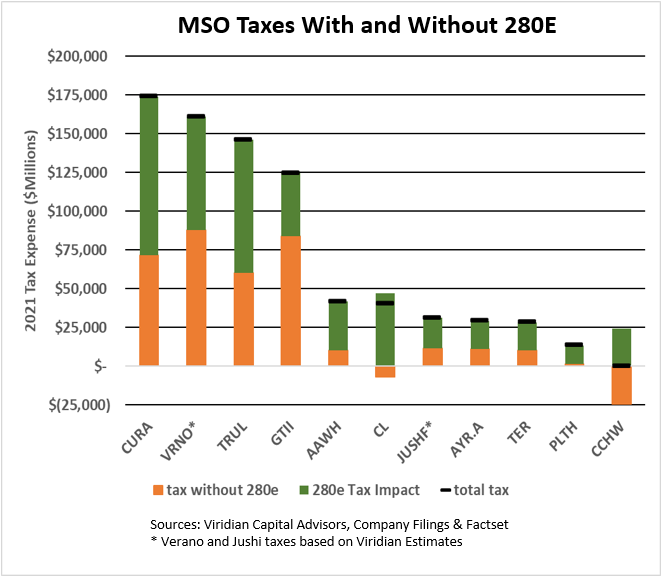
- Section 280E of the IRS tax code is one of the most reviled features of the current cannabis regulatory dichotomy. 280E essentially prevents the deduction of all expenses below the Cost of Goods Sold line, including interest expense and selling, general, and administrative expenses (although an entire cottage industry has developed to help companies “manage” their expense allocations to minimize 280E taxes).