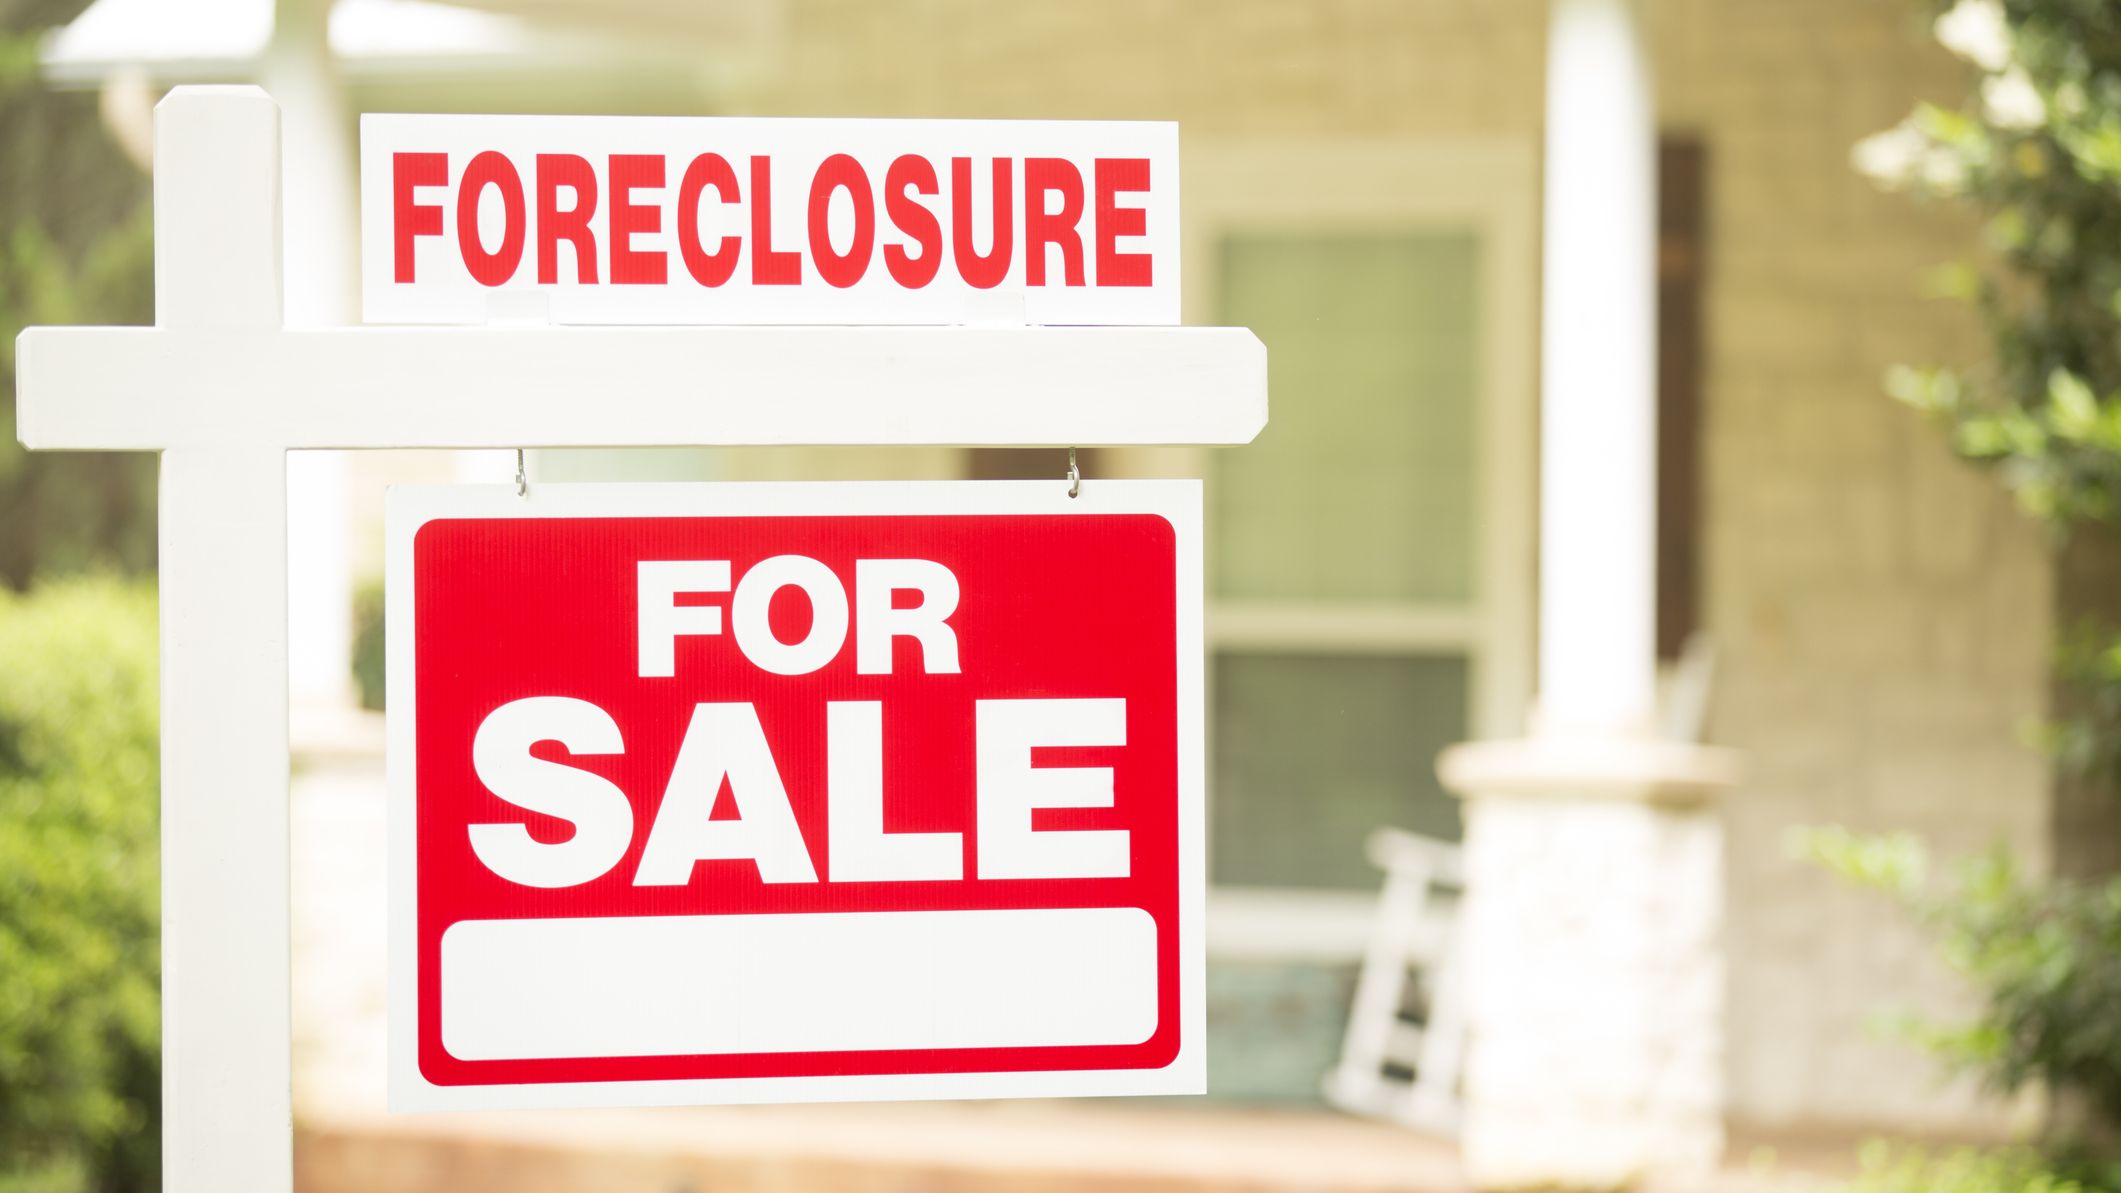
Before the 2008 housing crisis, some lenders offered homeowners 80/20 “piggyback” loans to help cover a down payment while avoiding private mortgage insurance (PMI). Borrowers took out a second mortgage or HELOC for 20% of the home’s value, leaving the primary mortgage at 80% and eliminating the need for PMI.
When home prices crashed, many of those second mortgages lost value and quietly went dormant. But now, loans long assumed to be settled are resurfacing.