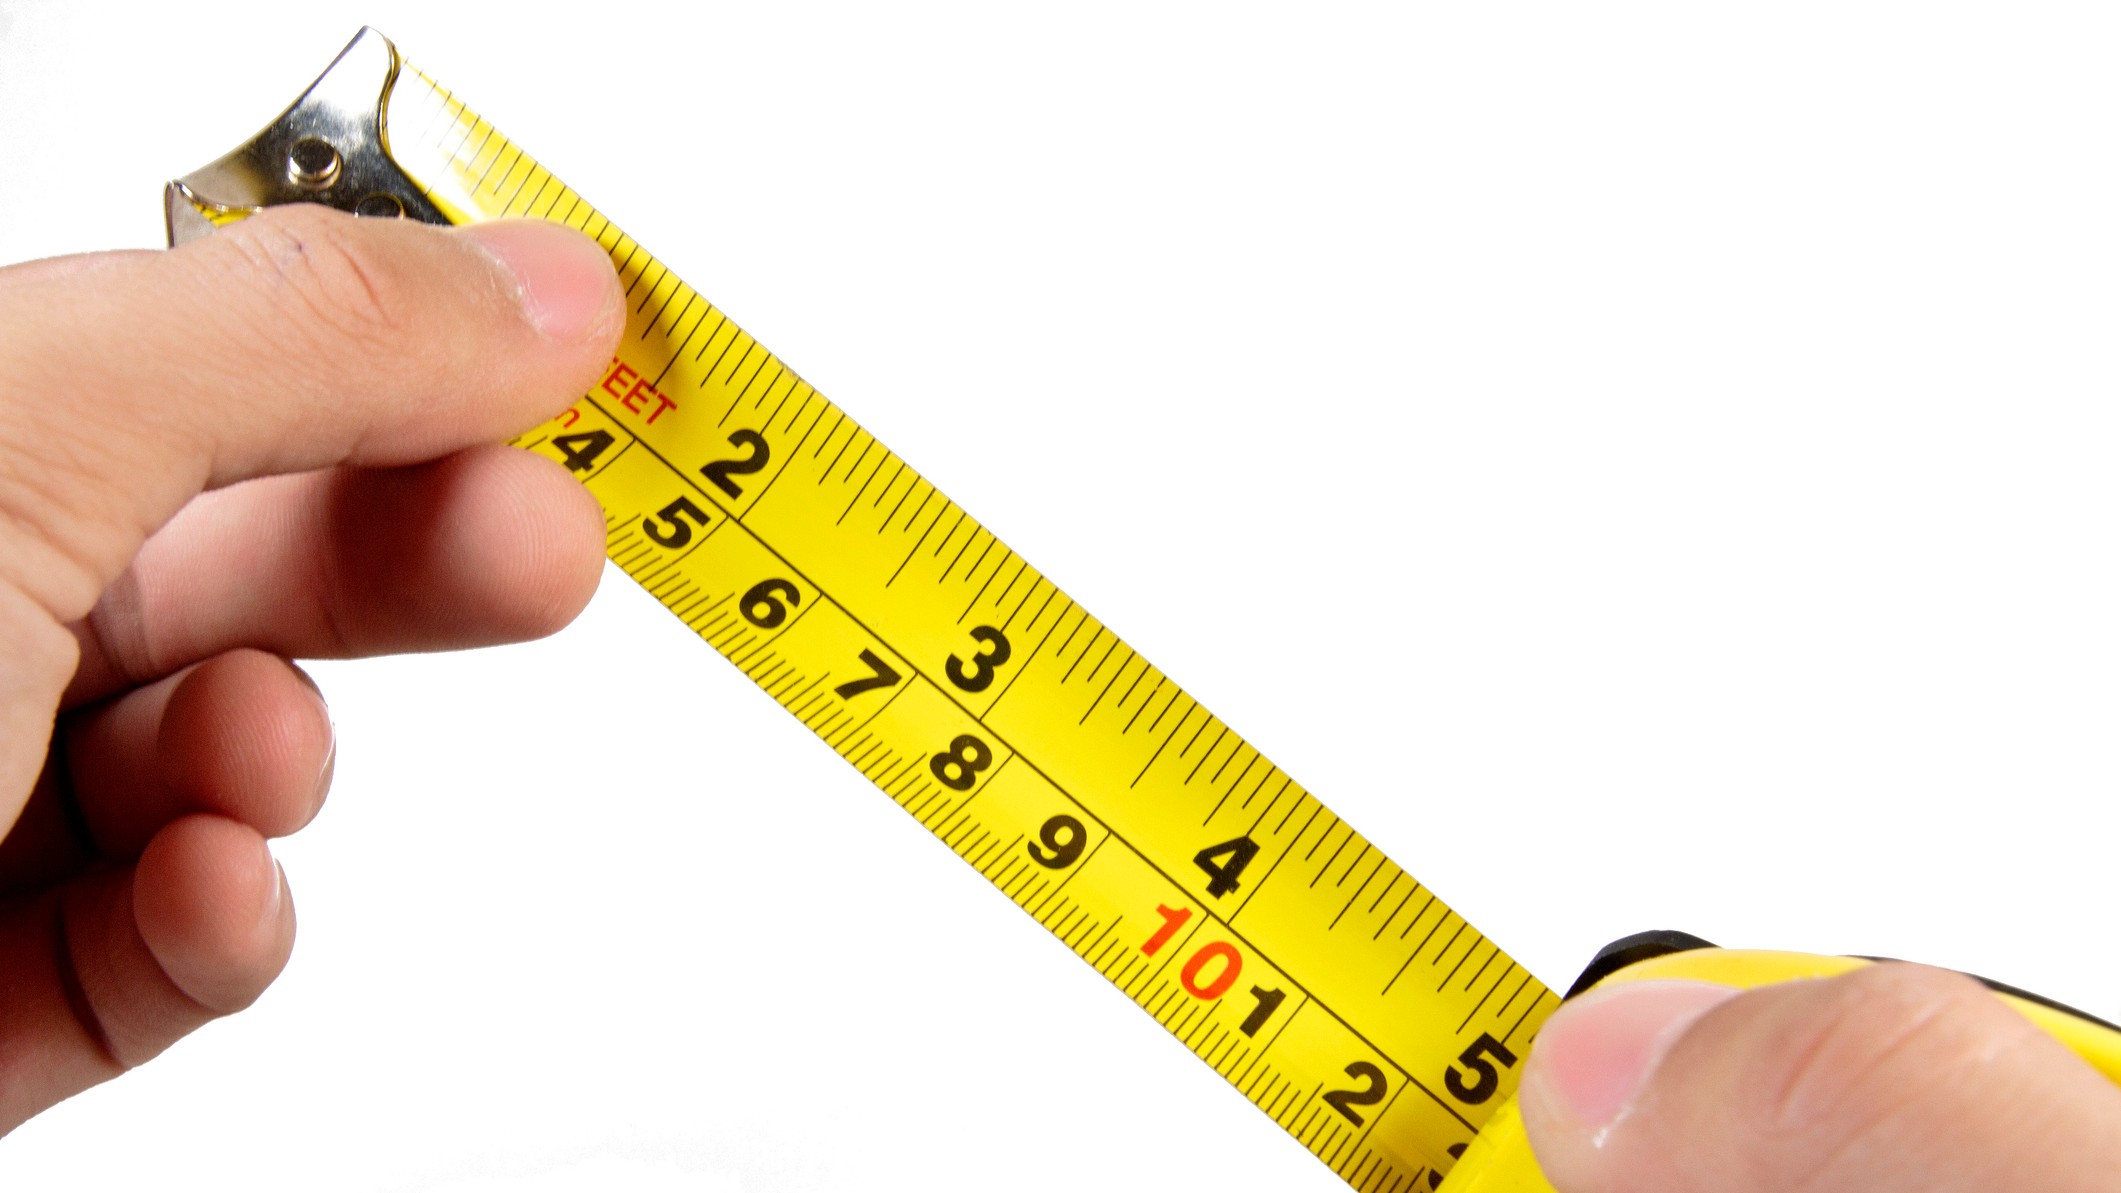
Try measuring something with a body part, and you’ll quickly see the problem with rules of thumb. Yet when it comes to money, many people still rely on them.The phrase “rule of thumb” dates to the 1600s, when thumbs were used as makeshift rulers. It’s a fitting metaphor for how people sometimes treat retirement planning: Eyeballing major financial decisions with rough shortcuts that can wildly miss the mark.One of the most well-known is the “120 minus your age” rule.According to this rule, you subtract your age from 120 to determine the percentage of your portfolio that should be in stocks, with the rest in bonds or other lower-risk assets. A 30-year-old might be 90% in stocks, while a 70-year-old would scale back to 50%.Simple, right? But that’s also the problem.As author Khaled Hosseini wrote, "Human behavior is messy and unpredictable and unconcerned with convenient symmetries." Rules like this treat everyone the same, when in reality, your emotions, habits and financial needs are just as important as your age. That can be especially problematic for retirement. A T. Rowe Price survey found that people with a formal retirement plan — one that accounts for their income goals, investment strategy and tax considerations — felt far more confident about their future than those without one.
"While the 120 rule can be a decent starting point, it often oversimplifies the complex nature of investor behavior." — Nathan Sebesta