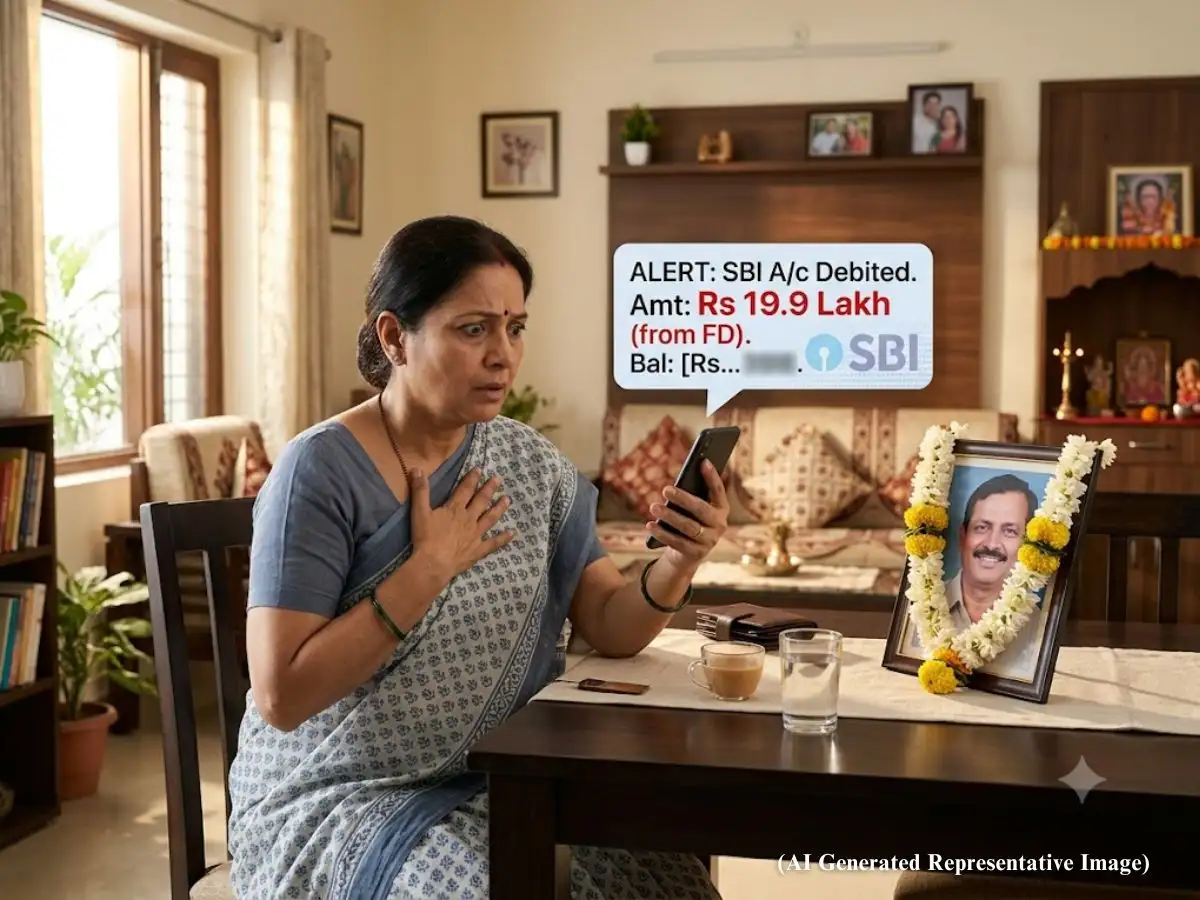
A widow’s fixed deposit was used by the State Bank of India to recover her late husband’s personal loan, even though she was not a borrower, co-borrower or guarantor in the loan. The Allahabad High Court has now ordered SBI to return Rs 19,90,693 with interest and pay another Rs 1 lakh as compensation.
The Lucknow bench of the Allahabad High Court also questioned the way the bank recovered the money. The court found that SBI had no legal basis to directly debit the woman’s account for her husband’s dues and directed the bank to refund the money within four weeks.
READ ALSO: PVR INOX asks to pay using UPI only; customer sends legal notice for refusing to accept cash payment
How much was the original SBI loan?
The woman’s husband had taken a Rs 15 lakh SBI Xpress Credit personal loan on November 3, 2020. He was working as an assistant professor at a hospital in Lucknow.
The court recorded that the woman was not a party to the loan. She was neither a signatory nor a consenting party and was not a co-applicant, co-borrower, guarantor, surety, indemnifier or nominee.
The loan was also covered by insurance through SBI General Insurance. The court order records that the husband had paid a premium of Rs 8,803 for the cover.
He died of Covid-19 on May 6, 2021.
What happened after the husband’s death?
SBI later sought to recover the outstanding loan amount from the woman. The bank issued a legal notice dated September 23, 2025, demanding Rs 13,87,382 along with interest and warning of legal action if the amount was not paid.
The bank had also placed her salary account on hold on September 12, 2025.
She approached the Reserve Bank of India Ombudsman over the issue, following which the hold was removed. The parties then continued discussions over the outstanding loan.
How did SBI recover Rs 19.9 lakh?
While discussions were continuing, SBI encashed a fixed deposit held in the woman’s name and debited Rs 19,90,693 from her account.
The FD had been opened in 2025 at SBI’s Ashiyana branch. The bank later transferred the account to its Jankipuram branch, where her husband had taken the loan.
The money was then debited from the FD and adjusted towards the deceased husband’s loan dues. After the debit, the account was transferred back to the Ashiyana branch.
The High Court specifically examined this sequence of events while deciding whether SBI had acted within its legal powers.
Why did the High Court question SBI’s action?
The bench of Justice Shekhar B Saraf and Justice Abdhesh Kumar Chaudhary noted that there was no privity of contract between the woman and SBI in relation to the loan.
The bank was also unable to show any law allowing it to directly debit the woman’s account for money owed by her husband.
The court took particular note of the FD being transferred from one SBI branch to another, the amount being debited and the account then being transferred back.
The bench said the process adopted by SBI “stinks of mala fide action” and described it as “abominable and clearly an anathema to banking practice”.
What was SBI’s defence?
SBI relied on an irrevocable standing instruction signed by the husband when he took the loan.
Under the instruction, the borrower had authorised SBI to collect amounts such as provident fund, gratuity, pension or similar dues in certain circumstances. He had also agreed to maintain his salary account with SBI until the loan was cleared.
The bank also relied on earlier court judgments concerning recovery of loan dues from retiral benefits.
The woman’s side argued that an instruction given by her husband could not give SBI the right to take money from an account belonging to her.
The High Court distinguished the cases cited by SBI. It noted that those cases concerned recovery from the borrower’s own retiral benefits, whereas the present case involved money belonging to a separate person who was not a party to the loan.
Could SBI recover the husband’s loan from the woman?
The High Court said SBI may have the right to proceed against the deceased borrower’s legal heir and recover his dues where permitted by law.
However, the bank has to follow the proper legal process while doing so.
The court said recovery cannot be carried out through arbitrary, capricious or unilateral action. It also described the bank’s conduct as a serious breach of the trust placed in banks as custodians of customers’ money.
How much must SBI pay back?
The High Court ordered SBI to immediately refund the entire Rs 19,90,693 taken from the woman’s account.
The bank must also pay interest at the fixed deposit rate that she was receiving on the amount. The refund has to be made within four weeks from the date of the order.
The court further awarded Rs 1 lakh as exemplary and punitive compensation for the bank’s actions.
The woman had sought Rs 25 lakh as compensation for alleged mental agony, emotional trauma and violation of her fundamental rights. The court considered Rs 1 lakh appropriate in the circumstances.
What is the total amount SBI has to pay?
The refund of Rs 19,90,693 and Rs 1 lakh compensation together come to about Rs 20.9 lakh.
This Rs 20.9 lakh figure does not include the additional interest payable on the FD amount.
The Allahabad High Court allowed the writ petition and directed SBI to comply with the order within four weeks.