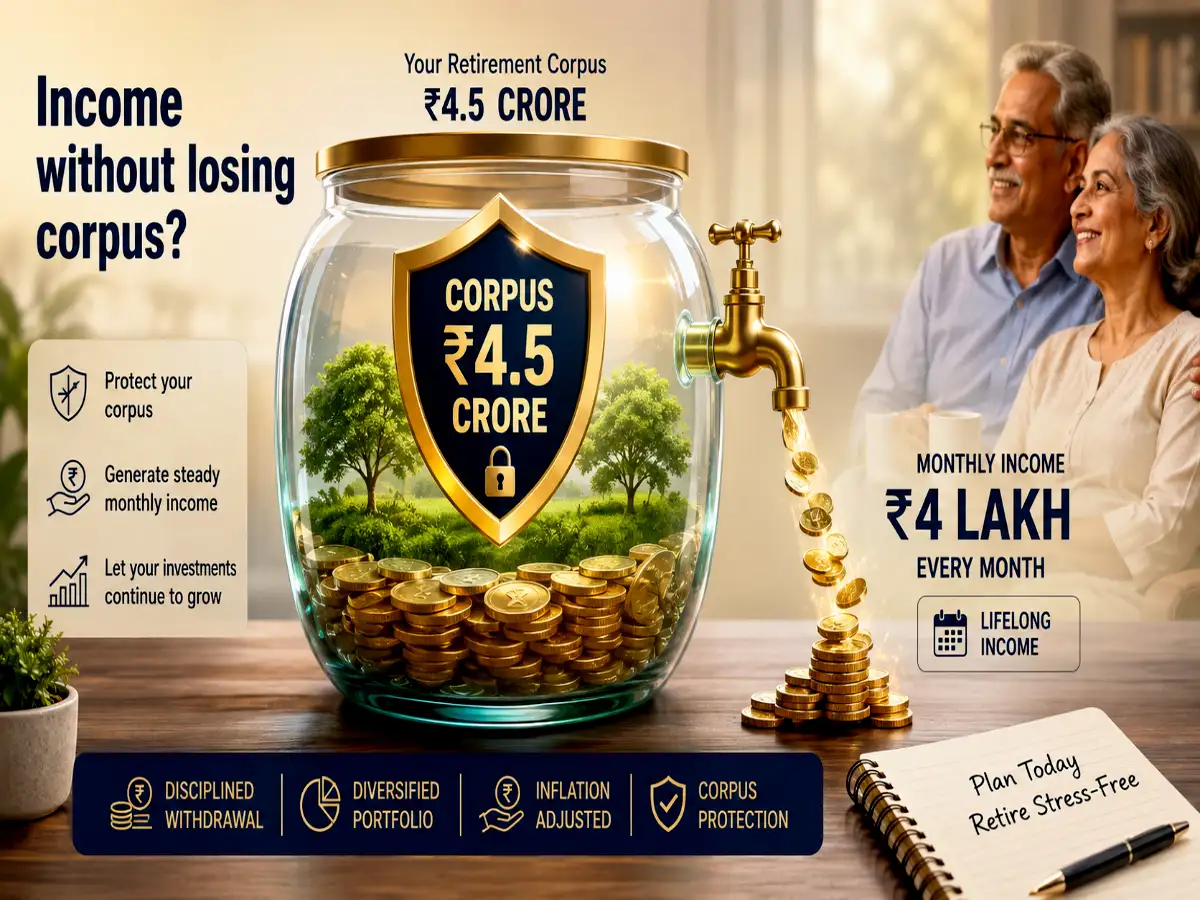
If someone retires with a Rs 4.5 crore corpus and invests that money in a fixed deposit (FD) at a 7% interest rate, they can expect to earn about Rs 37.33 lakh in interest over a year. Such a high interest income can push them in a 30% income tax slab, and if they have no other income, they might end up paying around Rs 7 lakh in taxes under the new tax regime. So, after taxes, their net income for the year would be roughly Rs 30.33 lakh.
Is there a way you can get better post-tax returns that also increase each year to keep up with inflation? Yes, it can be done! One option to reduce the tax burden is to invest the corpus in a mutual fund and set up a systematic withdrawal plan (SWP) to get a steady income. The great thing about this approach is that you can withdraw both the principal and gains, but you only pay income tax on the gains and not on the principal amount.
Moreover, long-term capital gains on equities are exempt up to Rs 1.25 lakh in a given year, and gains above it are taxed at a much lower rate of 12.5%. The higher your investment in equity instruments with a long-term horizon, the lower your tax outgo. As a result, your tax liability remains much lower if invested in equity MFs when compared to FDs, if you are investing Rs 4.5 crore.
How to invest Rs 4.5 crore in tax-efficient way
If you have a Rs 4.5 crore corpus, you can invest the amount in a mutual fund and start an SWP for monthly withdrawals, but only if you have the desired risk appetite to invest in growth assets like equities.
Rather than investing the entire sum in one fund, it is better to diversify and invest the corpus in five buckets of liquid, debt, equity savings, aggressive hybrid and equity mutual funds. While there could be many ways to diversify your investment, here we give one such allocation of a Rs 4.5 crore corpus.
Asset allocation of Rs 4.5 crore investment for retirement
| Investment bucket | Withdrawal duration | Return assumption | Allocation |
| Liquid Fund | Year 1 | 5% | ₹30 lakh |
| Debt Fund | Years 2–3 | 7% | ₹60 lakh |
| Equity Savings Fund | Years 4–5 | 7.50% | ₹80 lakh |
| Aggressive Hybrid Fund | Years 6–7 | 10% | ₹45 lakh |
| Equity Fund | Year 8 onwards | 12% | ₹2.35 cr |
| Total corpus | — | — | ₹4.50 cr |