Two investors can pursue the exact same market and end up with very different long-term results, not because one picked better winners, but because one avoided catastrophic losses the other didn't. One chases upside aggressively, accepting large downside risk as the reasonable cost of potentially large returns. The other treats avoiding permanent, irreversible loss as the actual foundation everything else gets built on, understanding that a single severe loss can undo years of otherwise solid gains. Buffett's rule, repeated so often it has become something close to a personal motto, isn't a claim that his investments never fluctuate in value; they clearly do. It's a statement about a specific kind of loss: the permanent, unrecoverable kind that comes from paying too much for something, misjudging a business fundamentally, or taking on risk that can wipe out capital rather than temporarily reduce it. Buffett's own career demonstrates this principle repeatedly, showing that disciplined restraint during periods of market euphoria often proves far more valuable over decades than chasing every apparent opportunity, however tempting the potential short-term rewards might initially appear.
Get breaking news anytime, anywhere. Download the TOI app now!
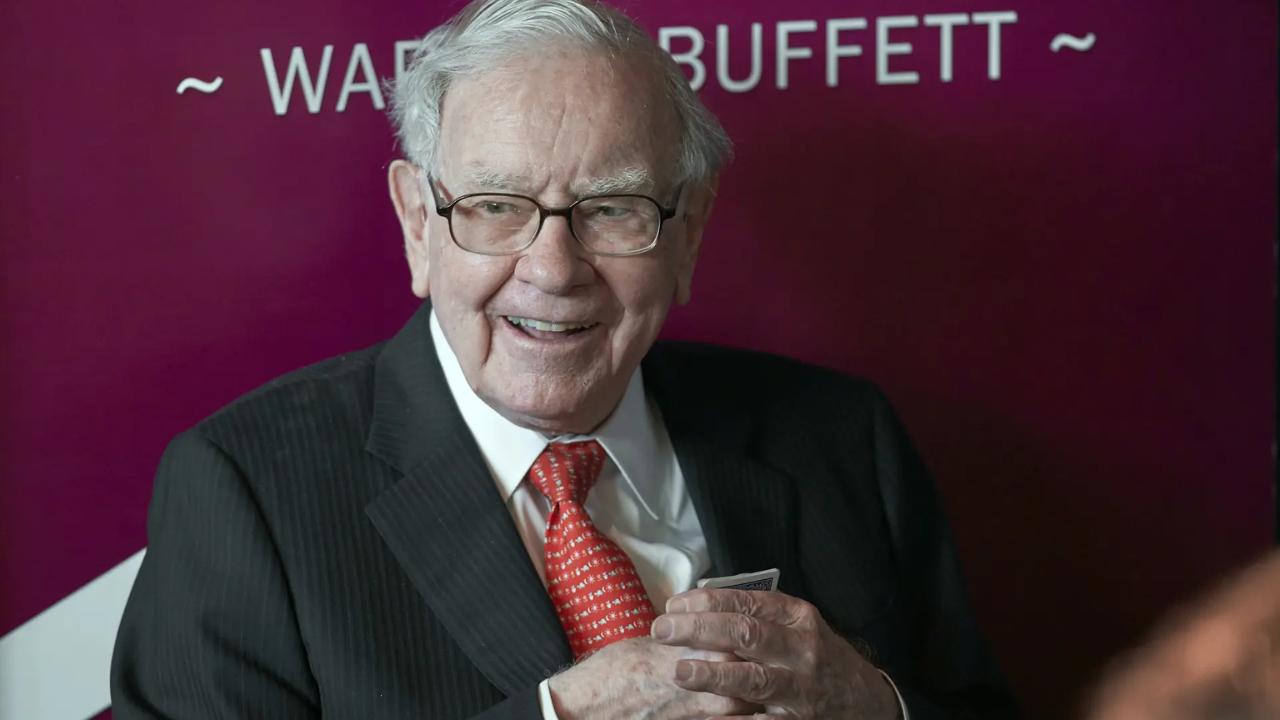
Quote of the day by Warren Buffett
"Rule No. 1: Never lose money. Rule No. 2: Never forget Rule No. 1."Written by an investor whose whole method is built around avoiding disaster
What gives this line extra weight is how closely it matches Buffett's actual documented investment philosophy over more than six decades running Berkshire Hathaway. Trained under Benjamin Graham at Columbia, Buffett built his entire approach around the concept of a "margin of safety," buying businesses and shares only when their price left substantial room for error, specifically so that a mistake in judgment wouldn't translate directly into a devastating loss of capital. That discipline is a large part of why Berkshire avoided the worst of the dot-com bubble in the late 1990s, when Buffett was publicly criticised for missing out on rapidly rising technology stocks he didn't understand well enough to value confidently, a decision that looked overly cautious for a couple of years and then looked prescient once the bubble collapsed.
Buffett has also been unusually open, for a public figure of his stature, about his own investment mistakes, including his often-cited regret over ever buying the original Berkshire Hathaway textile business at all, and other specific investments he has publicly acknowledged as errors in his annual shareholder letters. That openness reinforces rather than undermines the rule: the point was never that he avoids all mistakes, but that the mistakes he does make are structured to be survivable rather than catastrophic, precisely because avoiding permanent capital loss was always the first filter applied before any decision about potential upside.
A simple way to actually use this idea
The useful move here is treating downside protection as the first question in any significant decision, not an afterthought considered only after the potential upside has already gotten a person excited. It's easy to evaluate an opportunity almost entirely by how good the best-case outcome looks, while paying only glancing attention to how bad, and how recoverable, the worst-case outcome actually is. This applies well beyond investing. Career moves, major purchases, and personal commitments all carry the same asymmetry, where an appealing upside can quietly crowd out a clear-eyed look at what happens if things go wrong instead.
A fair test, before committing meaningfully to any risk, financial or otherwise, is to ask specifically whether a bad outcome would be a setback or something closer to unrecoverable. That question won't eliminate risk from any real decision, and Buffett himself has never claimed it should. It usually clarifies which risks are actually worth taking and which ones only look reasonable because their worst-case outcome hasn't been examined closely enough yet, which is precisely the gap his rule is designed to close before it becomes expensive.
Other famous quotes by Warren Buffett
- "Price is what you pay. Value is what you get."
- "Be fearful when others are greedy, and greedy when others are fearful."
- "It takes 20 years to build a reputation and five minutes to ruin it."