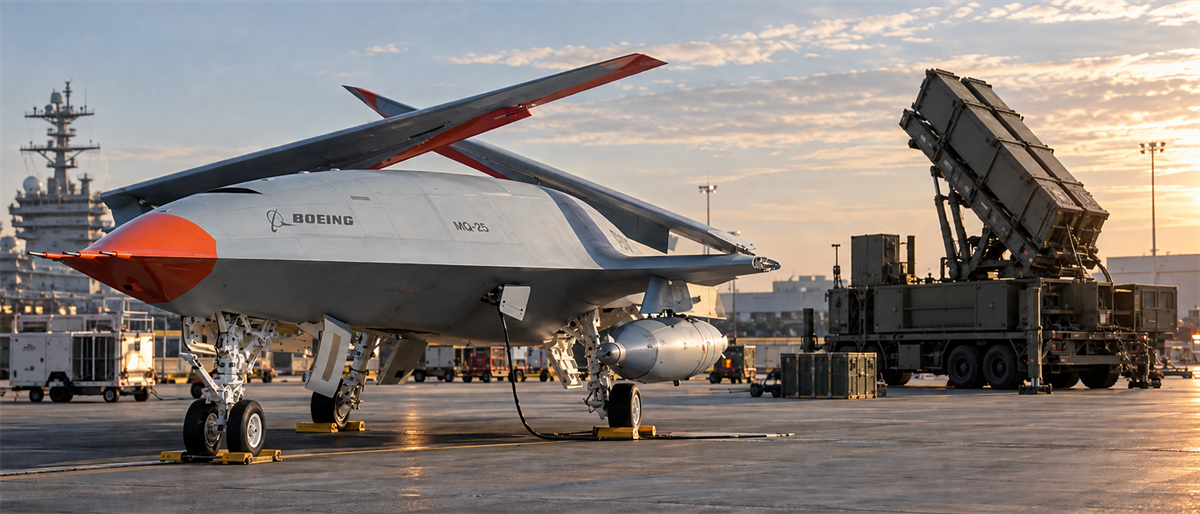
The Pentagon opened its checkbook on Sept. 14, and two of America's largest defense contractors were on the receiving end. Boeing (NYSE: BA) landed a $562 million Navy contract to move its MQ-25A Stingray refueling drone into low-rate initial production, its most significant milestone yet for a program long plagued by delays. Lockheed Martin (NYSE: LMT) hauled in more than $1.3 billion across three separate awards, anchored by a $1.21 billion contract for the Precision Strike Missile Increment 2. Yet in both cases, the market barely blinked. That shared shrug is where the story gets interesting, because the two stocks are being ignored for very different reasons.
Boeing: The Good News May Already Be in the Price
Boeing's muted response reflects a stock whose valuation already bakes in a great deal of optimism, despite this year’s sluggish returns. The market has spent the past couple of years betting on Boeing's turnaround under CEO Kelly Ortberg, and that faith is fully visible in the numbers. The stock trades at a striking 85 times trailing earnings on net margins of just 2.4%, with a balance sheet still carrying an enormous debt load from its troubled recent history. This is not a cheap stock pricing in bad news. It is an expensive one, pricing in a recovery that hasn't fully shown up in the financials yet.
That helps explain why another Pentagon win did little. When a stock already reflects lofty expectations, incremental good news struggles to move the needle. The optimism isn't baseless, though: Boeing's backlog keeps growing, its commercial production is recovering, and analysts still see real upside, with a Moderate Buy consensus and an average price target of $270.95, implying nearly 37% upside from the recent close near $198. But that target assumes the turnaround keeps converting into earnings. At 85 times profit, Boeing has to deliver, not just win contracts.
Lockheed: A Laggard the Market Won't Re-Rate...Yet
Lockheed's flat reaction stems from the opposite problem. Far from being priced for perfection, the stock has been left behind. Shares closed near $522, well below their highs from earlier this year and down roughly 24% from a 52-week peak of $692. Even as the company stacks contract win after contract win, the market has refused to reward it. The stock fell alongside other defense names in late September as reports of easing Middle East tensions deflated the wartime premium that had previously lifted the sector earlier in the year.
The valuation could hardly be more different from Boeing's. Lockheed trades at around 17 times forward earnings, pays a 2.64% dividend backed by a strong payout history, and generates far healthier margins. Its consensus price target of $637.56 implies about 22% upside. On the surface, that looks like a clear disconnect to BA: a cash-generating defense leader, winning business at a rapid clip, trading at a discount to both its history and its target.
Why the Contracts Might Not Be Enough
Despite the steady flow of awards, analysts rate Lockheed only a Hold, a telling signal that the market wants more than order flow before it re-rates the stock. Contracts fill the backlog, but they don't automatically translate into the metrics investors are watching: margin expansion, free cash flow conversion, and clarity on the timing of future defense budgets.
Real reasons might also help explain the caution. Lockheed's projected earnings growth sits at a modest 8.5%, and the company has been burned in recent years by fixed-price development programs that chewed through cash. So, in other words, the market might not be questioning whether Lockheed can win work. Rather, it is questioning how efficiently that work converts into profit and cash.
The Real Question
So, which stock could be the better potential opportunity? Well, Boeing offers the larger implied upside to target, but only if a richly valued turnaround delivers on lofty expectations. Lockheed offers a cheaper valuation, a real dividend, and a mountain of contract wins, yet sits under a Hold rating precisely because the market is holding out for proof beyond the backlog. Boeing's price may already reflect its good news, while Lockheed's may not yet reflect its own, but that gap will only close if Lockheed can turn its stacking contracts into the margins and cash flow investors are quietly demanding.
The article "Lockheed's Stock Hasn't Priced In Its Own Backlog—Boeing's Might Already Have" first appeared on MarketBeat.