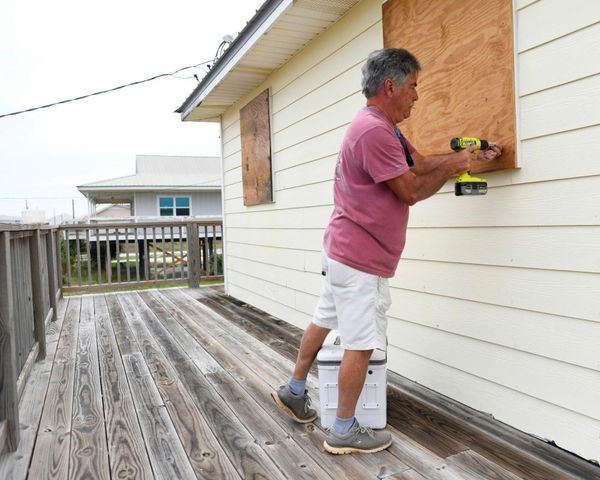

Living in a “high-risk” area is no longer just a line item on an insurance form; it can directly reshape what a home is worth on the open market. In fact, homes in areas exposed to wildfire, flooding, hurricanes, or other climate-related hazards can lose tens of thousands in value, with estimates ranging between $20K and $43K depending on the level of risk and insurance pressure. That shift does not come from a single dramatic event either. It builds slowly, quietly, and often catches homeowners off guard until resale time arrives. Buyers today pay close attention to long-term costs, not just sticker prices, and insurance affordability now plays a starring role in that calculation.
When insurance becomes expensive or difficult to secure, property values tend to feel the strain almost immediately. The housing market increasingly treats risk exposure like a hidden tax that follows the home year after year. And that “tax” often shows up in the final sale price, whether owners expect it or not.