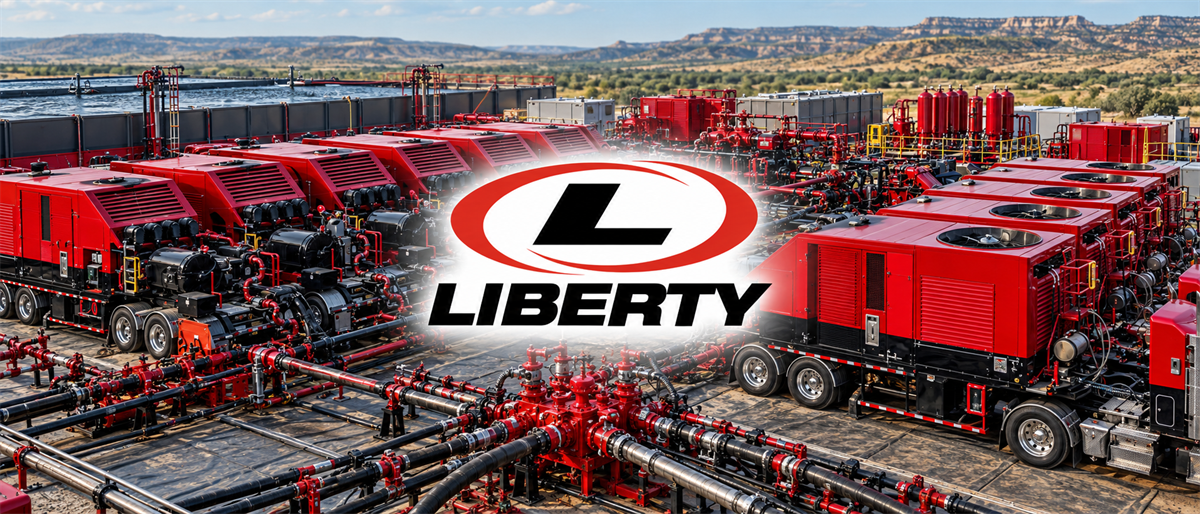
Liberty Energy (NYSE: LBRT) has an identity problem. Investors can't decide what kind of company they own.
For most of its history, Liberty was a hydraulic fracturing company. Its fortunes rose and fell with drilling activity. Now it is building something different: an on-site power business for AI data centers.
The market loved that idea in the spring. LBRT set a 52-week high of $34.48 in May. Then Liberty reported second-quarter results in July and disclosed the cost of that transition. Shares have since fallen below $20.
Here's the disconnect. UBS estimates the market is assigning only about $2 to $4 per share to Liberty Power Innovations, compared with the firm's own $14-per-share valuation. That gap shows just how differently investors are valuing Liberty's two businesses.
Spending Changed the Liberty Story
The market's reaction to those results was severe. Liberty beat second-quarter estimates for both earnings and revenue, but the stock still closed 22% lower following the report.
The reason was spending. Liberty raised its 2026 capital budget by nearly 50%, to about $1.5 billion, mostly for deposits on long-lead power equipment.
Investors wanted a signed contract to justify that spending. They didn't get one. Barclays blamed the sell-off on the missing contract timeline and the higher budget. Management also said meaningful income from power won't arrive until 2028.
Valuing Liberty Means Choosing Between Earnings and Cash Flow
MarketBeat data shows a trailing price-to-earnings (P/E) ratio near 25x and a forward P/E near 52x. That's because earnings are projected to fall about 42%. Therefore, the forward multiple is higher because analysts expect a weaker year in frac. The trailing number also flatters Liberty, since one-time investment gains boosted recent profits.
Discounted cash flow models make the split even clearer. Earnings-based models say the stock is undervalued. Free cash flow models say it's overvalued.
Both can be right. Heavy power spending is crushing free cash flow during the buildout, while earnings-based models look past it. The lens an investor chooses will decide whether Liberty looks cheap or expensive.
Liberty’s Legacy Business Can Only Carry So Much
Oil prices near $90 should be great news for a frac company. But that hasn't been the case.
Shale producers guided 2026 spending to $59.1 billion, down 5% from 2025. That's despite their most profitable quarter since 2022. Producers are pocketing the windfall instead of drilling with it.
Pricing hasn't helped either. Frac pricing failed to improve even with oil above $100. UBS just lowered its near-term frac estimates for Liberty.
That leaves the core business as a steady cash generator with a growth ceiling. That limitation helps explain the appeal of Liberty's power expansion.
Data Center Opposition Is Both Risk and Opportunity
There's a new headwind, too. Local opposition to AI data centers is spreading fast. In the second quarter alone, activists disrupted at least 45 projects across 27 states, worth $68 billion.
That's a real risk. Liberty's power business only grows if data centers get built.
But much of the backlash centers on rising utility bills. Behind-the-meter generation keeps data center demand off the local grid. If that argument wins over regulators, Liberty's model could become part of the solution.
The Chart Still Needs Confirmation
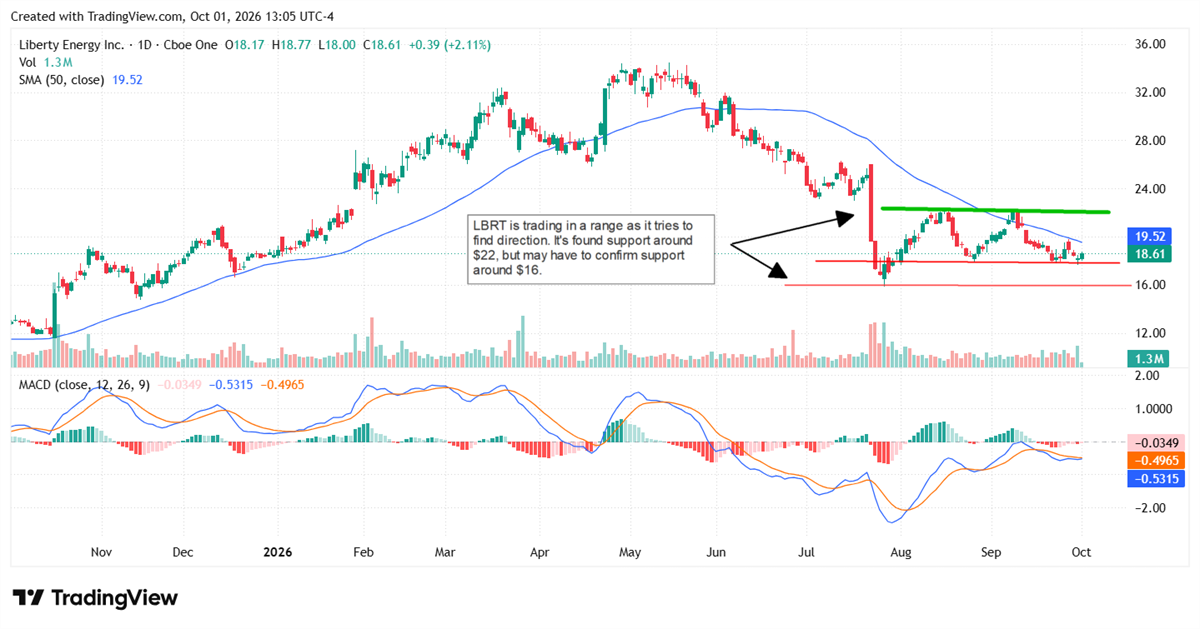
The chart reflects a stock still searching for a bottom. After July's gap down, shares hit a low near $16. Rallies in August and September both stalled near $22.
Liberty now trades below its declining 50-day moving average of about $19.50. The MACD sits just below its signal line, with a flat histogram. Selling pressure is fading, but there's no buy signal yet.
Support sits near $17.50, and below that, the July low around $16. Bulls need a close above the 50-day average, then a break above $22.
More Signed Megawatts Could Change the Valuation
Barclays shows how fast sentiment can flip. In July, it cut its target to $23.
On Sept. 28, it upgraded Liberty to Overweight and raised its target to $ 27, citing growing confidence that more long-term power contracts will be signed by the end of 2026.
Separately, UBS said Liberty remains confident it can sign at least 500 megawatts of energy service agreements before year-end.
That would build on Liberty's 1-gigawatt agreement with Vantage Data Centers, anchored by a firm 400-megawatt reservation for 2027, and its 3-gigawatt deployment target for 2029.
The Liberty Energy analyst forecasts on MarketBeat show a consensus rating of Moderate Buy, with an average price target of $27.54.
The Power Bet Still Has Plenty to Prove
The risks are real. Liberty carries about $1.3 billion in convertible notes. Their conversion prices sit near $34.50 and $37.44, so dilution isn't an immediate threat. Still, the debt adds pressure to deliver.
Frac weakness could also deepen. And contract timing could slip into 2027.
But markets pay for what they can see. Today, they see a frac company spending heavily on an unproven business. A signed contract would let investors see a power company instead. Until then, Liberty remains a show-me story.
The article "Liberty Energy’s AI Power Push Has Wall Street Divided" first appeared on MarketBeat.