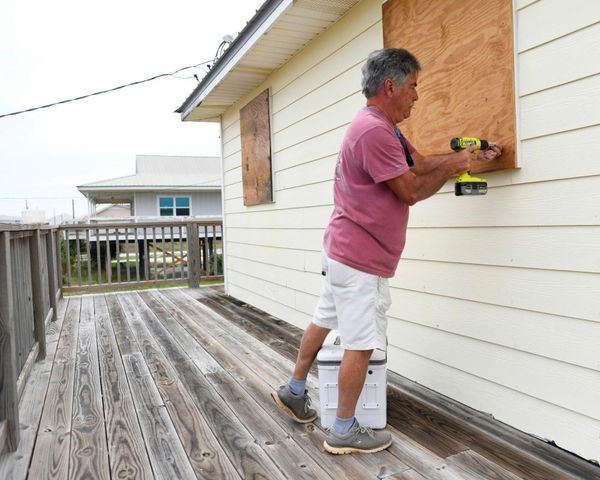

California’s housing landscape just got a subtle but meaningful shake-up, and it revolves around money sitting in a very specific place. When property damage happens and insurance payouts get delayed or held by lenders, AB 493 now steps in with a new rule: lenders must pay 2% annual interest on those insurance funds. That detail might sound small at first glance, but it reshapes how homeowners experience the already stressful aftermath of property damage. Suddenly, the wait for repairs carries a financial ripple that no longer sits quietly in the background.
This change targets a situation many homeowners never think about until disaster strikes. After damage occurs, insurance funds often pass through lenders before reaching the homeowner or contractor handling repairs. Those funds sometimes sit idle during the repair process, creating frustration when timelines stretch longer than expected. AB 493 adds a new layer of accountability by attaching interest to that waiting period, shifting how lenders manage those funds.