
Pentair plc (PNR), headquartered in London, the United Kingdom, provides various water solutions. Valued at $8.9 billion by market cap, the company designs, manufactures, and sells commercial and residential water treatment products and systems, including pressure tanks, control valves, activated carbon, commercial ice machines, conventional filtration, and water treatment systems.
Companies worth $2 billion or more are generally described as “mid-cap stocks,” and PNR fits right into that category with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the specialty industrial machinery industry. Pentair’s edge comes from trusted brands like Everpure, Fleck, and Sta-Rite, and a strong commercial client base in Water Solutions. Its wide product range and energy-efficient Pool innovations meet diverse needs, while ongoing R&D keeps it ahead of market and environmental demands, driving loyal revenue.
Despite its notable strength, PNR shares have slipped 51.3% from their 52-week high of $113.95, achieved on Oct. 3, 2025. Over the past three months, PNR stock has declined 23.5%, underperforming the Nasdaq Composite’s ($NASX) 6.5% gains during the same time frame.
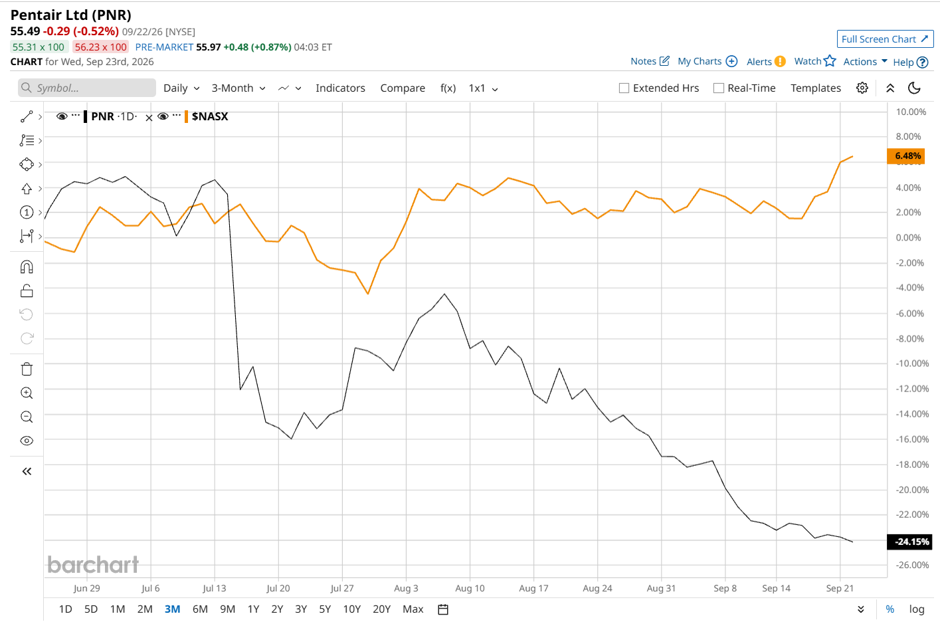
Shares of PNR fell 46.3% this year and dipped 49.2% over the past 52 weeks, considerably underperforming NASX’s YTD gains of 17.2% and 20.7% returns over the same time frame.
To confirm the bearish trend, PNR has been trading below its 50-day moving average since late October, 2025, with some fluctuations. The stock is trading below its 200-day moving average since early February.
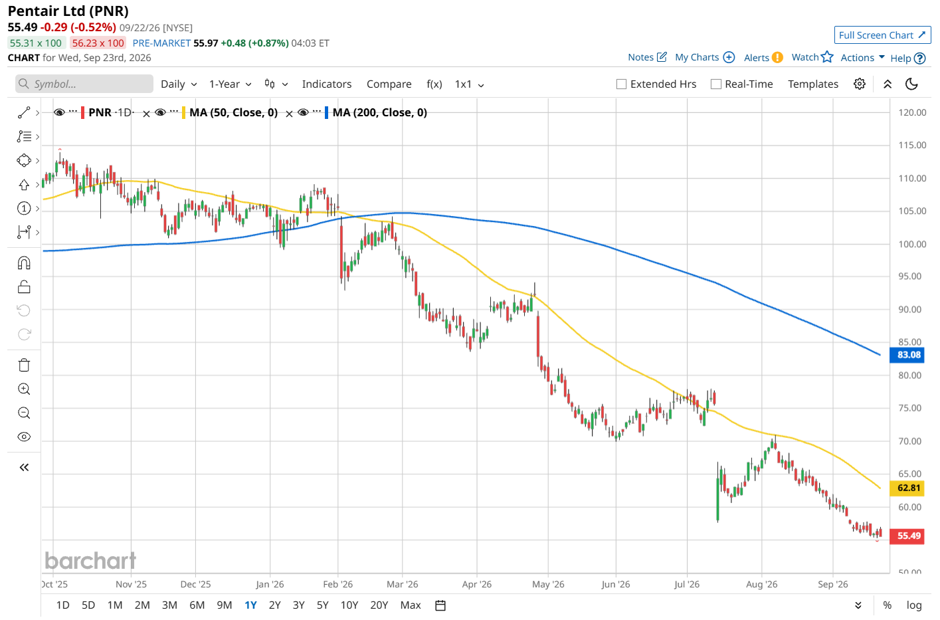
PNR has underperformed primarily due to severe, unexpected weakness in its high-margin Pool segment, driven by channel inventory destocking and a sharp downward revision of its financial outlook. After projecting positive sales growth earlier in the year, the company shocked the market in July by revealing a near 17% year over year revenue drop for Q2, estimating that distributor inventory right-sizing stripped roughly $170 million from Pool segment sales and $105 million from segment income. The sudden operational headwind caused management to slash full-year 2026 sales and earnings guidance, coinciding with an abrupt CFO departure and triggering a wave of investor securities fraud lawsuits. This combination of severe distributor inventory corrections, reduced forward guidance, executive turnover, and ongoing litigation has severely damaged investor sentiment and weighed down the stock's performance.
In the competitive arena of specialty industrial machinery, Xylem Inc. (XYL) has taken the lead over PNR, with a 20.7% downtick on a YTD basis and 24.5% losses over the past 52 weeks.
Wall Street analysts are reasonably bullish on PNR’s prospects. The stock has a consensus “Moderate Buy” rating from the 18 analysts covering it, and the mean price target of $78.62 suggests a notable potential upside of 41.7% from current price levels.