
With a market cap of $130.7 billion, Chubb Limited (CB) is a global insurance leader providing a broad range of commercial and personal insurance solutions across 54 countries and territories. Its offerings span property and casualty, personal accident and supplemental health, reinsurance, and life insurance for a diverse range of customers.
Companies valued at more than $10 billion or more are generally considered “large-cap” stocks, and Chubb Limited fits this criterion perfectly. With strong financial capabilities, extensive distribution networks, and local operations worldwide, Chubb employs approximately 45,000 people globally.
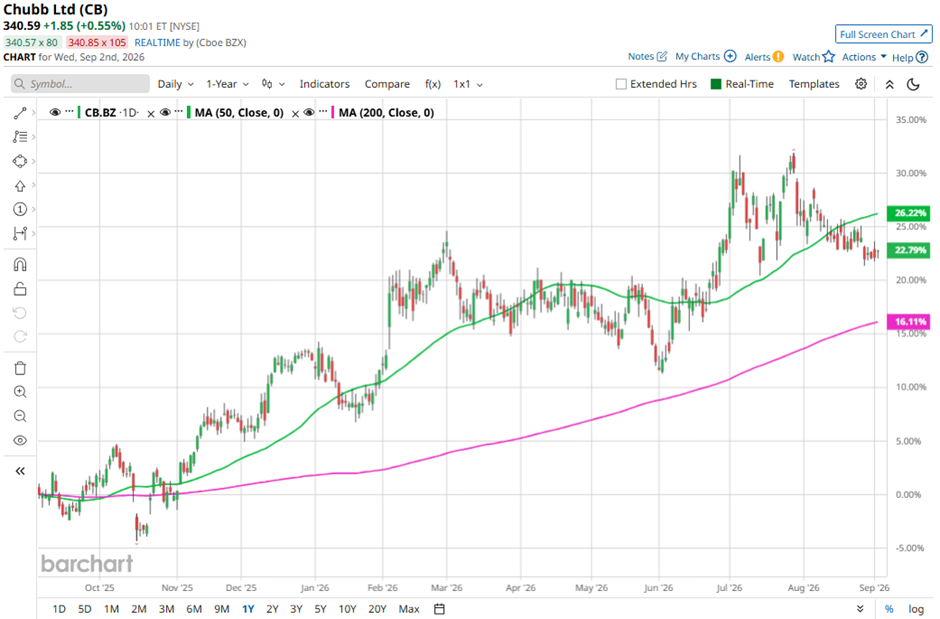
Shares of the Zurich, Switzerland-based company have pulled back nearly 7% from its 52-week high of $365.91. CB stock has risen 8.7% over the past three months, outpacing the S&P 500 Index’s ($SPX) marginal gain over the same time frame.
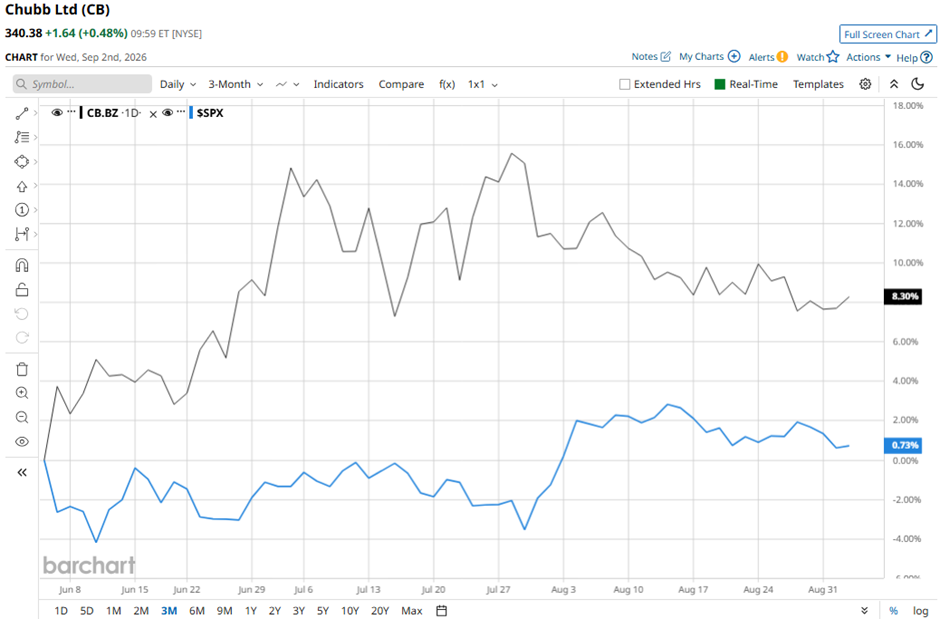
Shares of Chubb Limited have increased 22.6% over the past 52 weeks, outperforming SPX’s 19.1% return over the same time frame. However, the stock is up 8.8% on a YTD basis, underperforming SPX’s 11.6% increase.
Yet, the stock has been trading above its 200-day moving average since October last year.
Chubb Limited reported Q2 2026 results on Jul. 21, with core operating income increased to $2.84 billion, or $7.26 per share, reflecting stronger underwriting and investment returns. Pre-tax net investment income climbed 12.3% to $1.76 billion and global P&C net premiums written rose 2.8% to $11.99 billion, supported by firm insurance demand. Profitability also improved as the P&C combined ratio fell to 83.8% and catastrophe losses declined to $475 million, strengthening overall underwriting performance.
In comparison, rival The Progressive Corporation (PGR) has underperformed CB stock. PGR stock has fallen 9.8% over the past 52 weeks and 2.6% on a YTD basis.
Despite Chubb Limited's outperformance over the past, analysts are cautiously optimistic about its prospects. The stock has a consensus rating of “Moderate Buy” from the 26 analysts covering it, and the mean price target of $369.44 is a premium of 8.5% to current levels.