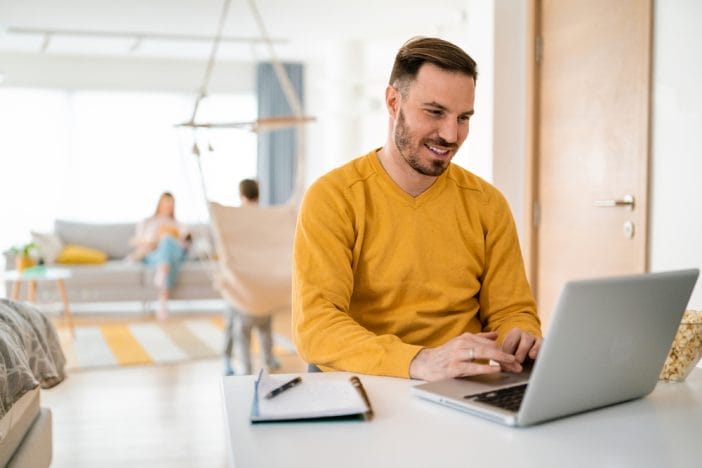
Remote work exploded across the United States, turning spare bedrooms, kitchen corners, and even closets into full-time workspaces. That shift brought comfort and flexibility, but it also introduced a hidden financial risk most people never think about: insurance blind spots. Many assume homeowners or renters insurance automatically protects everything inside the home, including business gear and work-related liabilities. That assumption can backfire fast when a claim gets denied after damage, theft, or even a liability issue tied to work activity. Insurance companies don’t always extend coverage to home-based business activity, and those fine-print exclusions matter more than ever.
A laptop crash or a spilled coffee might seem minor until replacement costs hit thousands of dollars with no reimbursement in sight. Remote workers across the U.S. often discover too late that standard policies don’t match modern work life. The gap between “working from home” and “running a home business” creates confusion that insurers don’t ignore.