Insiders are betting big on pharma in Q3, highlighting opportunities for speculative investors. Speculation is the key word, as these stocks offer risks alongside potentially strong rewards. The question is what is driving the interest from insiders—and how big the potential gains could be.
Braveheart Bio Boldly Goes Where Few Have Gone Before
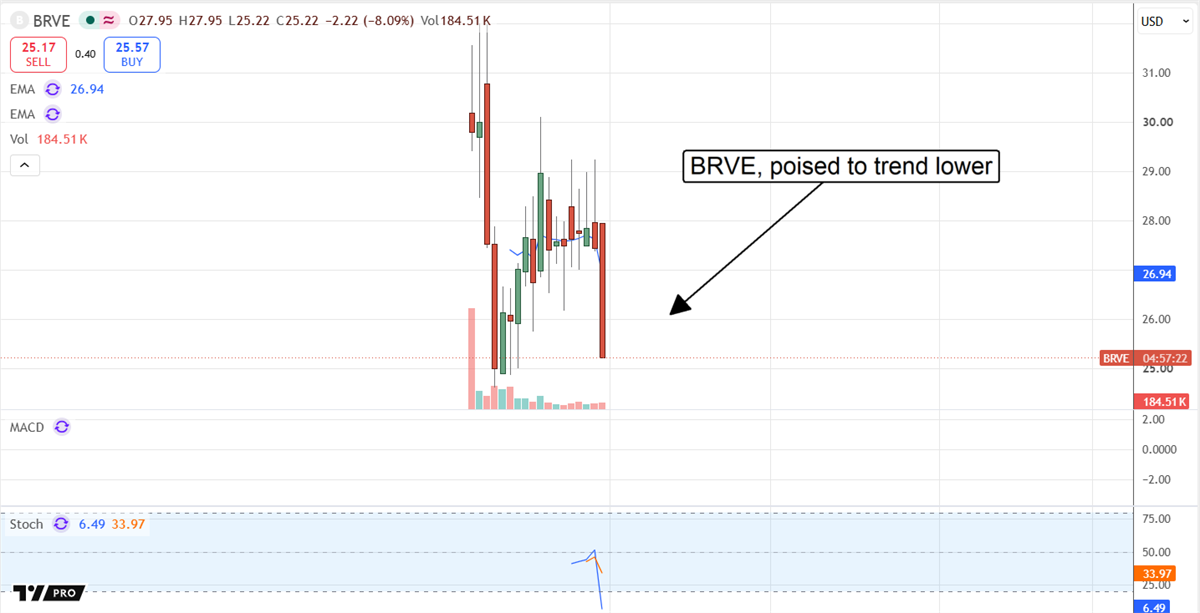
Braveheart Bio (NASDAQ: BRVE) is a late-stage biopharmaceutical that completed its IPO earlier this year. The company’s lead candidate, BHB-1893, is transitioning to phase 3 trials after positive phase 2 results and offers substantial upside for investors.
The therapy targets hypertrophic cardiomyopathy, a segment worth upward of $5 billion in annual sales at peak. Opportunities include disrupting established leaders while penetrating a largely underserved market. Analysts estimate that as few as 20% of eligible patients are currently treated.
Insiders buying this stock include a host of C-suite execs, including the CFO, CDO, and numerous directors, alongside early investors and major shareholders. Their purchases coincided with the IPO and with expanded positions at near-record prices, pushing total insider ownership to over 17%.
Institutional ownership remains low because venture capital and private equity firms primarily own the company. The risk is that they sell into any rallies, creating an overhang until market dynamics change. That is likely over the coming quarters, with phase 3 trials due to begin, but the real catalyst, the results, is unlikely until late in 2027 at the earliest. Looking ahead, the treatment is undergoing several studies, with results expected over the next two to three years to drive market sentiment, assuming a positive result in the first.
Analysts' coverage is light but reflects an optimistic outlook for the stock. It currently has five ratings, with a consensus Buy rating and about 80% upside. The likely outcome is that this stock trades sideways within its range over the next year, potentially trending lower until signs of traction emerge. While Braveheart's potential is bright, it is burning through capital and is unlikely to cease doing so within the next 12 to 18 months.
BlossomHill Therapeutics: The Higher Risk Option
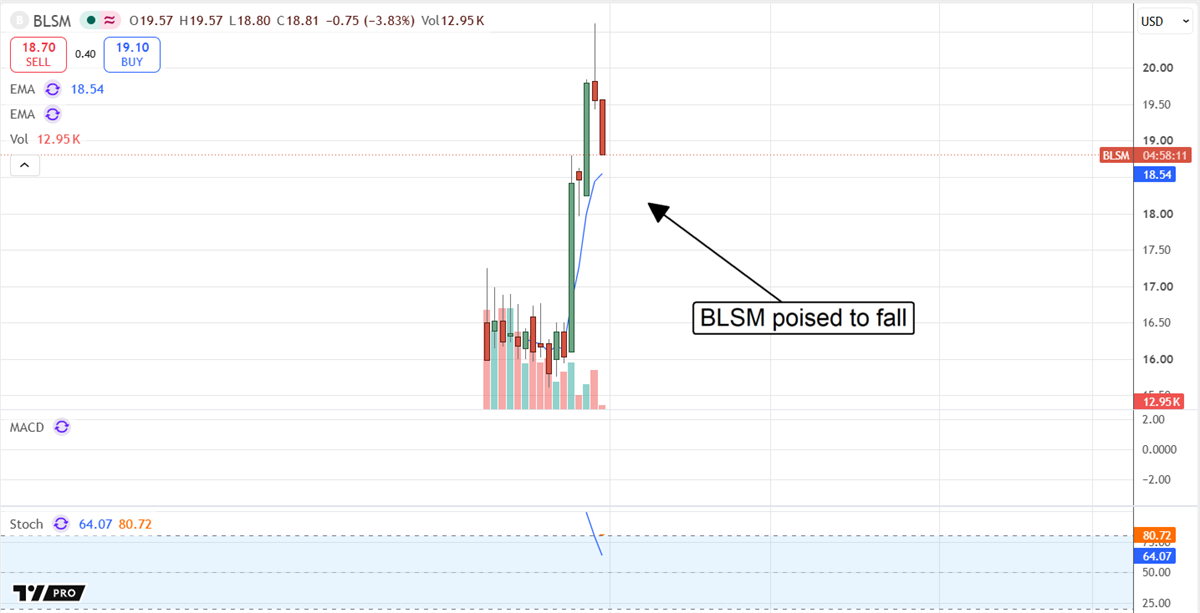
BlossomHill Therapeutics (NASDAQ: BLSM) is a cancer-focused biopharma in a similar position to Braveheart Bio. However, while Braveheart Bio has a candidate entering late-stage trials, BlossomHill Therapeutics does not. Its three candidates are preclinical or in early phase 1 trials, so it's still determining whether it's worth proceeding. In this light, it has an even longer runway to revenue and profits, though it has a larger end market.
Insiders buying this stock include a similar mix of C-suite execs and directors, including OrbiMed Advisors. OrbiMed Advisors is a global investment firm focused on health care with over $20 billion under management. It acts as a lead investor, investing across the lifecycle and helping companies grow into their potential.
Analysts and institutional coverage highlight the stock's risks. Institutions hold a token 5% of shares, while no analysts with coverage of BlossomHill are tracked. With this in play, BLSM shares are ripe for short-selling, sharp corrections, and downtrends, despite the fast-track status one of its candidates achieved.
Elanco: Pet-Friendly Investment With Robust Pipeline, Growth, and Profits
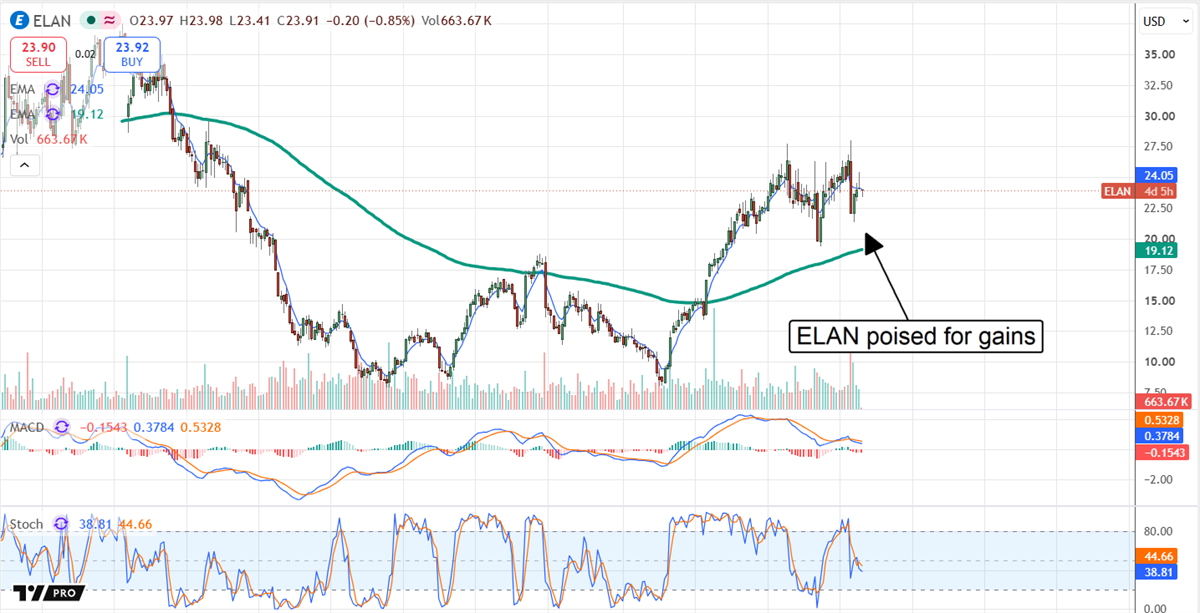
Elanco (NYSE: ELAN) is not a mainstream health care company, as it focuses on pets and livestock. The business is separated into two operating segments: Companion Animal and Livestock, providing name-brand vaccines, medicines, and technology across segments. Catalysts in 2026 include a corporate turnaround centered on a robust pipeline. The latest launch already achieved blockbuster status, and strength is expected to continue as new products launch.
Insiders buying include directors, the CFO, and an executive vice president, extending the trend—insiders have been buying this stock for the last two years. Analysts rate it as a Moderate Buy and show modest conviction, with 13 covering the stock. They have a bullish bias and see the stock rising 20% to the consensus target, highlighting the growth and profit potential presented.
Unlike BRVE and BLSM, ELAN did not recently go public. This stock has been trading for several years and is in the midst of a price recovery. After a 2023 decline on sluggish growth and lackluster prospects, the bottom was hammered out in 2024, and the rebound is now gaining momentum. The consensus price target of $29 would be enough enough to break the stock out of consolidation and set a new high, opening the door to a larger advance over time.
Elanco’s biggest risks are operational, including foreign exchange changes, product launches, adoption, and regulatory changes. Foreign exchange effects hit results quarterly and can swing from helpful to not in a single quarter. Product launches and adoption pose a greater risk because they increase upfront costs and can lead to weaker-than-expected results when delayed, sluggish, or disrupted by competition.
The article "Insiders Are Betting Big on These 3 Healthcare Stocks" first appeared on MarketBeat.