Farmers seeking commodity cost relief received bad news this week. Six of the eight major fertilizer inputs drifted higher in price again in September, reversing a trend that saw many raw materials retreat from their highs in August.
The closure of the Strait of Hormuz immediately drove up fertilizer components like ammonia, phosphates, urea, and potash, and many companies in the sector saw their stocks rise in unison. But once the shock wore off, fertilizer input price growth normalized, and these stocks declined. However, much like the refining trade, the fertilizer trade has become about spreads, not raw input prices. And the three companies we’ll discuss trade today at a discount to their strong margins.
Why Seasonality and Geography Are Driving the Fertilizer Trade
Summer officially ended on Sept. 21, and many investors in the Northeast immediately felt the cooler temps and wetter conditions. Fall has arrived, and that means winter isn’t far behind. But Europe is likely to feel the most pain this winter because of natural gas prices. The spread between gas prices in Europe and the U.S. is reaching historic levels, and that’s an arbitrage opportunity for fertilizer companies that turn natural gas into nitrogen.
The natural gas industry doesn’t measure product in barrels like oil, but in energy units known as British thermal units (Btu), with an industry standard block of One Million British thermal units (MMBtu). A Btu is generally considered the heat quantity required to raise the temperature of a pound of water, which makes more sense for natural gas than measuring by volume. It also provides an easy unit for trading and highlights the disparity between European and U.S. prices. The main Dutch hub supplying Europe reported a spot price of approximately $27 per MMBtu on Sept. 11, compared to the $2.80 per MMBtu spot price reported at Henry Hub. The same unit of gas in the United States costs 9 times more in Europe, and this spread is the primary thesis currently behind the fertilizer trade.
It takes about 30 MMbtu of natural gas to produce a ton of ammonia, the key ingredient in nitrogen-based fertilizers. With EU gas storage already well below its five-year average and Middle East and Russian plants possibly years away from returning to full capacity, this premium is likely to continue, and U.S. producers can sell into these markets using feedstock that’s a fraction of the price. In July, Europe’s leading crop nutrition company, Yara, bet on the duration of these spreads by purchasing Gulf Coast Ammonia in Texas, which is ramping up to open before the end of 2026.
3 Fertilizer Companies Benefiting From Gas Spreads
The following three companies profit from the spread between raw materials and finished fertilizer products, but each stock has pulled back from its spring high despite spreads trading near unprecedented levels. A quick reopening of Hormuz could bring these spreads crashing down, but a prolonged conflict (and cold winter) could push them even higher.
CF Industries: Margins Rising Faster Than Costs
CF Industries Holdings Inc. (NYSE: CF) is a global nitrogen producer operating in North America and Europe. This might seem like a counterintuitive choice at first since the company’s own gas cost rose significantly in the first half of 2026, up to $4.01 MMBtu from $3.52.
But in Q2 2026, CF Industries reported gross margins of 51.5%, up from 39.9% a year ago and higher than the first-half average of 44.9%. Management expects tight conditions in Europe to remain through 2027, and the company raised its mid-cycle baseline free cash flow and EBITDA projections.
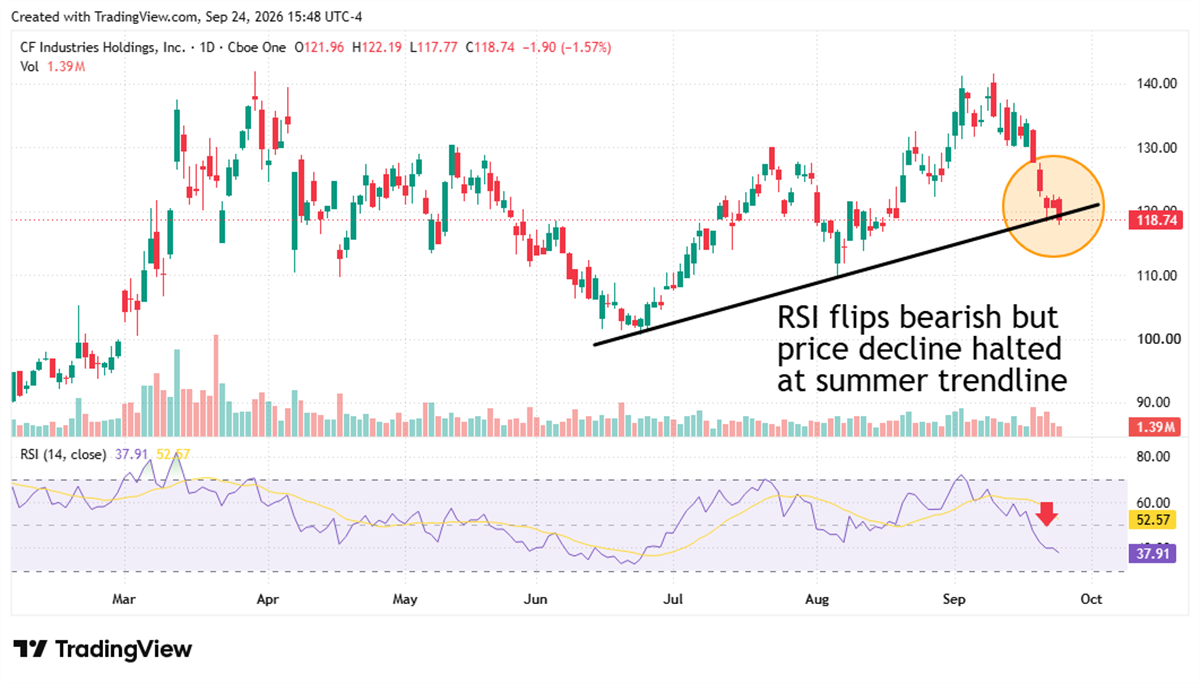
CF shares could be reaching a short-term bottom if the current trendline holds. After pulling back from its March high, the stock has been gradually recovering those gains, albeit in a volatile trend. The Relative Strength Index (RSI) has retreated into bearish territory, but the price has once again hit support at the trendline, and investors should watch for a reversal over the next few sessions.
CVR Partners: Input Insulation and Structure Offer More Upside
CVR Partners LP (NYSE: UAN), which produces nitrogen-based products such as ammonia and urea, offers a different way to play the fertilizer trade.
The company is structured as a variable-distribution Master Limited Partnership (MLP), meaning it pays a distribution based on quarterly cash generation rather than a fixed dividend. When input prices like ammonia and urea rise, the payout CVR shareholders receive rises too.
As of Q2 2026, the company is operating at 99% ammonia capacity and realizing $791 per ton of ammonia and $392 per ton of urea ammonia nitrate (UAN). Additionally, CVR’s Kansas plant runs on petroleum coke, so half the company’s output is insulated from violent gas price swings.
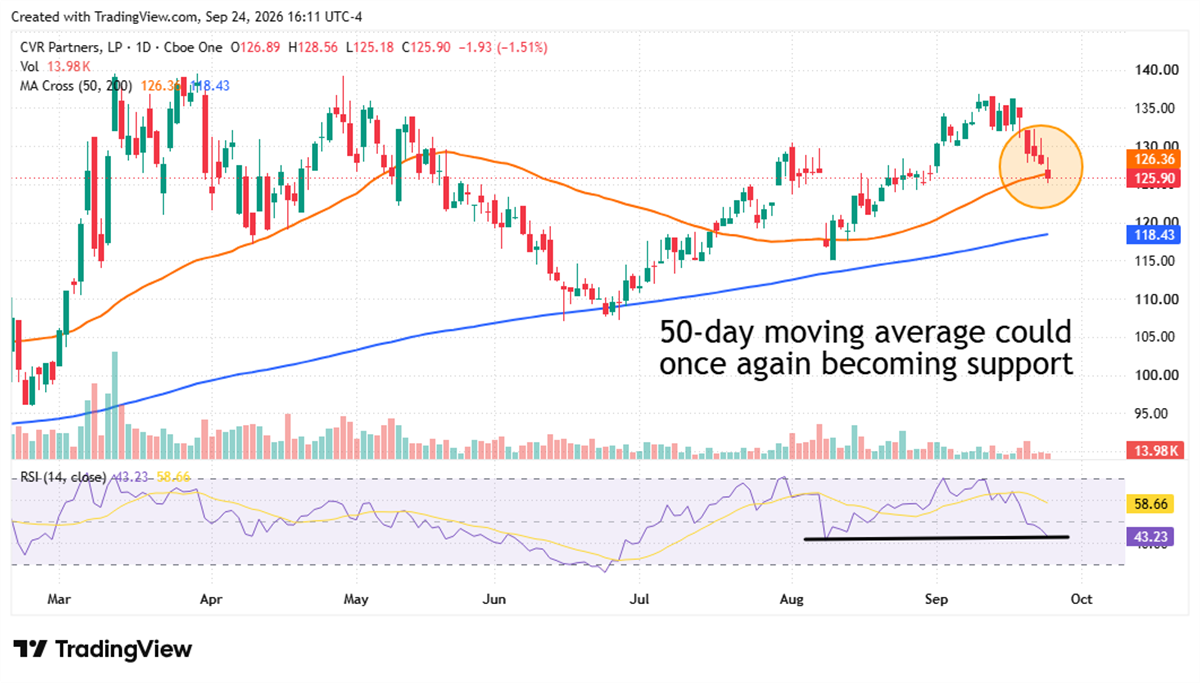
The RSI is also in bearish territory on the UAN chart, but it hasn’t dipped below the previous low from August, and the share price is now colliding with the 50-day moving average. CVR investors don’t need to rely on stock price appreciation if gas spreads keep dividends high, but a bounce off the 50-day moving average would be a good sign for future gas spreads.
LSB Industries: Highest Leverage But Entering Winter at Full Production
LSB Industries Inc. (NYSE: LXU) is the high-risk, high-reward fertilizer play, but it also has the best setup heading into winter. In Q2 2026, adjusted EBITDA jumped nearly 30% to $53 million despite absorbing $28.8 million in costs from the El Dorado and Pryor turnarounds.
Now that this maintenance is in the rearview mirror, LSB can enter the winter season at full production and take advantage of its low gas costs ($2.96 MMBtu in Q2, expected $3.20 in Q3). An investment in LSB also offers diversification away from the fertilizer trade since a portion of the ammonia nitrate output goes toward the industrial mining industry, which tracks more closely with metals like gold and copper.
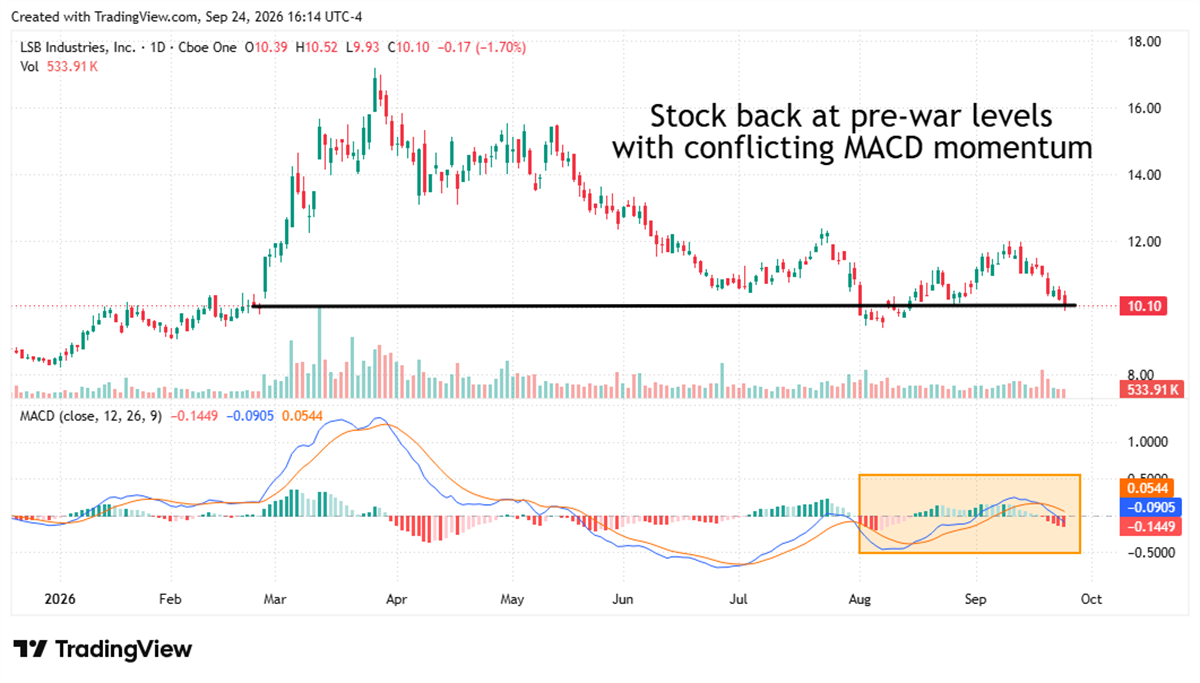
Unfortunately, the gold and copper sector has been weighing on LXU shares, and a fundamental catalyst is needed since the technical outlook isn’t optimistic. The Moving Average Convergence Divergence (MACD) recently performed a bearish cross, and the share price is back at the same level it was before the Iran war began. However, the decline has brought the stock back near $10, and the average price target is $14.67, implying upside of more than 45%.
The article "Fertilizer Prices Keep Climbing: 3 Stocks Still Trading at a Discount" first appeared on MarketBeat.