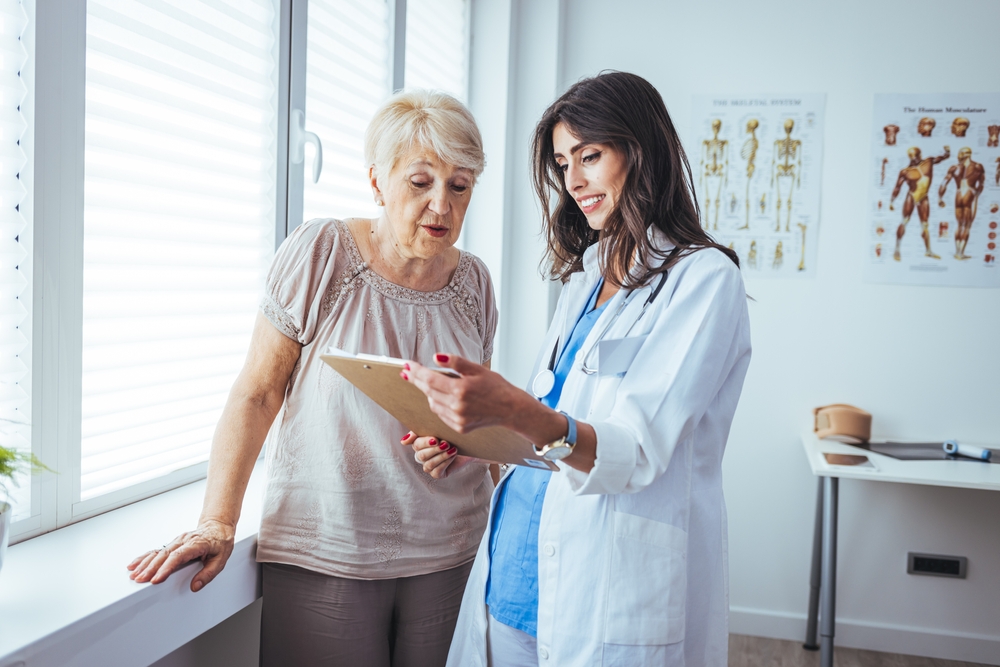
For many Americans, the years between retirement and Medicare eligibility at age 65 are financially challenging. Without employer-sponsored insurance, healthcare costs can skyrocket. Premiums, deductibles, and out-of-pocket expenses often consume a large portion of savings. This gap period leaves retirees vulnerable to unexpected medical bills. Planning ahead with effective strategies is essential to bridge the gap without draining resources.