Insurance is one of those expenses that can feel particularly painful when nothing goes wrong, but it’s often one of those things that can’t be avoided. Not only is some insurance required by law, but it can also provide peace of mind in the event of something catastrophic.
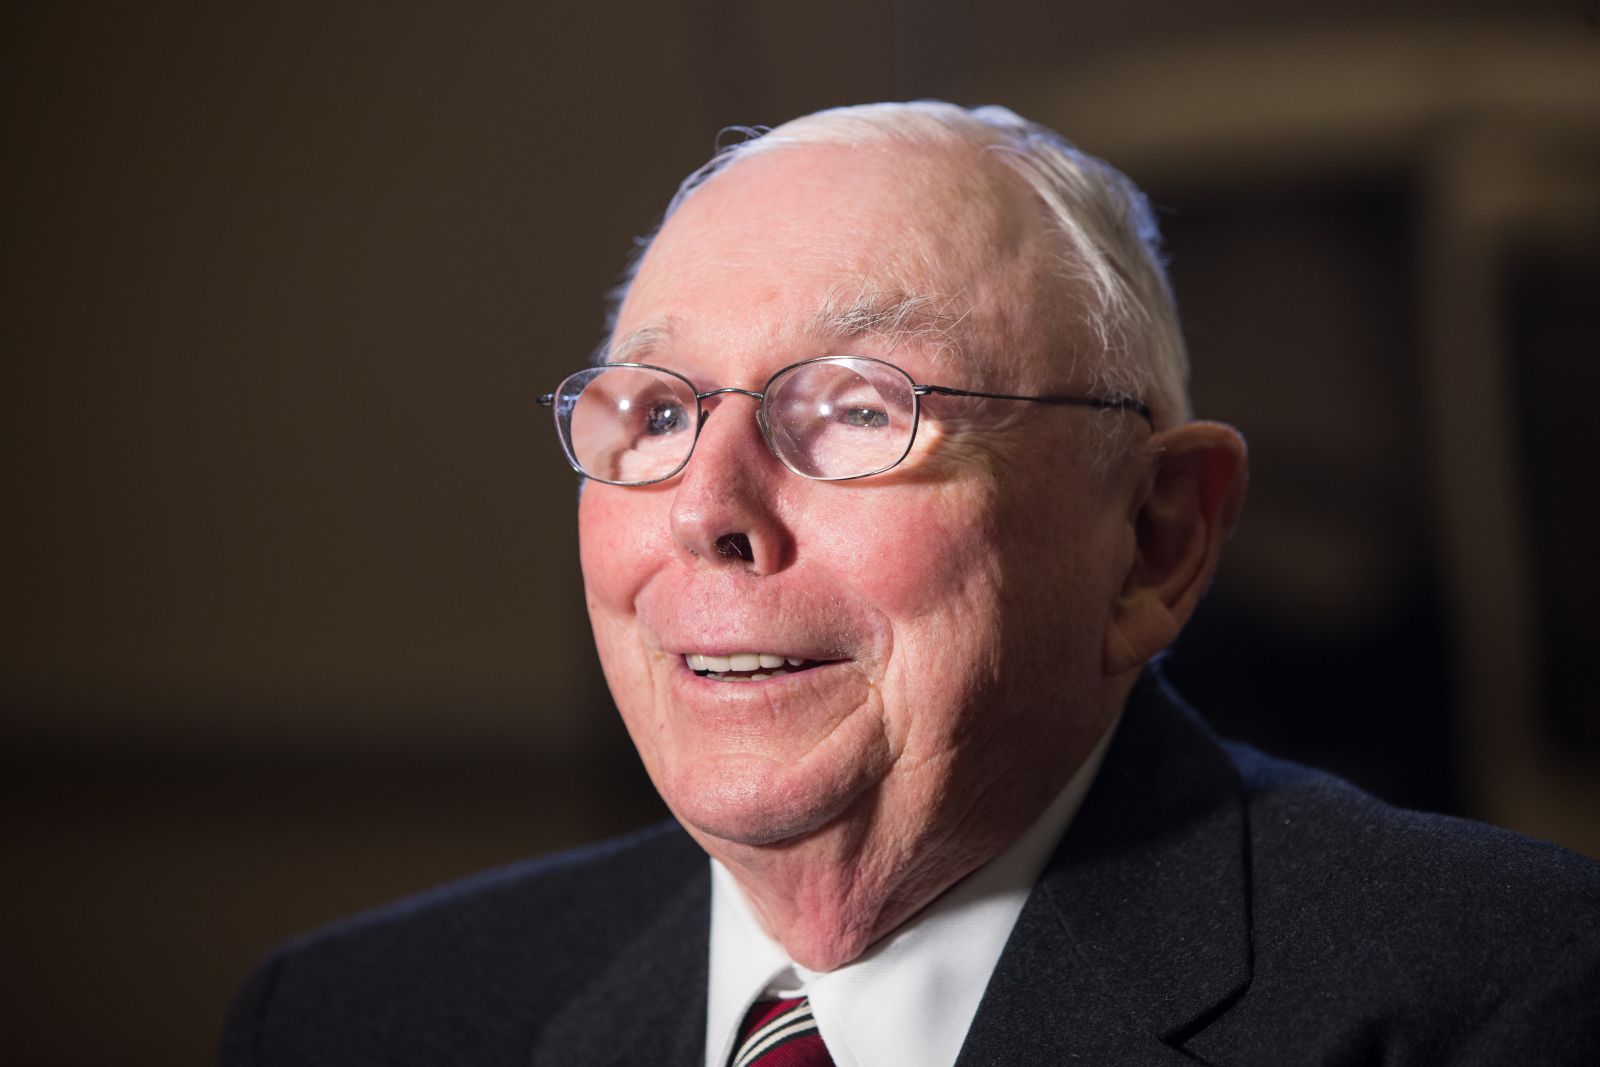
Billionaire Charlie Munger, however, reached a point where he decided some risks just weren’t worth insuring against. The longtime Berkshire Hathaway vice chairman had enough money to absorb certain losses himself, so why pay an insurance company to take a risk he could comfortably handle?
Munger explained his thinking at the Daily Journal Corporation’s annual shareholder meeting in February 2023, only a few months before his death. He was asked about large companies that were choosing to self-insure against certain risks.
“In my own life, I’m a big self-insured and so is Warren,” Munger said, referring to himself and Warren Buffett.
Sponsored Content: The Trillion-Dollar Energy Opportunity Investors May Be Missing
Munger explained that it made little sense for him to carry fire insurance on his house because he could afford to rebuild it if it burned down.
“You should insure against things you can’t afford to pay for yourself,” Munger said. “But if you can afford to take the bumps,” an unexpected expense might not be worth paying someone else to cover.
Then came a classic Munger moment.
“And all intelligent people do that way,” he said, before correcting himself.
“I don’t say all, but—maybe I should say, all intelligent people should do it my way.”
Munger then went into more detail about why he favored self-insurance.
“There should be way more self-insurance in life,” he said. “There’s a lot of waste. You’re paying when you buy insurance for the other fellows’ frauds—and there’s a lot of fraud in life.”
He also pointed to the costs that come with insurance beyond the actual risk itself, including claims, commissions, and the time involved in dealing with insurers.
“Think of what I’ve saved in my life,” Munger said.
The point was not that insurance had no value. It was that someone with enough money could decide that certain risks were cheaper to handle personally.
When A Billionaire Can Afford to Be His Own Insurer
Munger wasn’t arguing that insurance was pointless. He was making a distinction between a risk that could cause serious financial damage and one that could simply be absorbed.
Auto insurance, for example, is required by law in most states, although the exact requirements vary. Homeowners insurance is different. If a home is owned free and clear, homeowners insurance generally isn’t required by law, although a mortgage lender will typically require coverage.
For someone without substantial savings, going without homeowners insurance could be a massive gamble. A fire, storm, or other major loss could wipe out years of savings.
Munger was in a very different financial position.
If his house burned down, he could pay to rebuild it. The loss would be expensive and inconvenient, but it wouldn’t threaten his financial future.
That made self-insuring a reasonable choice for him.
Berkshire Made a Business Out of Taking on Risk
There’s an interesting twist to Munger’s argument. He was vice chairman of Berkshire Hathaway (BRK.A) (BRK.B), a company that had built a massive insurance operation, including GEICO.
Insurance became a major part of Berkshire’s business and generated capital the company could invest elsewhere. Berkshire collected premiums upfront and could invest that money before claims came due, creating what Warren Buffett has long referred to as “float.”
So Munger wasn’t against insurance. He understood why it could be a valuable business.
For an individual with enough money, taking on a manageable loss personally could make sense. For Berkshire, taking on other people’s risks in exchange for premiums could make sense.
The two decisions were based on the same calculation.
Munger also wasn’t going to change his personal view simply because Berkshire benefited from selling insurance.
“I’m not going to tell it differently than I think it really is just because it’s better for Berkshire,” he said at the meeting.
The business case and the personal financial decision weren’t necessarily the same thing.
The Same $100,000 Loss Can Mean Two Very Different Things
Munger’s insurance philosophy has a direct connection to investing.
Two people can make the exact same investment and face wholly different financial consequences.
Consider two investors who each put $100,000 into a highly volatile investment. It falls 50%, leaving each with $50,000.
One investor has several million dollars in other assets. The other has $150,000 in total savings.
The loss is identical.
The financial impact isn’t.
For the first investor, a $50,000 loss may be painful but manageable. For the second, it could affect the ability to pay bills, handle an emergency, or reach a major financial goal.
That’s why investment risk can’t be judged only by looking at the investment itself. The investor’s financial position matters, too.
Being Able to Take the Hit Changes the Calculation
An investor may be comfortable watching a portfolio fall 40% on paper. But if that decline forces a sale to cover an emergency or pay for something that can’t wait, the investor wasn’t really in a position to take that risk.
There’s a difference between being emotionally comfortable with a loss and being financially capable of absorbing it.
That’s essentially what Munger was saying about insurance.
Self-insurance only works when someone has enough money to cover the loss without putting their financial future in jeopardy.
The same principle applies to an investment portfolio.
Someone with substantial assets may be able to sit through a major market decline without selling at the worst possible time. Someone with little financial flexibility may not have that option.
Self-Insurance Isn’t the Same as Going Without Protection
Munger’s comment wasn’t a warning against insurance. It was a reminder that the value of insurance depends on the risk being covered and the resources of the person buying the policy.
For someone who can’t afford to replace a home, paying for homeowners insurance can be essential protection. For Munger, paying to insure a house against a loss he could easily cover himself wasn’t worth the expense.
That same thinking can help investors look at risk differently.
The question isn’t simply how much an investment could lose.
It’s whether the investor can afford to lose it.
Munger had enough wealth to absorb certain losses himself. Most people don’t have that luxury, which is why insurance and diversification can play such an important role in protecting what they’ve built.
The smartest investor isn’t necessarily the one willing to take the most risk.
It’s the one who understands which risks can be absorbed, which need protection, and which aren’t worth taking in the first place.