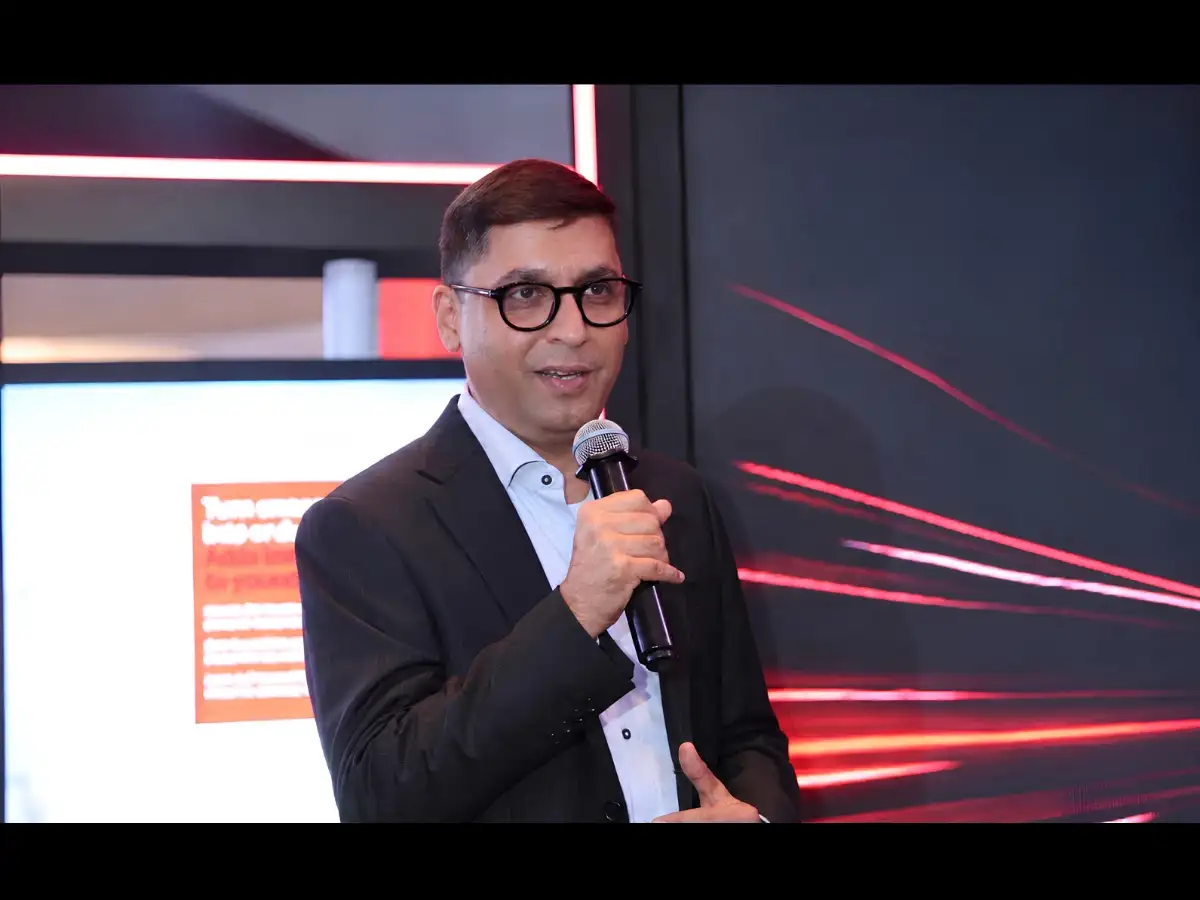
In an effort to meet the changing needs of the MSME (micro, small, and medium enterprise) ecosystem, DBS Bank India has introduced a new Collections Orchestration platform that helps merchants manage payments across multiple payment gateways through a single integration. The offering includes a unified dashboard, gateway-agnostic card tokenisation, and management tools to assist SMEs in managing their payments. In an interaction with The Economic Times Digital , Divyesh Dalal, Managing Director & Head, Global Transaction Services, Corporate Banking, Financial Institutions and SMEs, DBS Bank India, discusses why small and medium enterprises (SMEs) are central to the bank’s strategy, the role foreign banks can play in addressing the sector’s requirements, how ongoing trade realignments are creating opportunities for businesses to look beyond domestic markets, and more. Edited excerpts:
The Economic Times Digital (ET): How is DBS Bank India strengthening its proposition for SMEs, and what are some of the key needs of small businesses that are shaping this approach?
Divyesh Dalal (DD): The needs of SMEs today have evolved beyond basic funding requirements; hence, the scope of banks to play a more meaningful role in their growth journey is now greater than ever.
Today an SME owner values digital banking solutions that save time and effort, ecosystem partnerships, access to cross-border networks, and opportunities to be connected to larger value chains. With the formalisation and digitisation of the Indian economy, SMEs are eager to explore online channels and open networks to scale their reach, often requiring support to navigate these new digital corridors. DBS supports SMEs on their digitisation journeys through business banking solutions like DBS IDEAL, which provides real-time cash flow visibility, while integrations with ERP platforms like Tally streamline accounting and reconciliation.
DBS Bank India harnesses technology to solve real-world challenges that SMEs might face. A key offering is the cash-flow-based underwriting solution, which uses alternative, high-frequency, digital data, such as GST (goods and services tax) filings, transaction flows, and bureaus, to provide timely credit, including working capital, invoice finance, and term loans. This allows the bank to evaluate creditworthiness through business performance indicators rather than relying exclusively on conventional financial statements. This is particularly valuable for micro and small enterprises, where traditional financial documentation may not fully reflect business potential.
ET: What is driving DBS Bank’s momentum in the SME business, and how are the needs of SMEs evolving today?
DD: There has been strong and sustained momentum over the past three years for DBS Bank India. Our SME asset book has more than doubled between FY23 and FY26, with broad-based growth across the MSME segments.
DBS has been systematically expanding its SME business beyond metropolitan centres into high-growth SME clusters, where entrepreneurial and export-led activities continue to accelerate. Supported by our global network and local footprint spanning over 180 SME-focused locations, covering more than 70% of India’s addressable SME market, DBS is uniquely positioned to extend the benefits of its digital banking capabilities to enterprises across the country.
SMEs from non-metro markets now represent a significant and growing segment of our customer base, mirroring the continued momentum of manufacturing, trading, and entrepreneurial activity in India’s Tier II and Tier III cities. As these regional economic centres gain prominence, we expect their contributions to our franchise to increase further.
By integrating bank statements and GST information into our proprietary risk assessment models, we develop a comprehensive view of an enterprise’s financial health, enabling more informed and efficient credit underwriting. It is this strong risk culture that will continue to underpin the expansion of our SME asset portfolio while ensuring long-term value creation.
ET: Digitalisation is becoming increasingly important for small businesses. How is DBS Bank India helping SMEs access digital banking, loans, payments, collections, and transaction banking solutions more easily?
DD: We have adopted a “phygital” (physical + digital) model to strengthen our SME proposition, recognising that while digital tools drive efficiency and scale, long-term relationships require a blend of on-the-ground support and seamless digital integration.
Through DBS IDEAL, our integrated digital banking platform, and cash management solutions, such as DBS MAX, business owners can seamlessly manage their banking needs anytime, anywhere, reducing reliance on branch visits and enabling them to devote more time to scaling their businesses. The bank works closely with customers to help them fully leverage these digital capabilities.
The Online Account Opening System (OAOS) allows SMEs to seamlessly open and manage accounts remotely, reducing cumbersome processes and long turnaround times. The DBS IDEAL enterprise platform is at the heart of this strategy, providing a one-stop digital suite for payments & collections, GST compliance, reconciliation, paperless trade finance, and digital business loans.
ET: How are platforms like DBS MAX helping SMEs and merchants manage their day-to-day business and transaction needs?
DD: Digitalisation has become a necessity for small businesses, and DBS Bank India has been helping SMEs navigate this transition by reimagining banking, embedding financial services directly into the SME business ecosystem and replacing traditional, manual workflows with seamless, digital-first banking solutions.
DBS MAX equips businesses with the ability to address failed recurring payments, helping reduce revenue leakage and mitigate customer churn. By replacing fragmented processes with automated, real-time workflows, it enhances clearing efficiency and provides actionable insights into payment performance. For eligible transactions, real-time or near real-time settlement improves cash flow visibility and accelerates access to funds compared with traditional settlement cycles.
ET: What does Collections Orchestration bring to the DBS MAX platform, and how can it help businesses simplify the management of their payment collections ecosystem?
DD: As digital commerce scales and consumers increasingly use different payment modes, merchants prefer to work with multiple payment aggregators to optimise conversions. At the same time, the volume of online transactions has increased exponentially, and along with this, the possibility of failed payments and the complexity and costs of managing multiple vendors and integrations have risen. In line with this, DBS MAX has expanded its capabilities through its partnership with Juspay, strengthening merchants’ ability to orchestrate payments, improve transaction success rates, and gain end-to-end visibility across digital collections.
Through DBS MAX, merchants can accept real-time digital payments while leveraging the broader DBS ecosystem for virtual accounts, automated reconciliation, liquidity management, and treasury services. As online commerce continues to grow, these capabilities provide merchants with a more resilient payments infrastructure, helping them access stronger lifetime customer value through an efficient payment experience.
ET: With businesses managing multiple digital payment channels, what are some of the challenges around collections that merchants face today?
DD: Merchants today face a host of collection challenges due to the plethora of digital payment platforms, where managing diverse payment modes (cards, wallets, UPI, etc.) can lead to time-consuming and costly onboarding and reconciliation processes.
For subscription-based and recurring payment models, revenue leakage frequently arises from expired payment credentials, technical disruptions, or friction within authentication and collection journeys.
ET: How do you see the role of banks evolving in supporting SMEs as they become more digitally enabled and increasingly connected to domestic and global markets?
DD: As SMEs digitise and engage in broader domestic and global trade, foreign banks particularly have a crucial role to play, enabling the discovery of new customers and suppliers. Ongoing trade realignments have created opportunities to look beyond domestic markets, and enterprises today increasingly require regional network support, cross-border trade finance expertise, and FX management solutions.
DBS Bank India leverages the bank’s regional network across key Asian markets, including Singapore, Hong Kong, China, Indonesia, and Taiwan, and global expertise to act as a strategic partner for Indian SMEs aiming to expand beyond domestic markets. By combining capital and market intelligence with entrenched local and regional connectivity, the bank helps these businesses navigate international corridors with confidence.
ET: Looking ahead, what are the key opportunities you see in India’s SME and merchant ecosystem, and where will DBS Bank India continue to focus its efforts?
DD: India’s vision of Viksit Bharat 2047 aims to transform the country into a developed, high-income, globally competitive economy. SMEs are central to this ambition because they drive employment, exports, innovation, and manufacturing growth. DBS Bank India is positioned to add real value to this growth trajectory, helping SMEs with intelligent orchestration, ecosystem embedding, and cross-border enablement. The bridge between India’s manufacturing hubs and the broader Asian market remains a significant, high-growth opportunity.