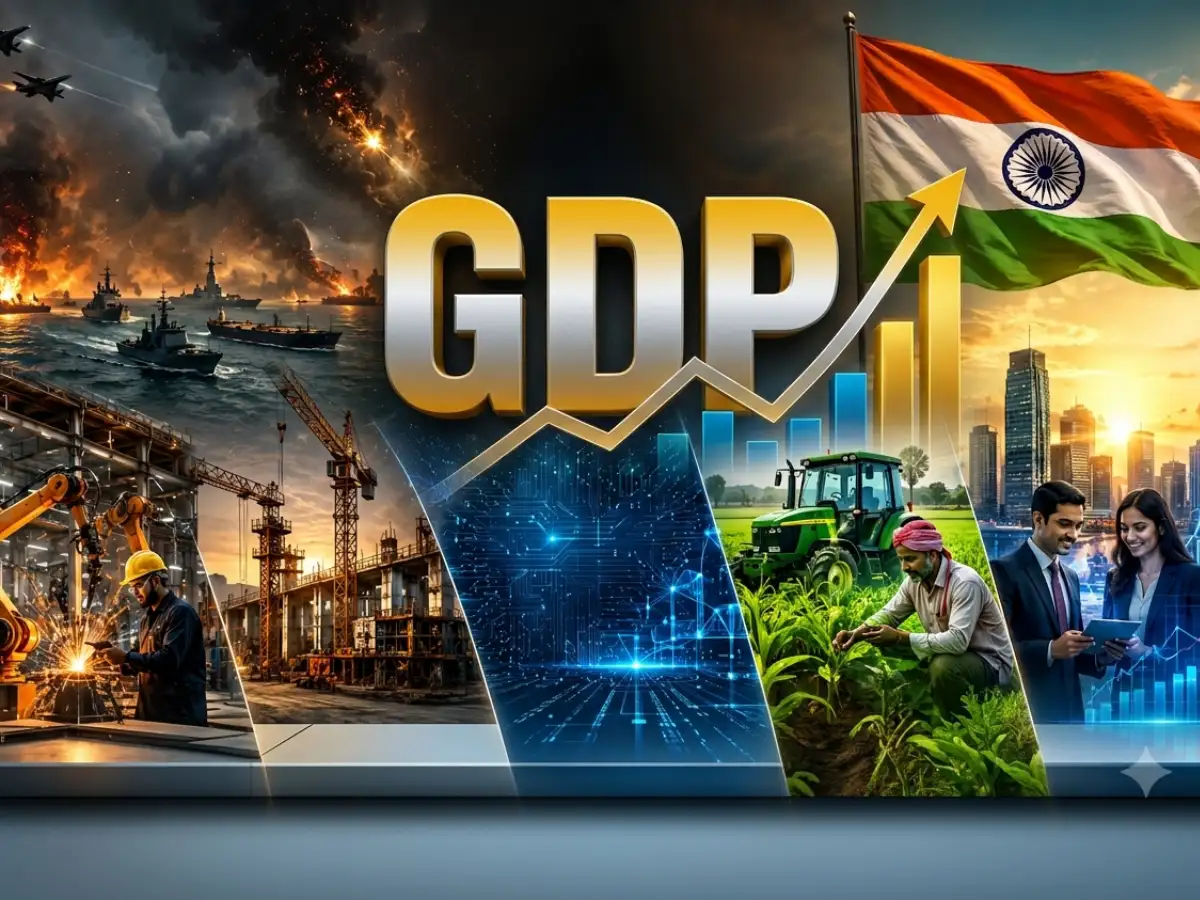
India's 7.8% GDP growth in the April-June quarter of FY27 decisively beat expectations despite an oil shock, geopolitical tensions, supply-chain disruptions and uncertainty over global trade. The figure was well above the 7% forecast of the RBI and the 7.1% Reuters poll median, defying predictions of a meaningful slowdown.
US President Donald Trump had last year called India a dead economy though a few months ago he said Indian economy is doing very well. Politics aside, many experts had expected the economy to bend to various external pressures such as the Iran war, oil prices and trade and supply chain troubles.
ALSO READ | India’s growth beat suggests economy on cusp of investment boom
Prime Minister Narendra Modi was quick to respond. In a post on X, he called the performance a “herculean feat” and said: “Doomsayers were doomed and India bloomed…yet again!” He pointed to India's ability to withstand oil-price shocks, supply-chain disruptions and global uncertainty. Beyond the political messaging, the numbers reveal something important. The surprise was not merely the headline growth rate but its breadth. Consumption remained resilient, investment accelerated, manufacturing strengthened, services continued to expand rapidly and exports proved far more resilient than expected. Just ten years ago, these kinds of external pressures would have depressed GDP growth but Indian economy has grown more resilient now.