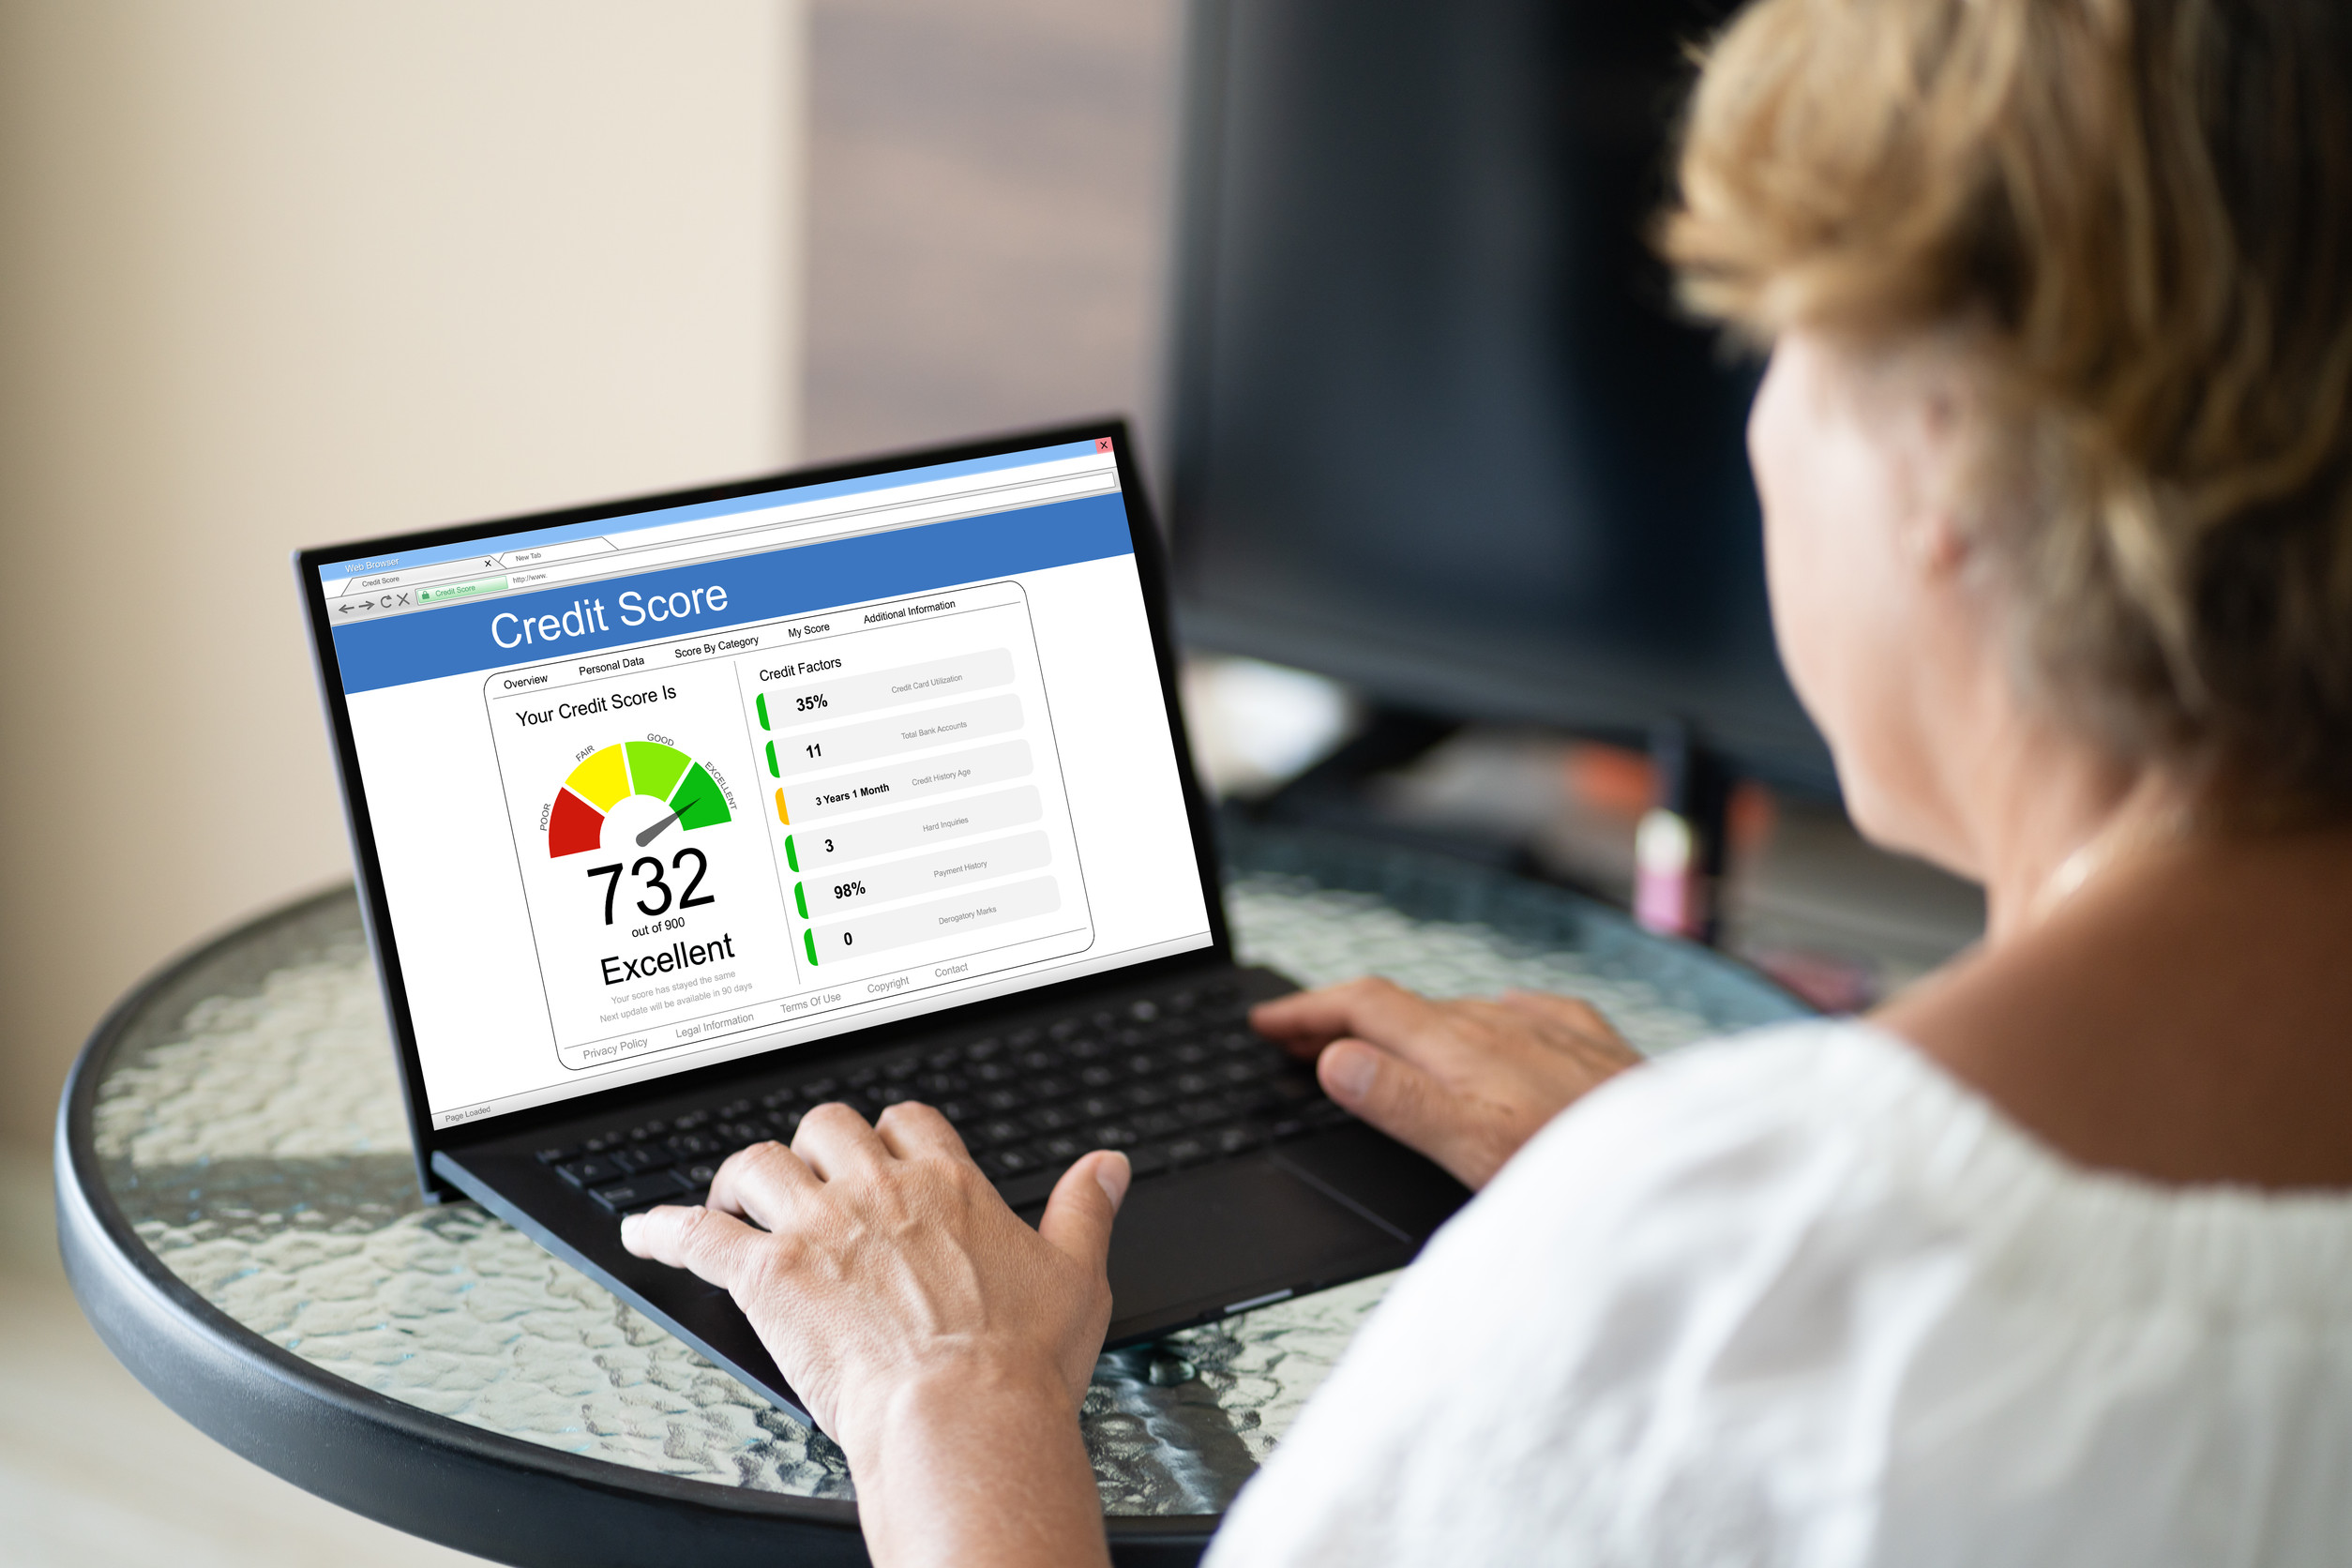
You might think that once you retire, your credit score will stay steady—or even improve—since you’re no longer taking on new debt. But many retirees are surprised to see their scores quietly decline, even when they pay every bill on time. That’s because credit scoring models reward activity, diversity, and usage—not just responsibility. Retirement often changes how you use credit, and those shifts can lower your score unintentionally. Understanding the hidden factors helps protect your rating long after the paychecks stop.