
Dell Technologies (DELL) is moving deeper into the artificial intelligence (AI) infrastructure buildout, with exposure across servers, networking, storage, and commercial computing. The company strengthened that position in the second quarter of fiscal 2027, reporting $60.9 billion in AI server orders and a $95 billion AI backlog while also raising its full-year fiscal 2027 guidance.
The numbers have done little to cool Wall Street’s enthusiasm. Evercore ISI analyst Amit Daryanani recently raised his price target to $650 from $575 and reiterated DELL stock as a top pick. His bullish view reflects stronger neocloud deployments, expanding enterprise AI adoption, potential share and margin gains, and disciplined capital allocation.
Evercore also sees room above the fiscal 2027 Wall Street EPS estimate of about $25.88, with its bull case exceeding $30 per share. Daryanani further believes that a “combination of higher AI attach” and continued AI-server expansion could push Dell’s earnings power well above consensus. In fact, Evercore sees additional leverage building into fiscal 2028 as well, expecting storage margin expansion to above 30% EBIT margins, while operating expense leverage and incremental capital returns could help take fiscal 2028 EPS above $40 versus expectations of roughly $31 per share.
Let's take a closer look at how much further DELL stock could realistically run from here.
About Dell Stock
Commanding a market capitalization of nearly $368 billion, Dell helps businesses upgrade infrastructure, manage data, strengthen digital operations, and support AI workloads. Based in Round Rock, Texas, the company also offers financing, subscription, leasing, and technology consumption solutions, allowing customers to access technology in several ways as their infrastructure requirements evolve.
DELL stock’s market performance has been notable. The stock has climbed approximately 327% over the past 52 weeks and has surged 324% year-to-date (YTD). The rally has remained strong across shorter periods as well, with shares gaining 35% over the past three months and 9% over the past month, largely reflecting the solid Q2 performance.
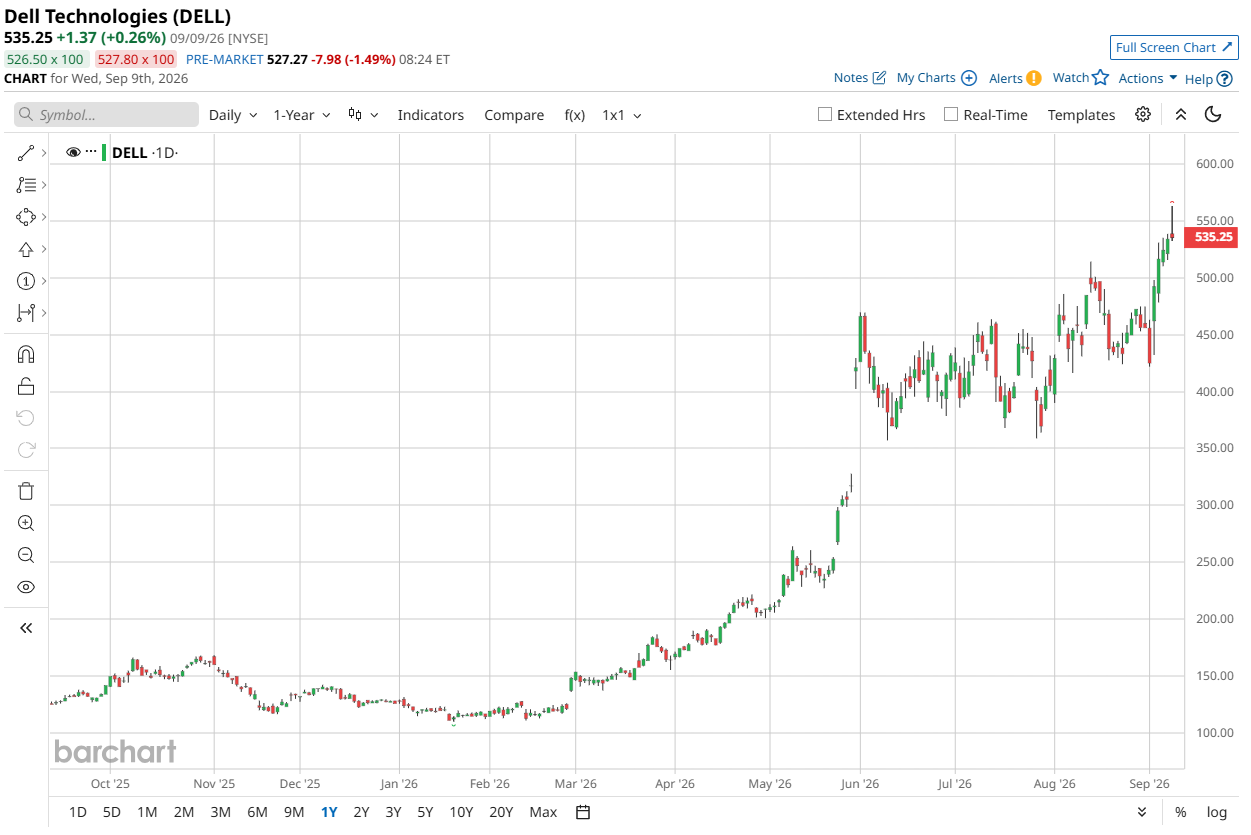
On the valuation front, DELL stock trades at 22.5 times forward earnings and 3.2 times sales. Shareholders are also receiving direct returns from the company. Dell currently pays an annual dividend of $2.52 per share, which translates into a yield of 0.44%. The company is scheduled to pay its next quarterly cash dividend of $0.63 per common share on Oct. 30 to shareholders of record as of Oct. 20.
Dell Reports Q2 Earnings
Dell reported its Q2 fiscal 2027 earnings on Sept. 1, and the release gave investors a fresh look at the strength of its business. The market reacted sharply, sending DELL stock almost 16% higher in the following trading session. Total revenue grew 58% year-over-year (YOY) to $46.97 billion, exceeding the $45.06 billion analyst estimate, while adjusted EPS rose 203% YOY to $7.04, topping Wall Street’s forecast of $4.92.
The strongest contribution came from the Infrastructure Solutions Group (ISG). Revenue from the segment jumped 89% YOY to $31.8 billion. AI-optimized servers were the standout, generating $16.4 billion in revenue. More importantly, Dell added $60.9 billion in new orders and posted a record $95 billion backlog.
Growth was not confined to the AI-server business. Traditional servers and networking increased 122% YOY, while storage revenue advanced 26% from the prior-year period. Profitability also improved sharply, with ISG operating income more than tripling and rising 225% YOY.
The Client Solutions Group (CSG) delivered a more measured performance but still recorded healthy growth. Revenue increased 20% YOY to $15 billion, helped by a 22% YOY increase in commercial client revenue. Consumer demand remained considerably slower, with that portion of the business increasing just 7% during the period.
Dell’s cash flow performance provided another strong takeaway from the quarter. Adjusted free cash flow climbed 224% YOY to $8.1 billion, giving the company substantial financial capacity.
Looking ahead, management has subsequently raised its full-year fiscal 2027 outlook, setting its revenue forecast at $192 billion, implying 169% YOY growth. Dell also expects AI-optimized server revenue of $74 billion, up 200%, and non-GAAP EPS of $25.50. Meanwhile, management guided Q3 revenue to $49 billion and non-GAAP EPS of $6.50 per share.
Analysts are also expecting exceptional earnings growth, forecasting Q3 EPS to rise 173% YOY to $6.42. For fiscal 2027, earnings are expected to climb 172% YOY to $25.14 per share, followed by another 13% YOY increase to $28.38 per share in fiscal 2028.
What Do Analysts Expect for Dell Stock?
Evercore was not the only analyst firm to be optimistic about DELL stock following Dell’s most recent quarterly results. Susquehanna analyst Mehdi Hosseini reiterated a “Buy” rating on the stock while keeping his $700 price target unchanged.
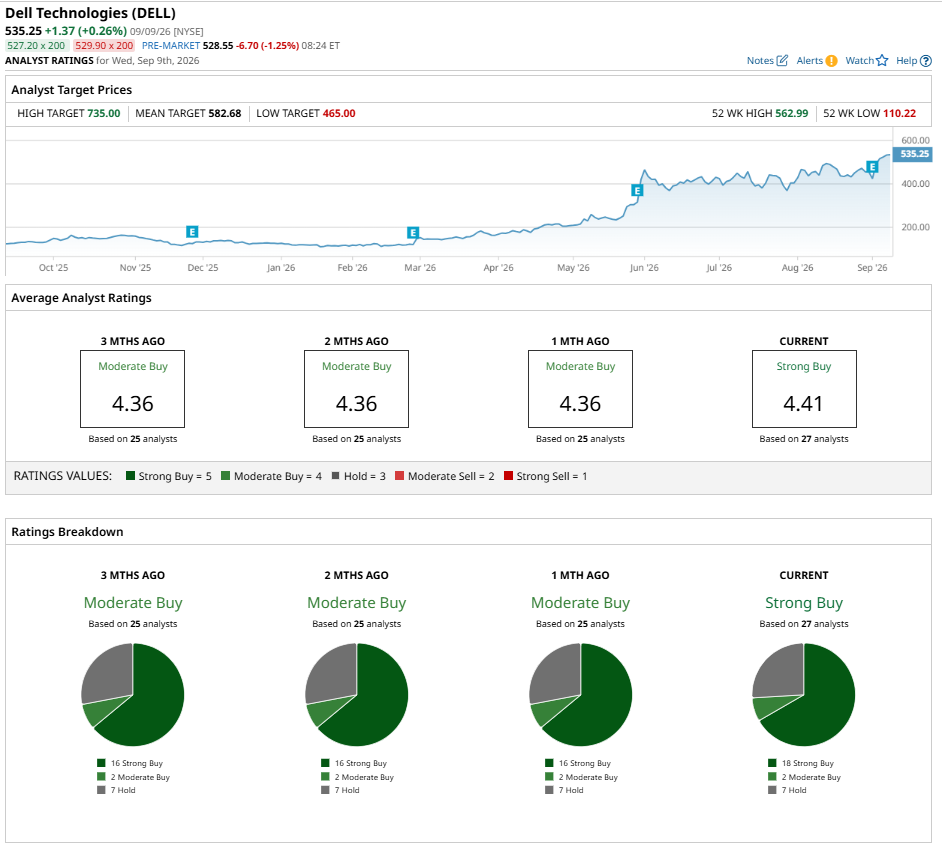
Broader Wall Street sentiment remains firmly bullish, assigning DELL stock a consensus “Moderate Buy” rating. Among 28 analysts with coverage, 18 have a “Strong Buy” rating, three have a “Moderate Buy,” and seven analysts have a “Hold” rating.
The broader target range reflects that optimism. The average price target of $584.88 represents potential upside of 9% from current levels, while the Street-high target of $735 implies a possible gain of almost 38% from here.