The much-awaited initial public offering (IPO) of the National Stock Exchange of India opened for subscription on September 17, allowing public-market investors to own a stake in the country’s largest stock exchange.
The Rs 22,561.57-crore IPO is entirely an offer for sale (OFS) of 12.64 crore shares by 23 existing shareholders. The issue has been priced at Rs 1,700-1,785 a share, with a lot size of eight shares. Thus, at the upper end of the price band, retail investors will need Rs 14,280 to apply for one lot. The maximum application of 14 lots, or 112 shares, will require Rs 1,99,920. The issue closes on September 21, while the shares are scheduled to list on September 24, subject to the final listing schedule.
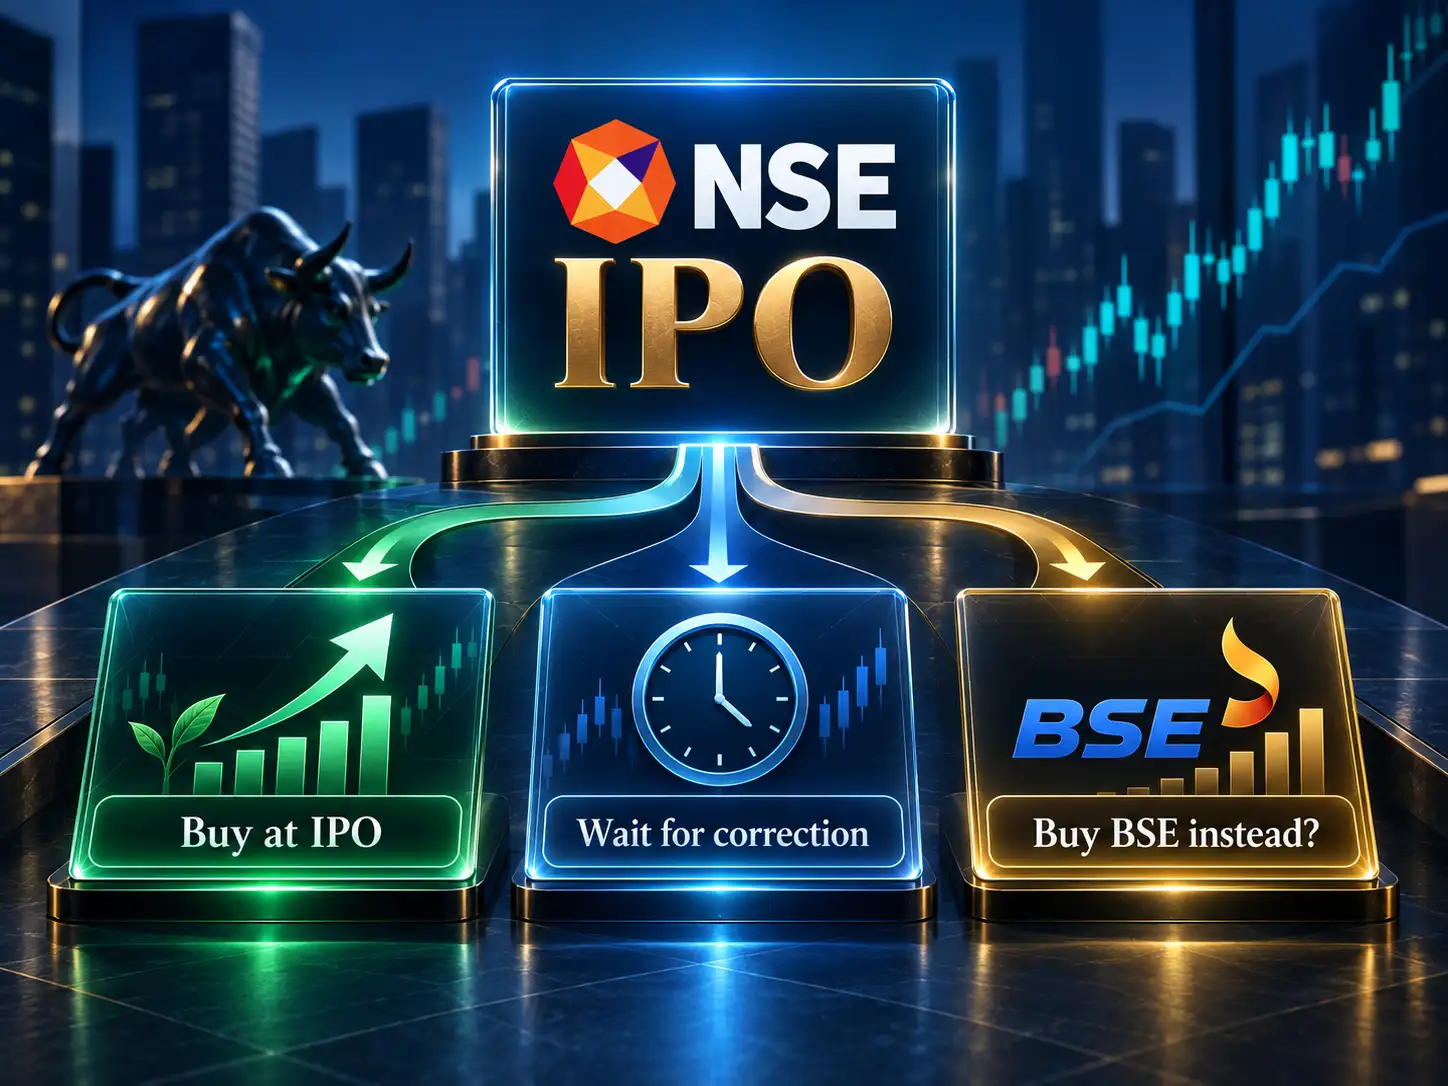
For investors, however, the bigger question is whether NSE IPO valuation leaves enough room for further gains or whether it makes more sense to wait for a post-listing correction. With BSE the only listed comparable, its valuation provides a reference point for investors assessing NSE.
Read more: NSE IPO Tracker: Catch all the highlights here
NSE’s market dominance
Analysts said NSE’s investment case rests largely on its dominant position across India’s capital markets.
The exchange operates across trading, clearing, listing, indices and data services, covering the cash market, equity futures and options, currency and commodity derivatives, mutual funds, wholesale debt and interest-rate futures.
NSE has remained India’s largest exchange by cash-market and equity-derivatives turnover since FY01.
As of June 30, 2026, NSE had 132.37 million unique registered investors, 1,328 trading members and 3,005 listed entities. These companies had a combined market capitalisation of Rs 474.08 trillion.
That scale and market share sit at the centre of the valuation debate, particularly when NSE is compared with BSE.
NSE vs BSE: Financials and valuations
Ravi Singh, chief research officer at MasterTrust, said NSE has a stronger financial profile than BSE.
NSE reported FY26 revenue of Rs 16,601 crore and profit after tax (PAT) of Rs 10,302 crore, compared with BSE’s revenue of Rs 5,124 crore and PAT of Rs 2,487 crore.
Both exchanges reported EBITDA margins of around 68%. NSE’s PAT margin stood at 62.1%. BSE, however, reported higher returns, with ROE of 46% and ROCE of 60%, compared with 33% and 42.8%, respectively, for NSE.
On valuation, Singh said NSE’s EV/EBITDA multiple of 35.1 times was broadly comparable with BSE’s 24.9 times and 36.6 times, while NSE’s P/E of 42.9 times was below BSE’s 53.3 times.
“Subscribing for this IPO depends on an investor's objective,” Singh said.
Since the IPO is entirely an OFS, NSE itself will not receive any fresh capital from the issue.
At Rs 1,785 a share and with the latest GMP at around 9.4%, Singh said NSE was valued at 42.9 times earnings, below BSE’s 53.3 times, while offering higher revenue and PAT with similar EBITDA margins.
“Investors looking for listing gains may consider applying at the IPO price,” he said. “However, for long-term investors, NSE’s strong financials and growth potential may support participation, with scope to add on dips after listing.”
ALSO READ: NSE IPO: Every Rs 10 move in shares could swing Radhakishan Damani’s wealth by nearly Rs 40 crore
Valuation remains the key concern
The valuation at which investors enter remains a key point of debate.
Rahul Sharma, head of research at Equity99, said NSE would be valued at around 42.8 times earnings at the upper end of the price band. He considers this expensive, particularly after the company reported a decline in PAT in FY26.
At the same time, Sharma acknowledged NSE’s strong market position, with a 93% share of the cash-equity segment and nearly 100% share of the F&O segment.
“This IPO appears quite expensive at this valuation considering company reported degrowth in PAT in FY26,” Sharma said. “However, its fundamentals cannot be ignored with 93% share in cash equity segment and almost 100% share in F&O segment.”
He said the stock could see minor gains on listing but did not recommend long-term investment at current levels.
“Long-term investors can add this counter on dips,” he said.
Sharma also said BSE appeared expensive at current levels and did not consider it a good long-term investment.
NSE valuation in context of BSE
Choice Institutional Equities took a more constructive view of NSE’s valuation relative to BSE.
According to the brokerage, NSE’s IPO is priced at 47.3 times trailing earnings, while BSE trades at 48.9 times. Choice noted that BSE is less than a third of NSE’s size and argued that NSE’s valuation needs to be assessed against its scale and market position.
“The NSE IPO is priced at 47.3x TTM earnings. BSE, the only listed comparable, trades higher at 48.9x — on a business less than a third of NSE’s size, and on profits helped by the very options volumes NSE has lost,” Choice said.
“Buyers are paying full price for the larger and stronger of the two, not a premium over it.”
The brokerage also highlighted NSE’s vertically integrated business model, spanning the exchange, clearing operations, Nifty indices and data services.
According to Choice, the model allows NSE to monetise a single trade across multiple services, while new products can be added at relatively low incremental cost.
More than 90% of cash-market turnover and almost all equity-futures activity has gone through NSE every year since FY24, the brokerage said, adding that neither share has faced a serious challenge.
Choice also pointed to margins of around 76% and a debt-free balance sheet as structural features of the business.
Options volumes remain a concern
Choice, however, flagged index options as a key risk for NSE.
The brokerage said NSE has lost share in the segment since SEBI allowed each exchange only one weekly expiry day. It also expects the higher transaction tax introduced from April 2026 to put further pressure on volumes.
According to Choice, the development is significant because index options have been the fastest-growing part of NSE’s business.
The brokerage nevertheless said the broader franchise remains intact, pointing to the return of revenue and profit growth in Q1FY27. It also noted that FY26 profit was affected by a settlement charge that has since been paid.
Despite the concerns around options, Choice recommended subscribing to the IPO, arguing that there is no other way to own Indian market infrastructure at NSE’s scale and that first-time listings rarely come cheap.
This article has been written by Kumar Gaurav, who is not a SEBI-registered Research Analyst or an Investment Adviser. Gaurav and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment.