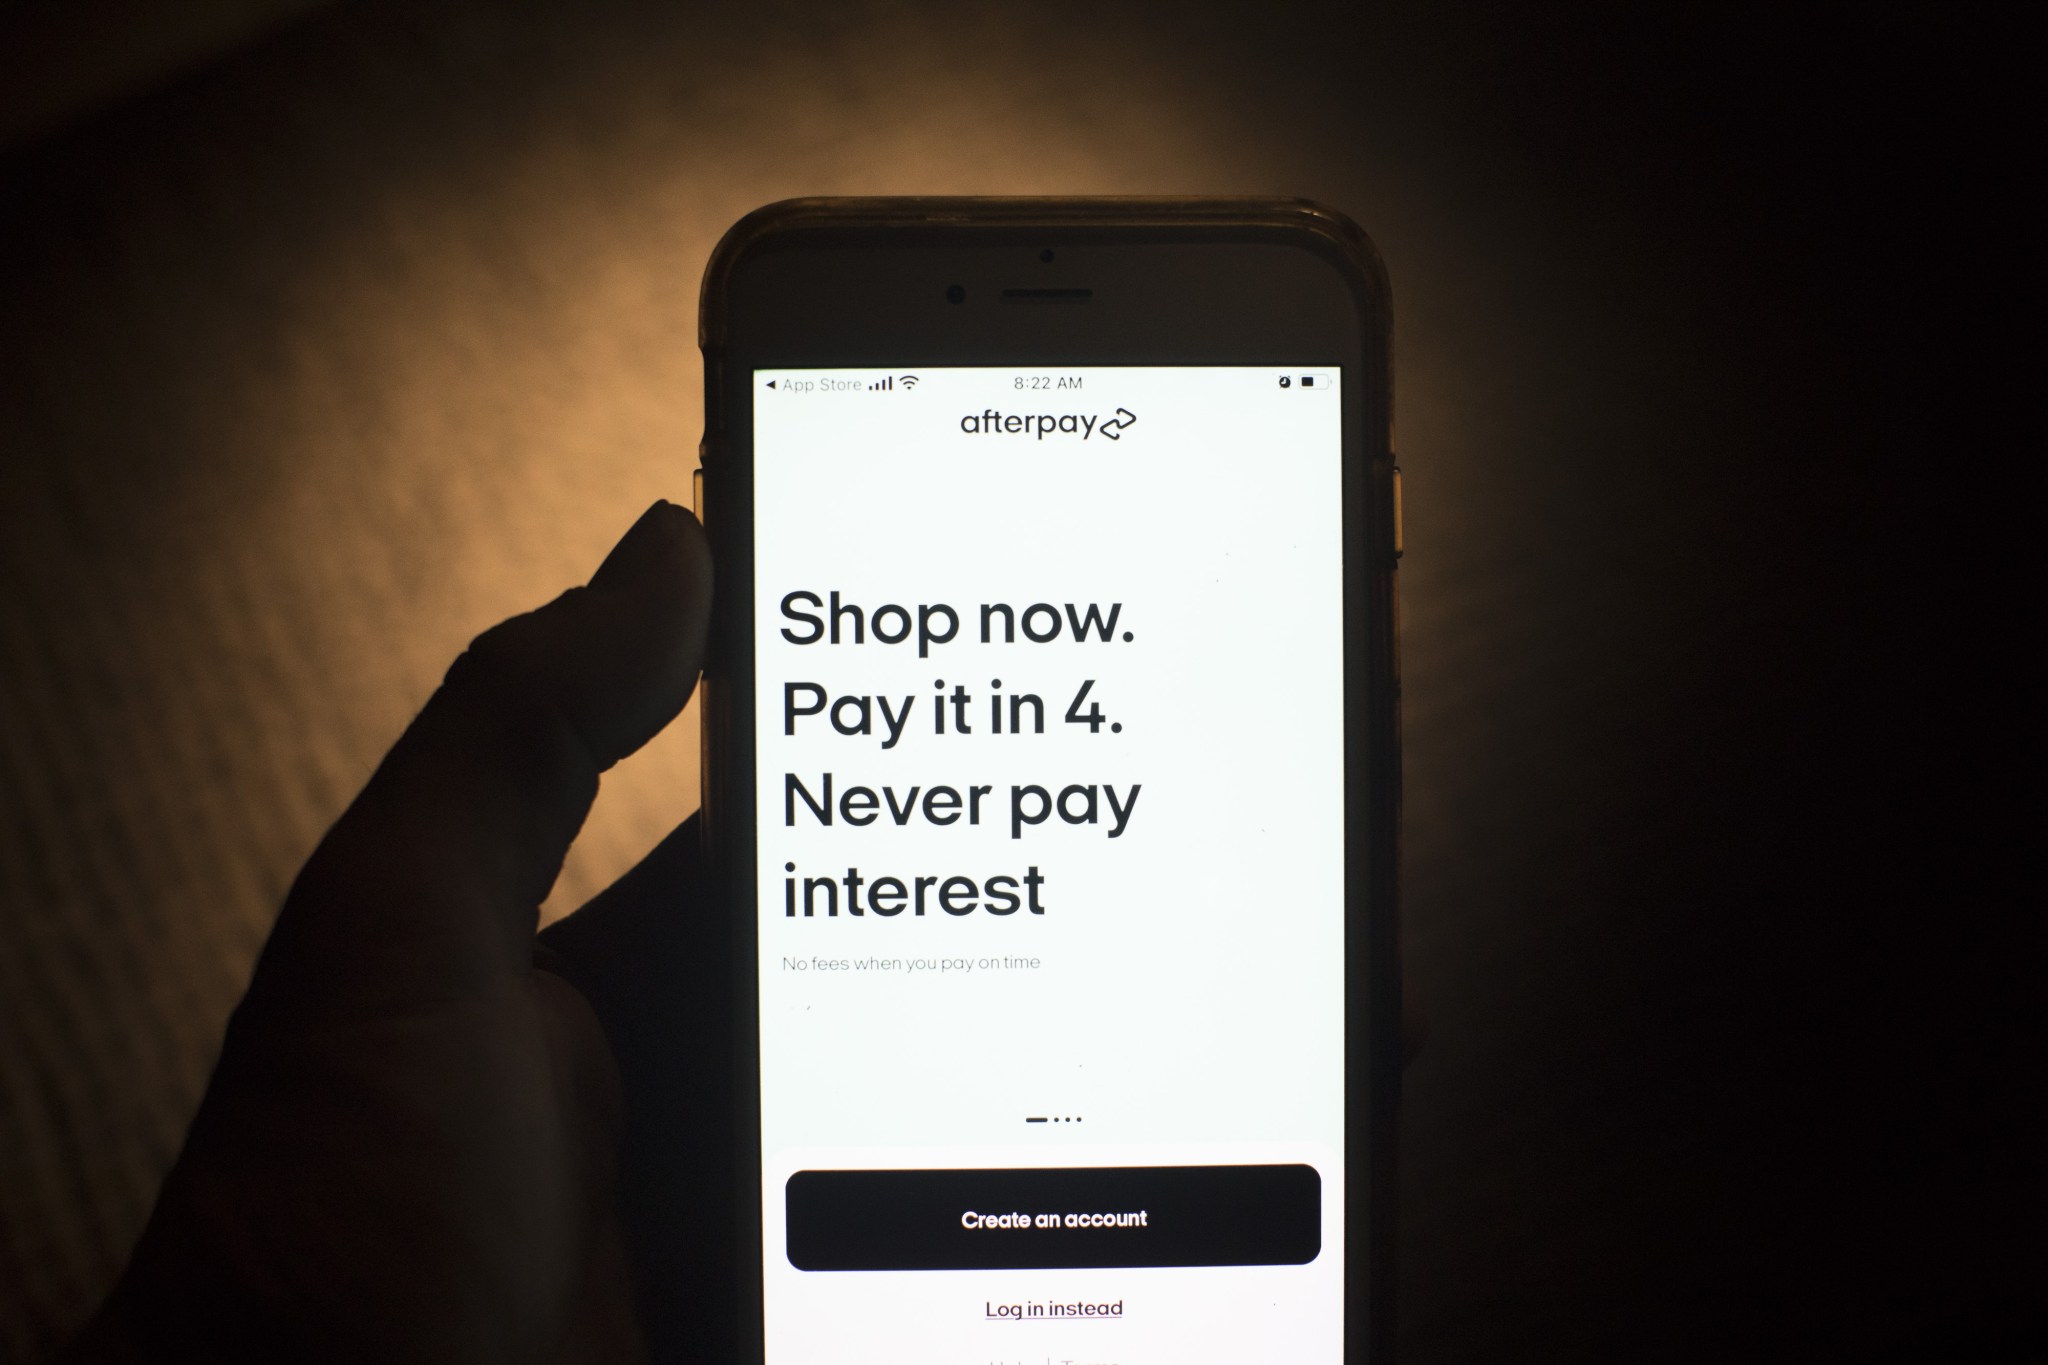
When “buy now, pay later” financing first gained traction, it was largely a way to finance discretionary purchases. Today, BNPL is being extended to rent.
When installment financing migrates from discretionary purchases to basic housing, it makes a mathematical reality visible: the middle-class margin has collapsed. Yet, when the Federal Reserve recently raised interest rates, lifting the federal funds target range by 25 basis points to 3.75% to 4%, with the 10-year Treasury yield topping 5%, policymakers painted a very different picture. Citing resilient domestic spending, strong productivity growth, and robust capital investment, the Fed described economic activity as expanding at a solid pace.