
Wall Street just gave SpaceX (SPCX) another vote of confidence, but the biggest part of the bull case has little to do with rockets. This time, TD Cowen initiated coverage of SPCX stock with a “Buy” rating and a $200 price target, putting the firm’s focus squarely on the company’s rapidly expanding artificial intelligence (AI) business.
This gives a huge boost to SpaceX because it is increasingly becoming more than a launch company. TD Cowen believes leasing AI computing capacity could eventually become one of its biggest revenue engines, adding another layer to the investment story.
The call comes as SpaceX stock remains volatile in its first year as a public company. Shares have been roughly flat in 2026 after an early surge and subsequent pullback. The latest data shows that SPCX stock is 30% below its initial public offering (IPO) peak.
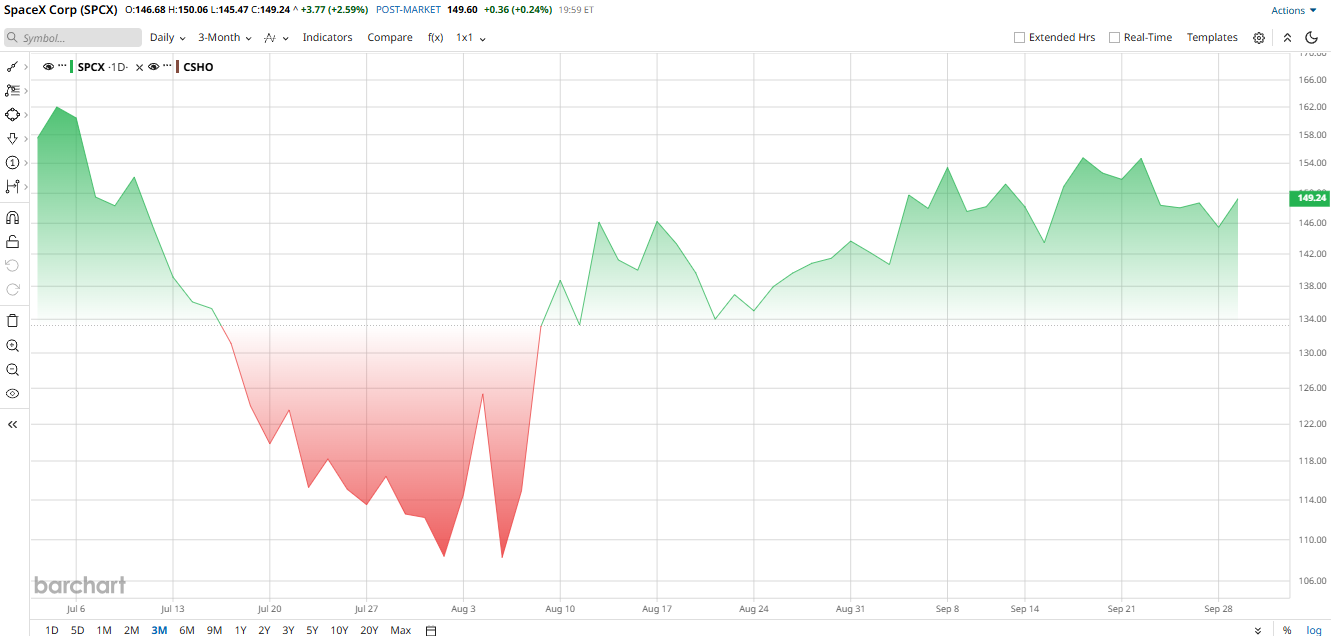
TD Cowen Sees an AI Business Hiding Inside SpaceX
So, TD Cowen’s take is that investors may need to think of SpaceX as an AI infrastructure company as well as a space business. Analyst John Blackledge projects $14.4 billion of AI revenue in 2026, or about 35% of total sales. By 2027, he expects AI revenue to reach $66 billion, which would make up more than half of the company’s business.
SpaceX is building massive ground-based computing capacity and selling access to customers that need additional AI infrastructure. Anthropic, Alphabet's (GOOGL) Google, and Reflection AI are among the publicly identified customers, while the company has also signed multiple cloud services agreements.
The opportunity is expanding quickly. SpaceX expects terrestrial computing capacity to increase from about 2.1 gigawatts in 2026 to 6 GW in 2027. TD Cowen also sees that figure reaching 22 GW by 2031.
That changes what the $200 target represents. The thesis is not simply about more launches or Starlink subscribers. It assumes SpaceX can turn its computing infrastructure into a large recurring-revenue business while continuing to scale its traditional operations.
The Latest Quarter Showed Why the Story Is Changing
SpaceX’s second-quarter results provided plenty of evidence behind that broader thesis.
Revenue almost doubled year-over-year (YOY) to $7.8 billion, exceeding projections. Similarly, net loss fell to $541 million from about $1 billion a year ago as adjusted EBITDA rose 191% to $3.5 billion. The company also had $14.1 billion in contracted sales of cloud services agreements.
Connectivity was the biggest revenue category with $4.3 billion, up 66% YOY. Meanwhile, the AI segment contributed $2.6 billion in revenue, which was up 247% YOY, while the Space segment made a $962 million contribution to the top line, up 29% YOY.
The numbers indicate that SpaceX is no longer growing from one business. Space is still a big opportunity to pursue in the long run, while AI is growing, as is the company's Starlink service.
Starship Adds Another Catalyst
SpaceX also reached an important milestone on Sept. 28, when Starship reached orbit for the first time and deployed 26 Starlink V3 satellites. The mission ended earlier than planned after an engine issue, but Reuters reports that the vehicle completed two orbits before returning to Earth.
For SpaceX, the achievement could matter beyond launch revenue. A more capable and reusable Starship could eventually help lower the cost of deploying satellites and potentially support future space-based computing infrastructure.
That gives investors another potential catalyst alongside the company’s expanding AI operations.
What Do Analysts Think of SPCX Stock?
Analysts are becoming increasingly bullish on SPCX stock as the company achieves milestones. Morgan Stanley analyst Adam Jonas has a $300 price target and views SpaceX as having opportunities across both space and AI infrastructure. Similarly, Bank of America analyst Ronald Epstein has a “Buy” rating with a $235 target, while RBC Capital analyst Ken Herbert has a price target of $225 following the Starship milestone.
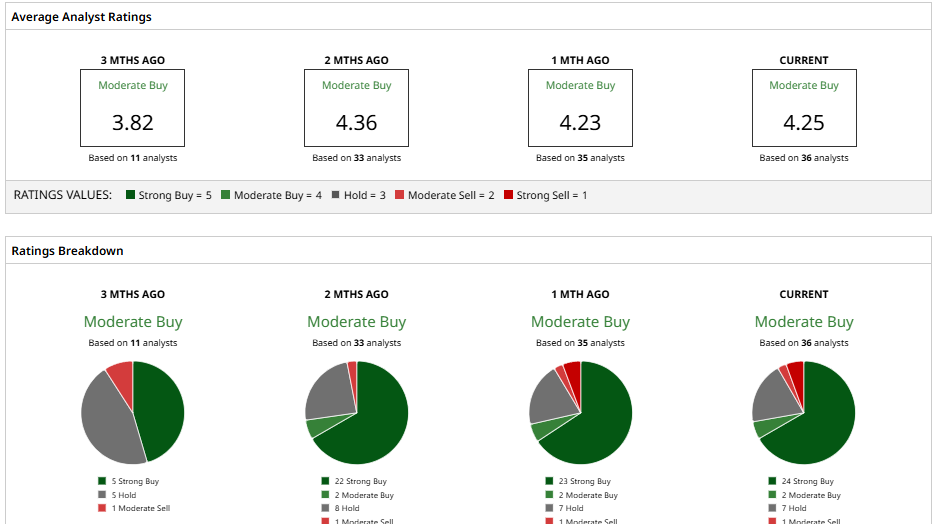
Overall, SpaceX stock has a consensus “Moderate Buy” rating on Wall Street. The average price target of $220.31 implies potential upside of roughly 40% from current levels, highlighting how much attention Wall Street is placing on SpaceX’s expanding AI and space opportunities.