
The software industry is no longer unified. For years, buying the iShares Expanded Tech-Software Sector ETF (IGV) provided clean, broad-based exposure to predictable software-as-a-service (SaaS) recurring revenue models. Currently, however, software stocks are a dividend bunch.
At the macro level, the industry is divided into two distinct camps: infrastructure backends enabling artificial intelligence workflows, and legacy application software facing structural pricing friction. Companies that own foundational enterprise databases, multi-cloud infrastructure, and specialized data pipelines are expanding their market share.
Conversely, traditional per-seat SaaS providers are discovering that AI agents, which are supposed to make workforce teams vastly more efficient, can inadvertently shrink the number of paid user seats enterprise clients require.
Here’s a list of several of the biggest holdings in IGV, the most prominent ETF devoted to providing access to stocks in the software industry. It is concentrated at the top, but there’s a wide range of companies throughout.
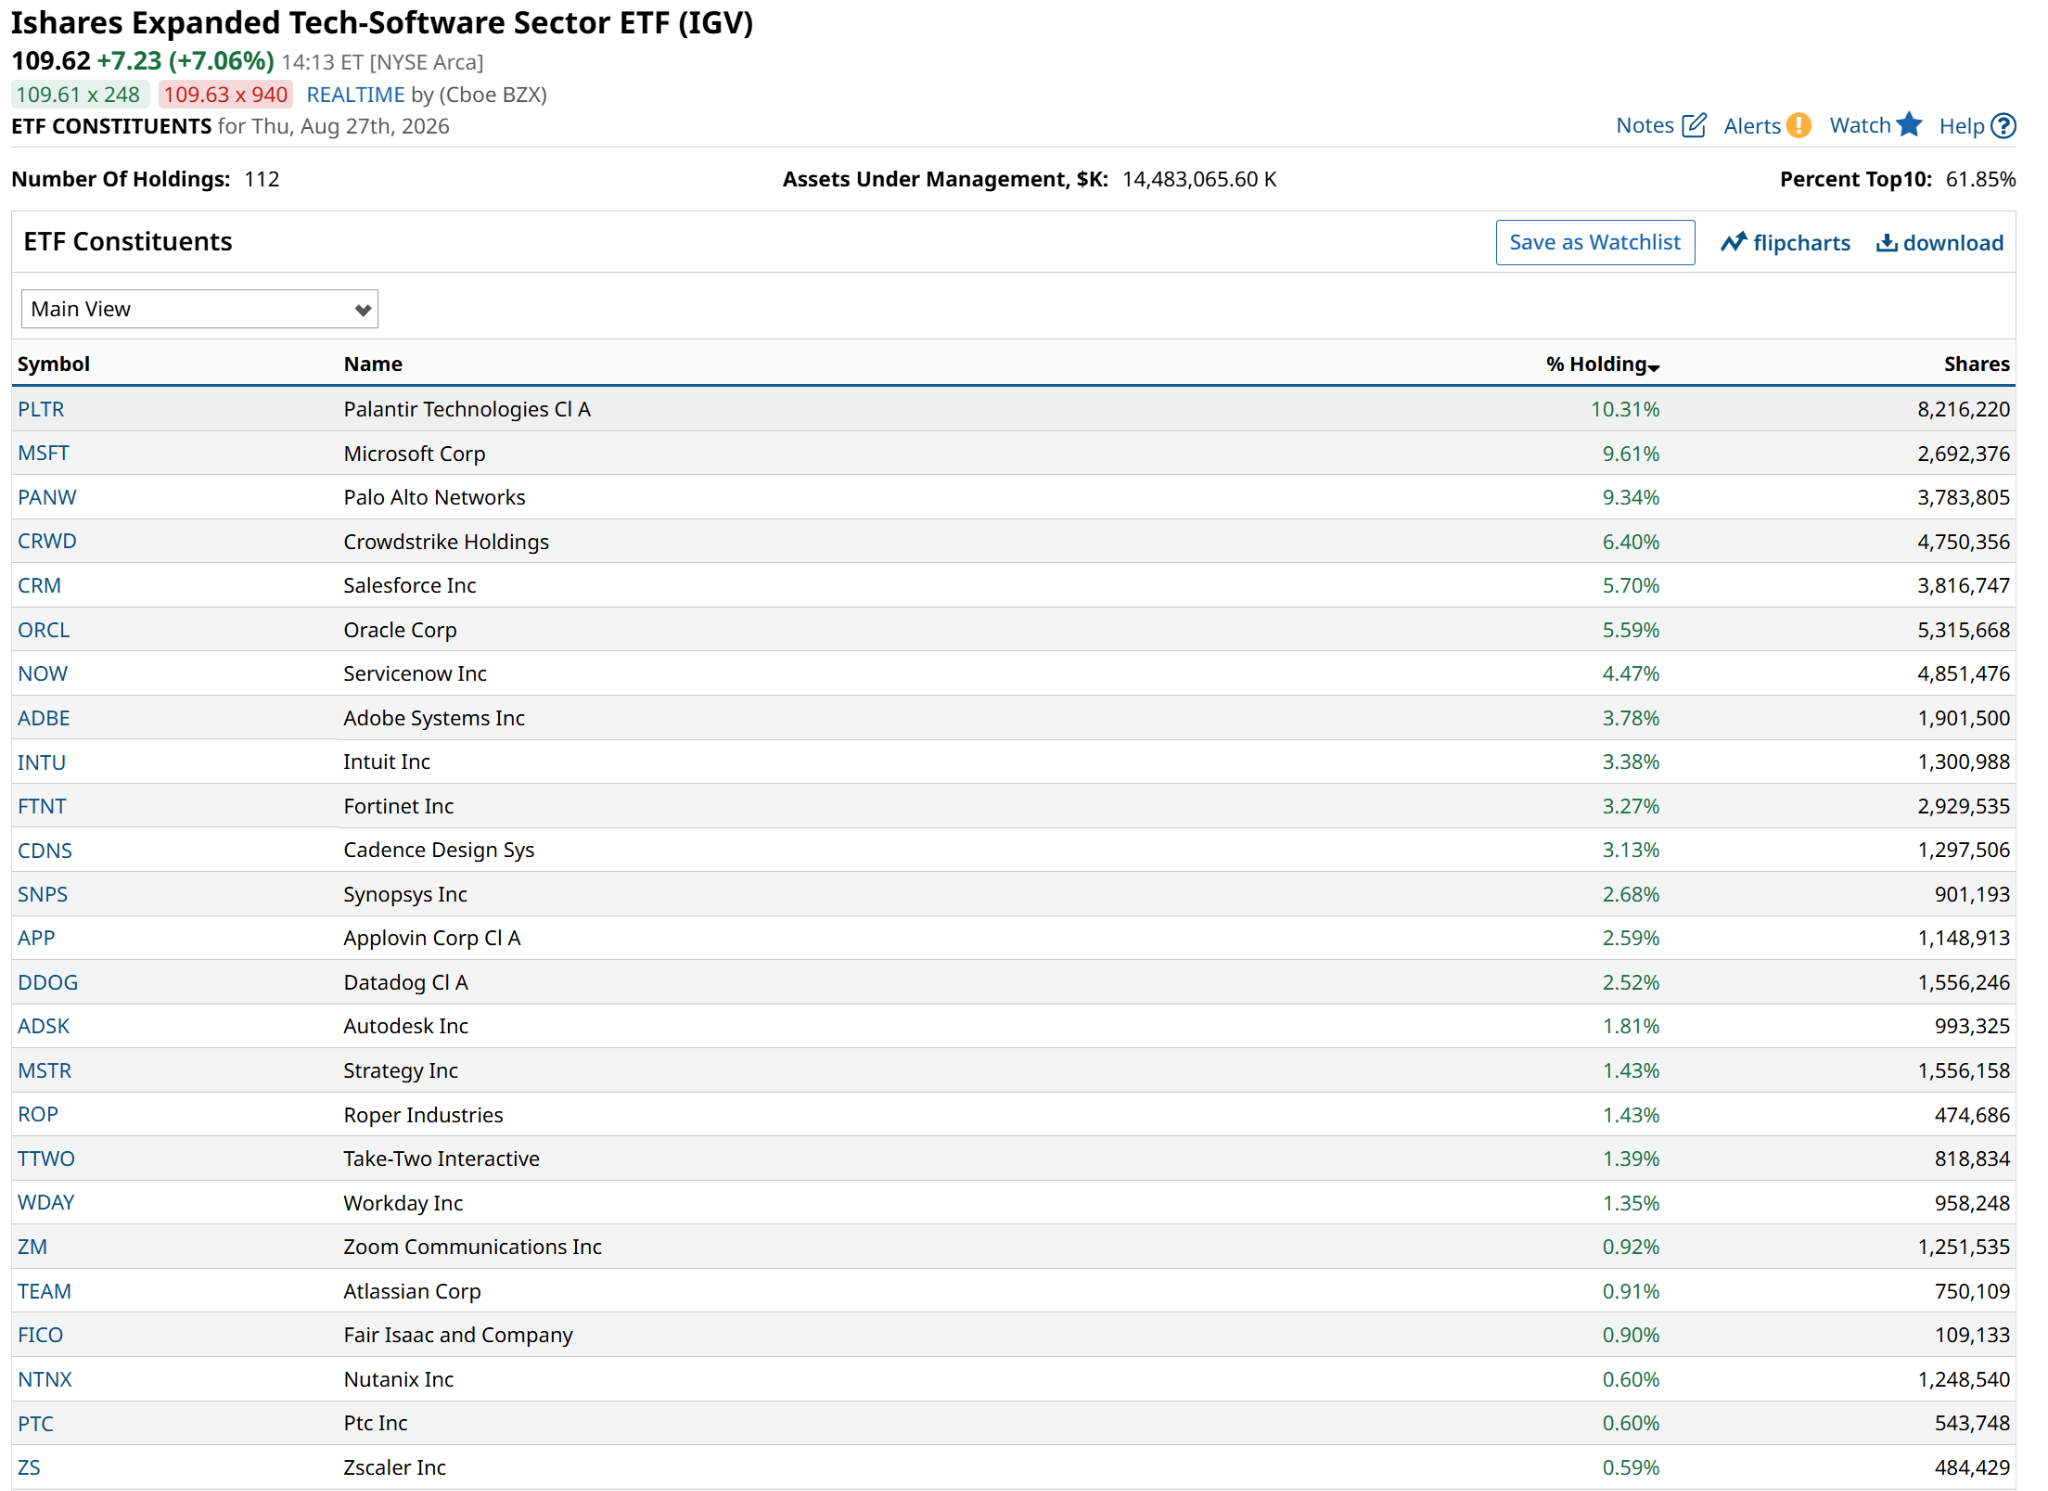
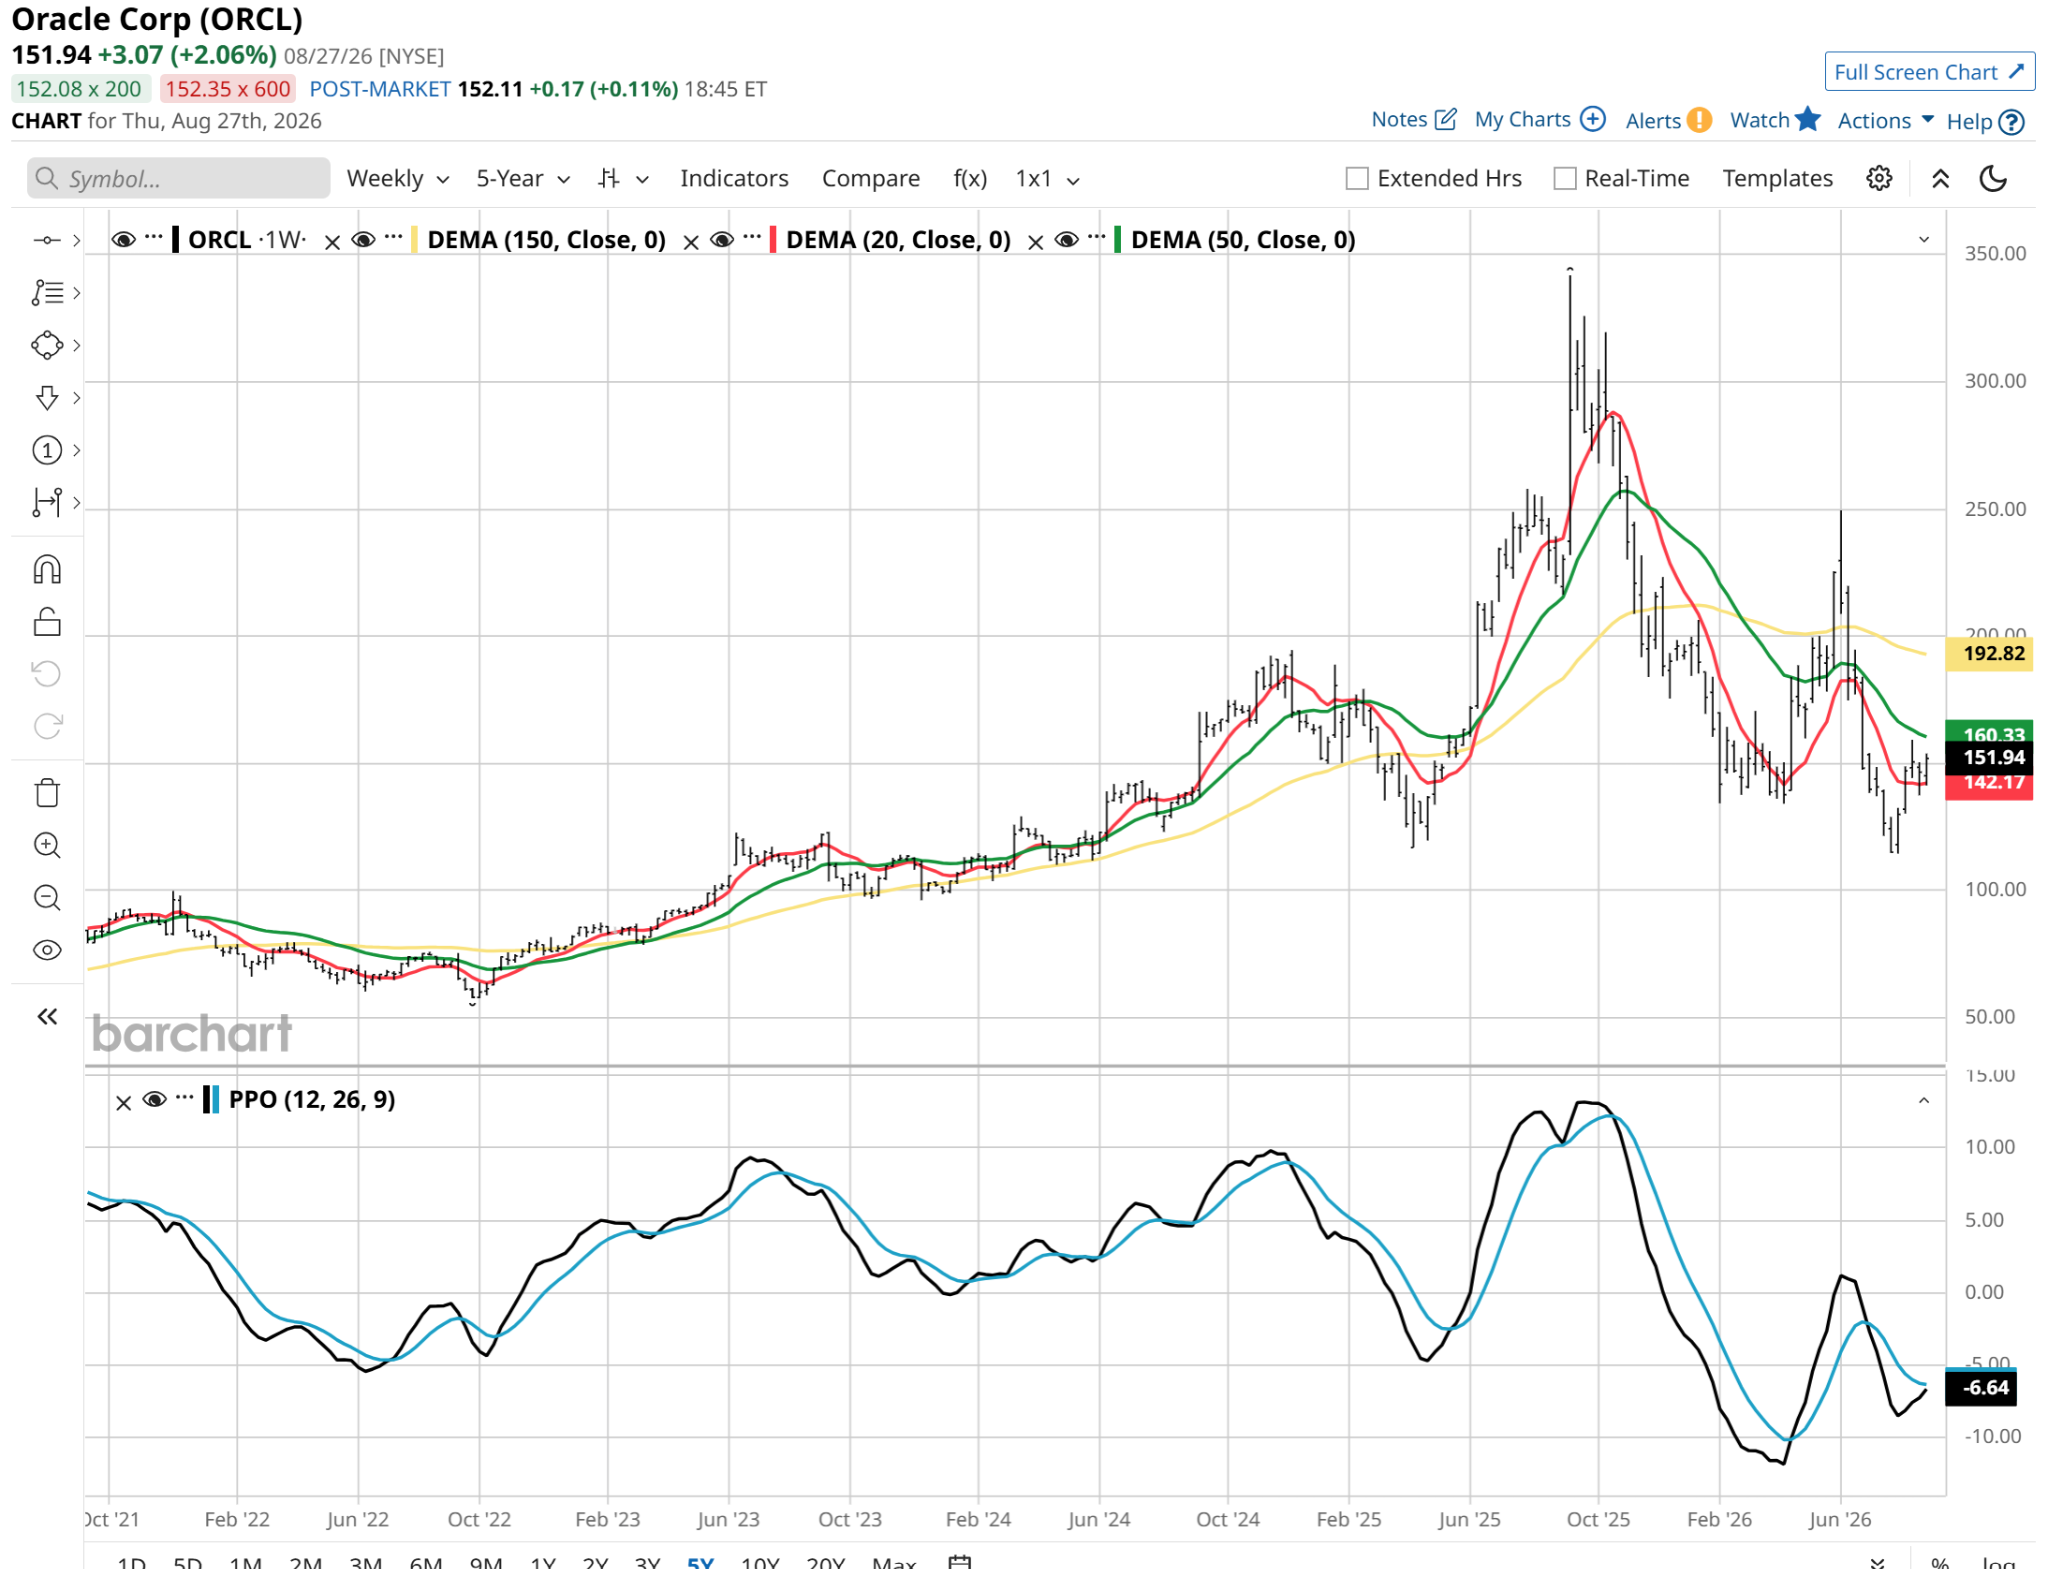
Oracle (ORCL) stands out as a legacy giant that appears to be successfully completing a metamorphosis. Long viewed as a slow-growing database staple, Oracle has repurposed its architecture into a vital multi-cloud infrastructure company.
By establishing direct cloud partnerships with major hyperscalers and providing specialized compute environments for heavy AI workloads, Oracle is capturing more durable corporate spending. Its transition from traditional software licensing to essential cloud database infrastructure gives it pricing power and cash-flow visibility that many application-level competitors currently lack.
If I force myself to look past the short-term noise to a weekly price chart, I can at least point out that the stock is trading at a very familiar trough level, around $150. That’s a better buying spot than we’ve seen in a while.
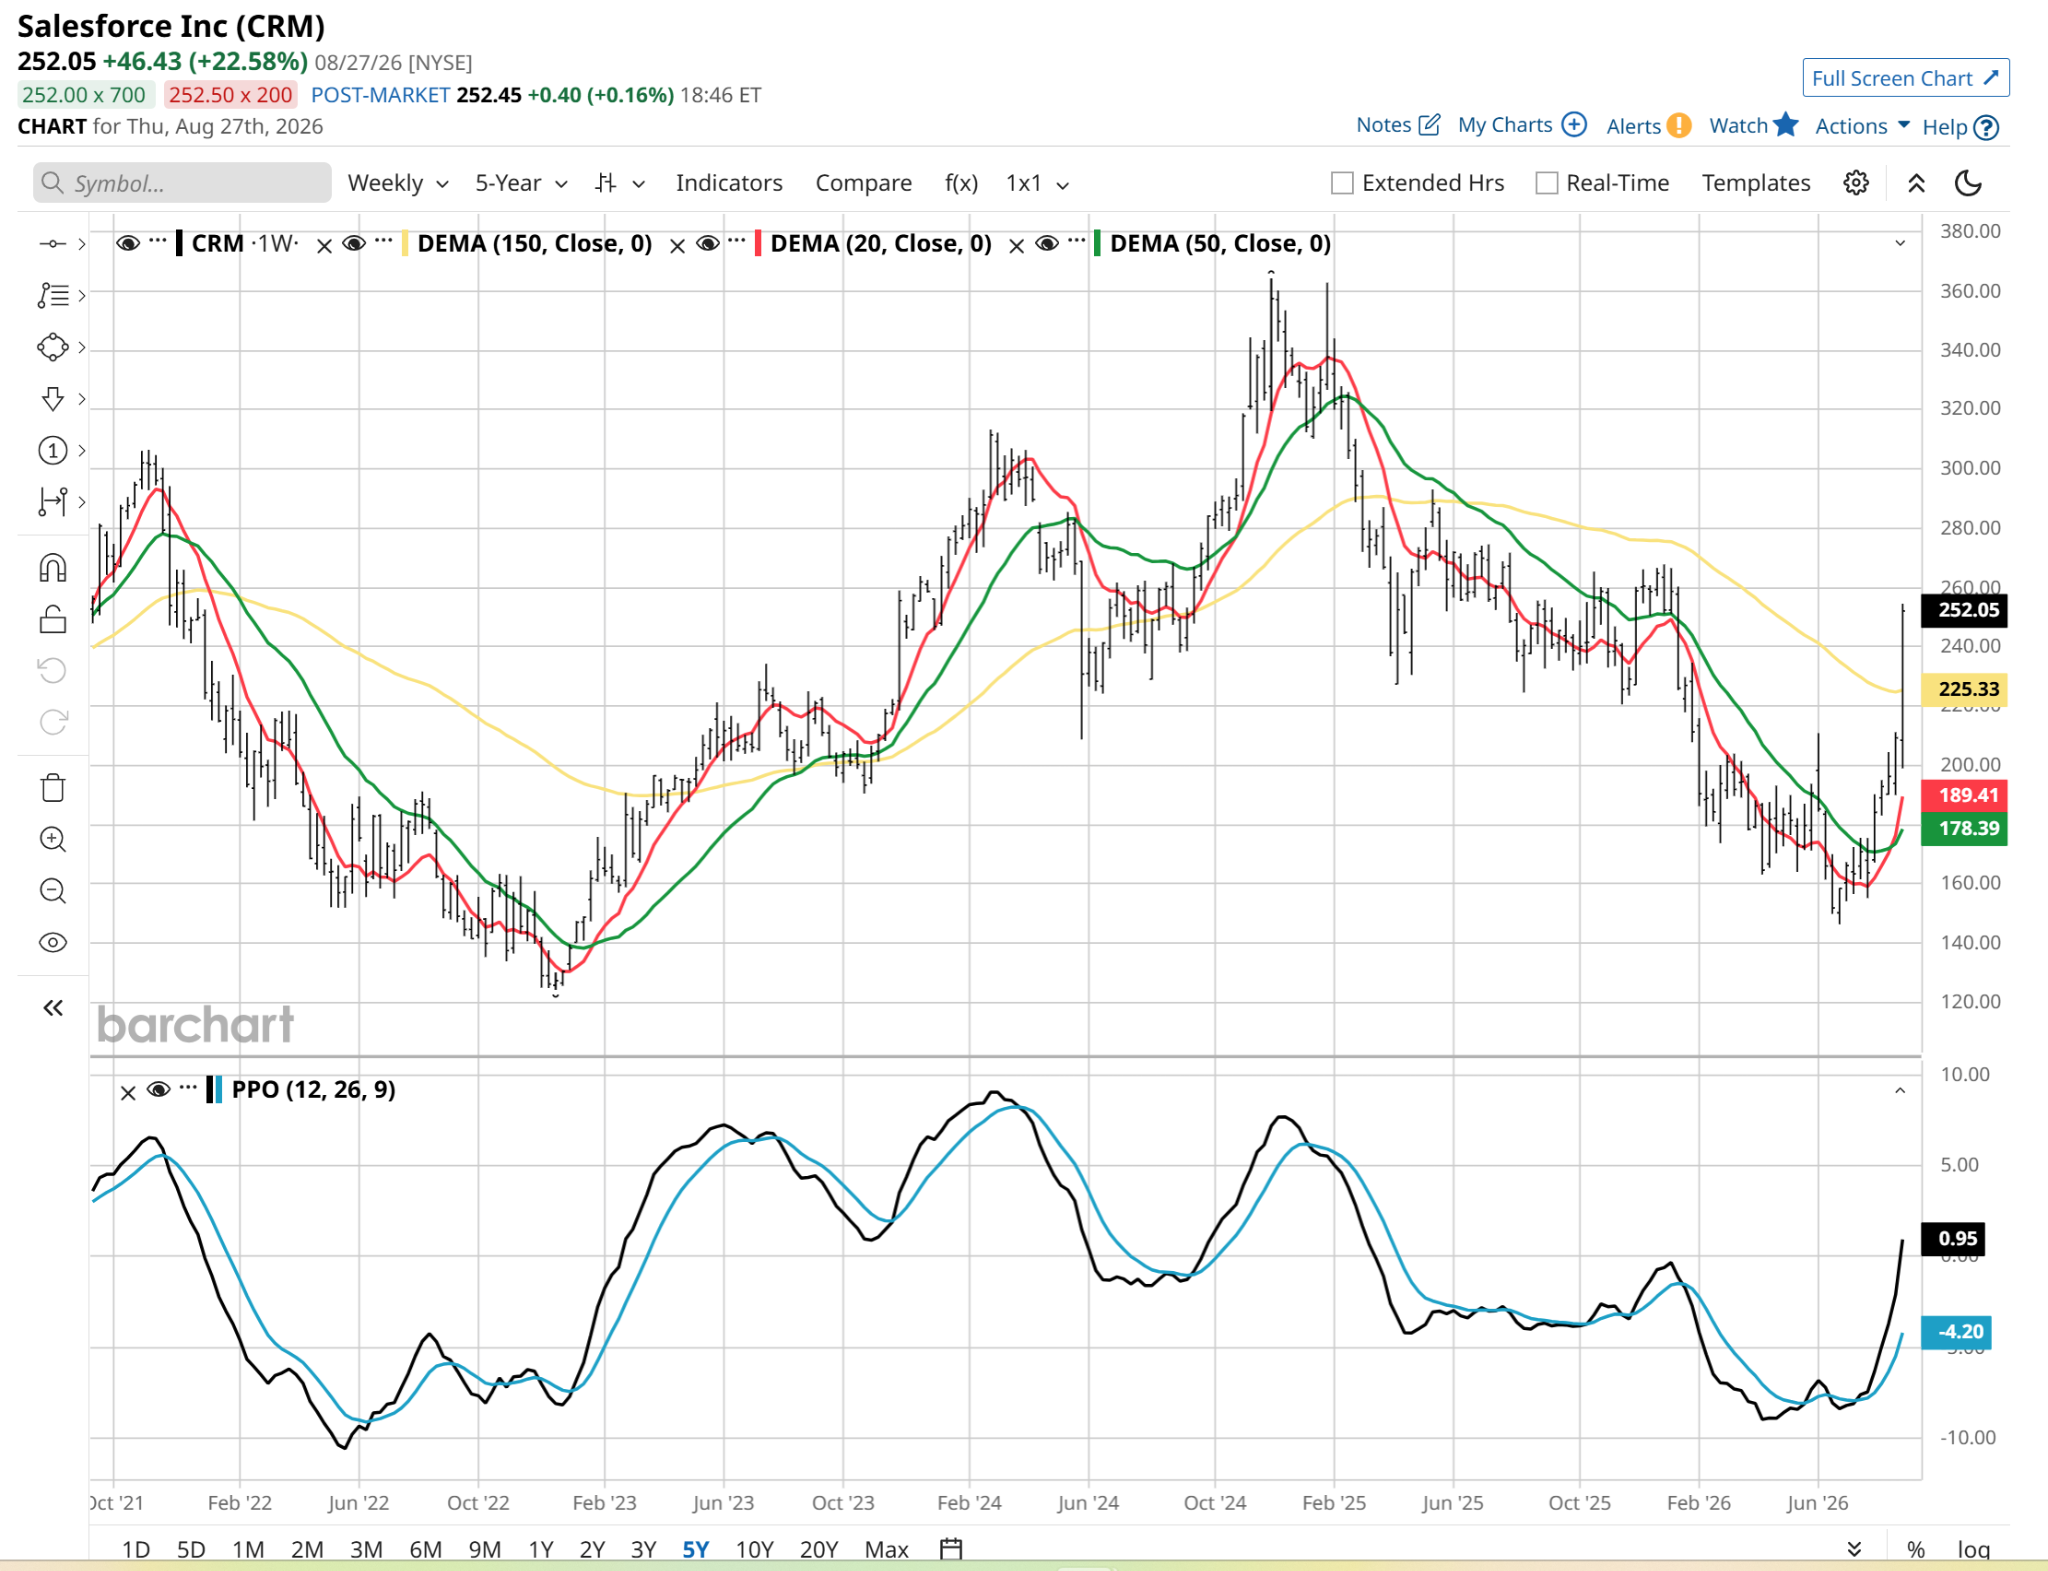
On the other side of the spectrum, high-flying names that mounted impressive rallies are showing clear signs of exhaustion. That includes Salesforce (CRM), which rallied more than 22% on Thursday. Before you get too excited, recall that ORCL did that at one point too, only to top out shortly afterward.
CRM executed a strong run on the back of automated AI agent announcements. But this company’s business model faces a dilemma.
If enterprise clients deploy autonomous software agents to handle sales and customer support, the total count of required human employee seats naturally contracts. Until enterprise SaaS platforms prove they can monetize AI capabilities at a higher rate than the seat-count erosion they cause, upside momentum remains capped. This is not a 2026 AI issue in my view, but it could be the AI-related story of 2027.
The chart looks OK, albeit stretched. At least, in the past that would have been my read of this one below. These days, the algorithmic trading-driven market prompts me to avoid stocks following sharp moves, or trim my position if I’m fortunate enough to own one.
ORCL and CRM are typical of what I see chart-wise across the top holdings in IGV. A mix of good and bad. Here are a couple of more charts to note.
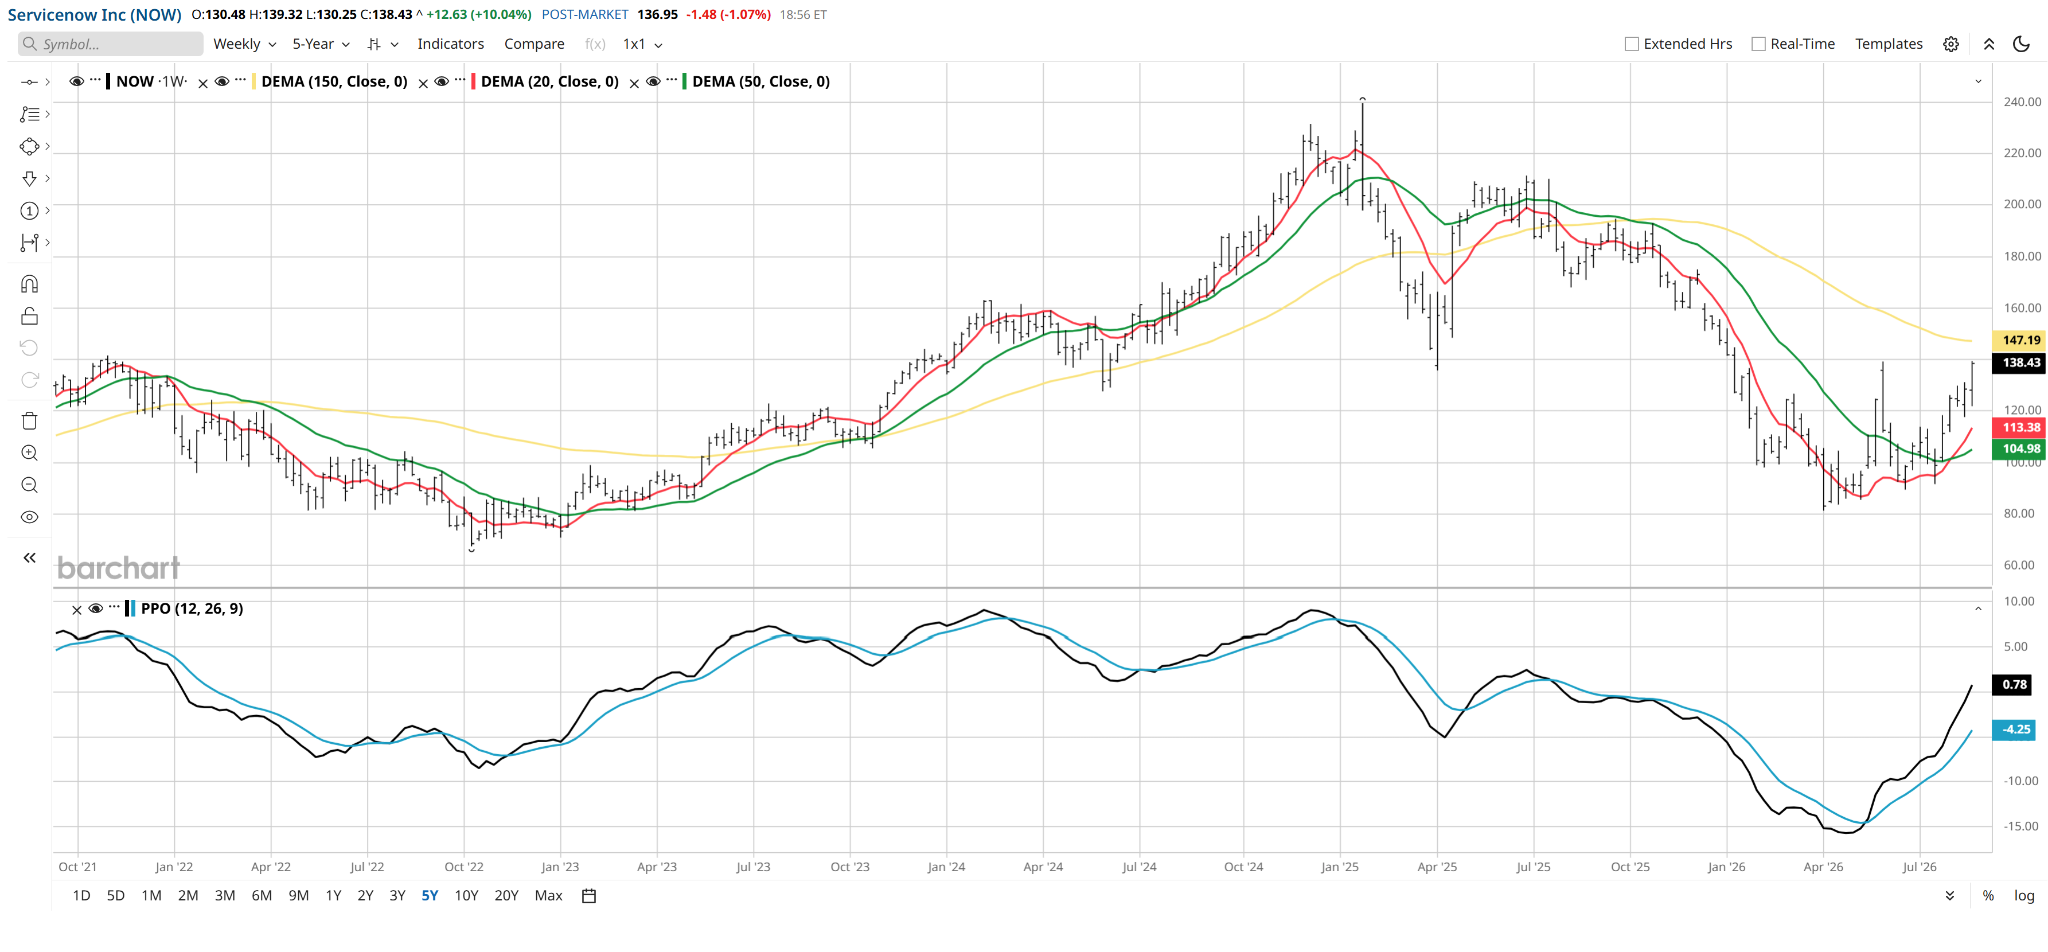
The chart of ServiceNow (NOW) has a fighting chance as I see it. That said, a 200% range from top to bottom since it peaked in early 2025 is not my cup of tea. It indicates to me that sellers could resurface in a heartbeat. Which would make ServiceNow a “Sell Now” in that case.
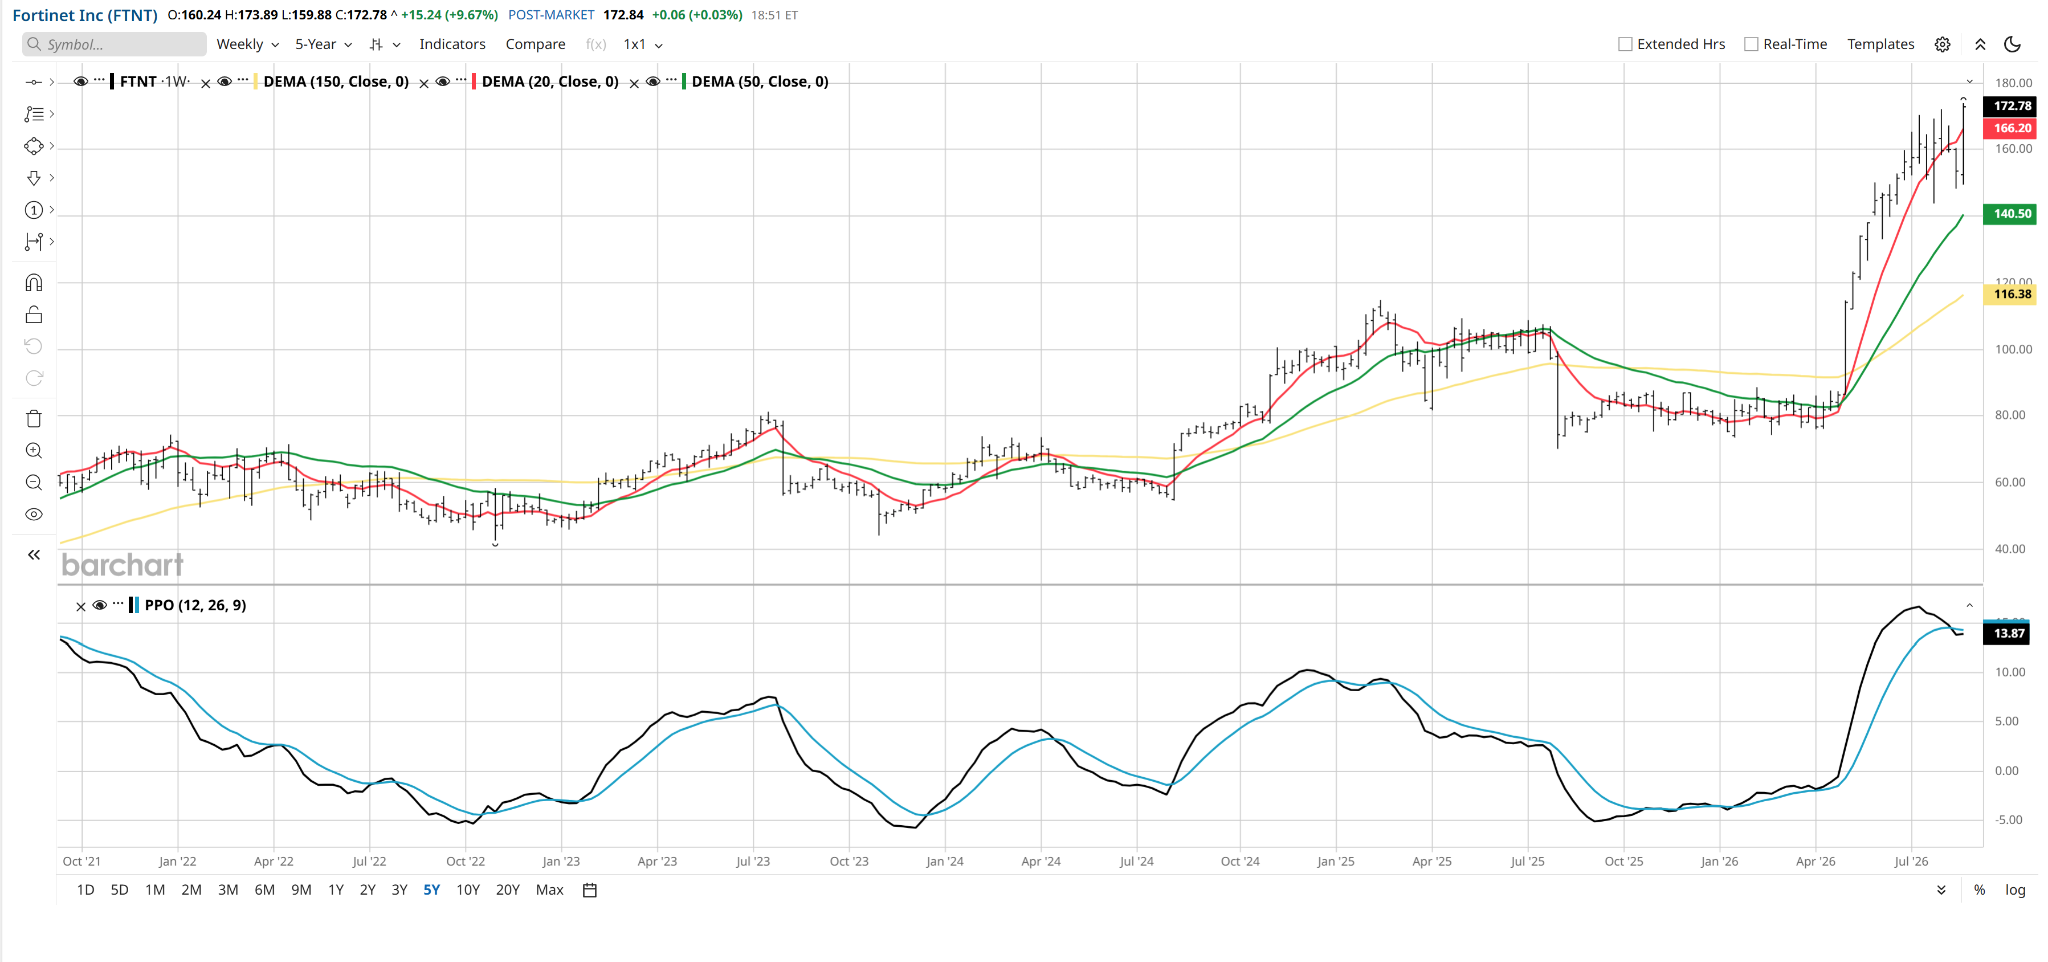
And then, there’s a stock like Fortinet (FTNT), which has been a wild mover and shows signs of topping out on this weekly view.
This internal split explains why holding a broad software basket like IGV feels increasingly like a tug of war. Passive ETF holders own both sides of the coin.The database and infrastructure leaders benefiting from AI implementation, and the application platforms being disrupted by it. That means navigating the software space now requires looking beyond top-line industry headlines, and evaluating whether a company’s product line sits on the right side of the technology shift. That makes IGV better for stock picking among its holdings than for owning outright.
Rob Isbitts is a semi-retired CIO, former fiduciary investment advisor, and Barchart columnist. Check out his other work at ETFYourself.com (featuring the Fresh Charts weekly trading post), and ROAR.PiTrade.com, helping investors to better-manage their own portfolios.