
PhilipCapital started coverage of Snowflake (SNOW) with a Buy rating and a $423 price target on Sept. 28. That bullish stance comes after the stock has already climbed more than 50% year-to-date. The thesis centers on one key figure: 95% of the company’s revenue comes directly from consumption rather than flat subscriptions. PhilipCapital believes this model leaves Snowflake well positioned to capture AI-driven compute demand.
The Rating and the Reasoning
PhilipCapital analyst Alif Fahmi initiated coverage on Snowflake at a time when the consensus rating was already “Strong Buy” with an average price target of around $426. The thesis is built around growing enterprise data volumes and AI adoption, which are driving greater use of cloud-native platforms. The global data lake market is projected to reach $45.8 billion by 2030, while AI products contributed about half of Snowflake’s growth acceleration in the second quarter of fiscal 2027. CoCo and CoWork reached more than 9,100 and 5,800 adopted accounts, respectively, and product revenue grew 37% year over year, marking the company’s strongest growth in three years. Its consumption model provides the main source of leverage as customers purchase credits upfront and use them as workloads run, while AI’s higher compute requirements can mechanically drive greater spending.
About Snowflake Stock
Snowflake provides a cloud-based data platform for various organizations in the U.S. and internationally. Its AI data Cloud allows businesses to bring data from different sources together, gain insights, build data-driven applications, and use artificial intelligence to solve business problems. It operates seamlessly across major cloud providers including Amazon's (AMZN) Amazon Web Services, Microsoft's (MSFT) Azure, and Alphabet's (GOOG) (GOOGL) Google Cloud Platform. Founded in 2012, the company is headquartered in Menlo Park, California.
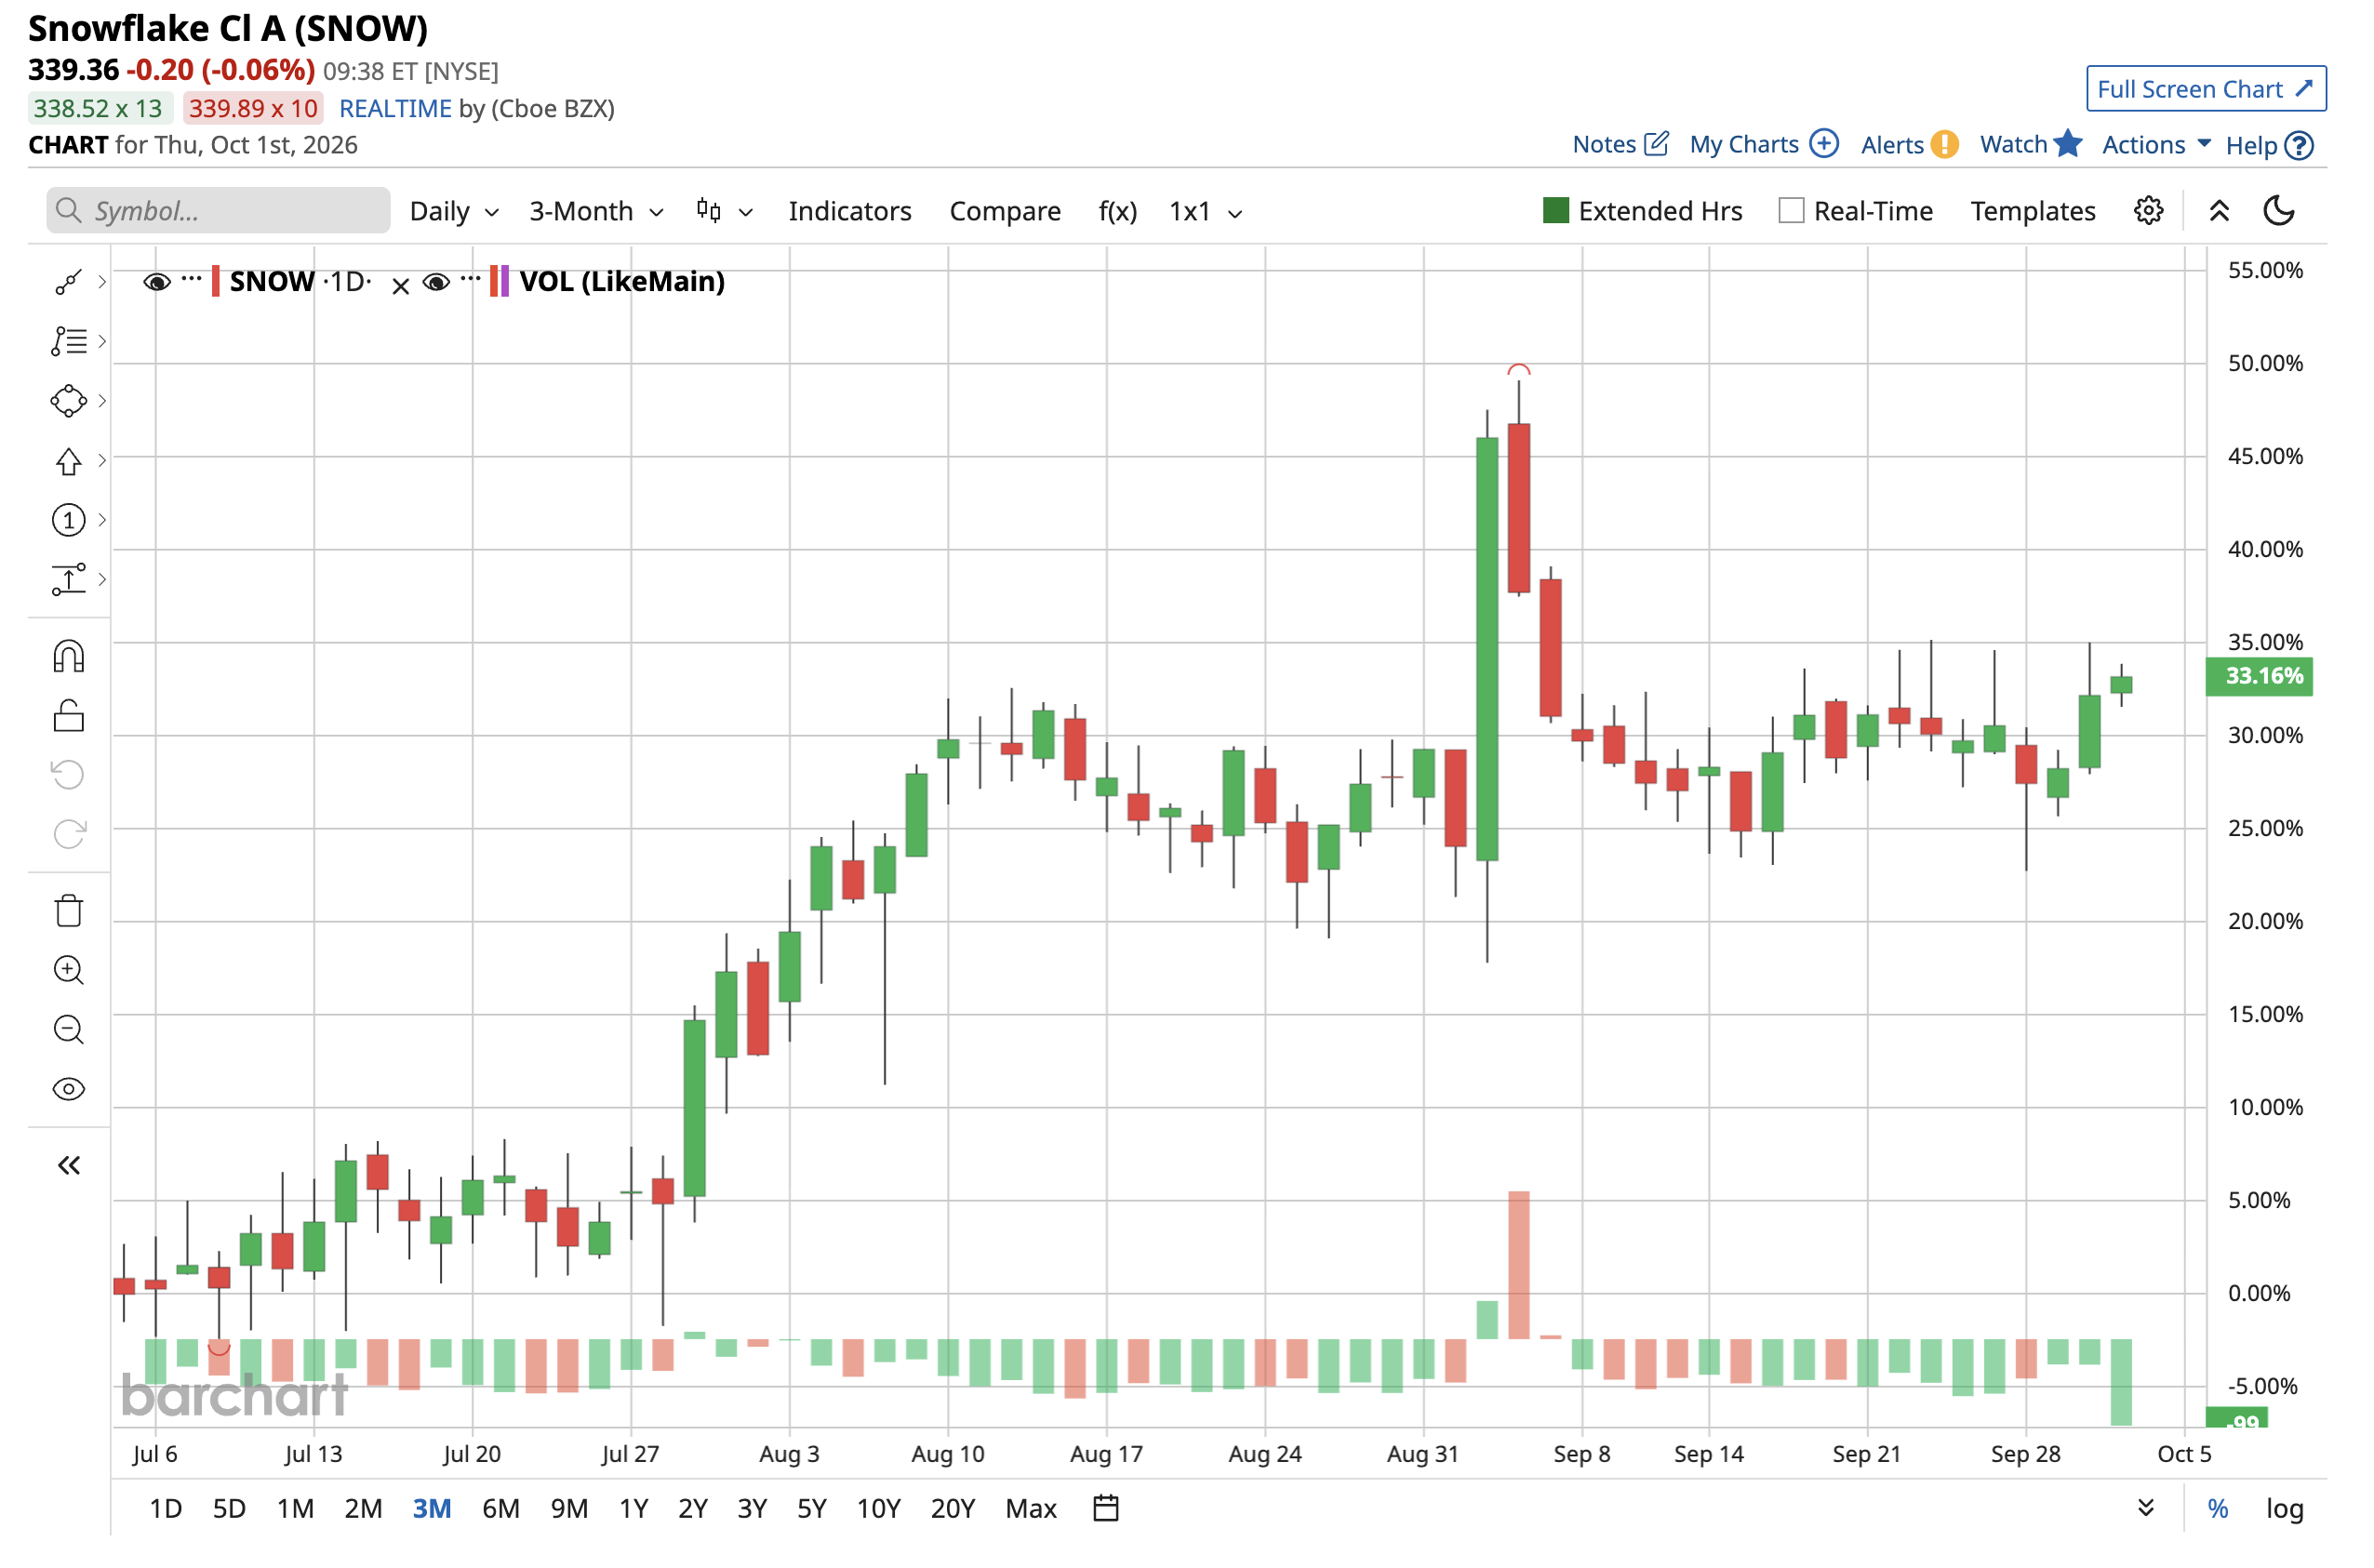
Snowflake has surged 47.3% over the past year, but with high volatility. The stock has ranged from $118 to $385 over the past 52 weeks and sits about 12% below its high. By contrast, the S&P 500 (SPY) gained 14% over the same period and remains only about 2% below its 52-week high. SNOW therefore outperformed the broader market by roughly 33 percentage points, suggesting that company-specific factors, not just overall market sentiment, drove its share price.
What Do the $3.5 Billion Convertible Notes Mean for Snowflake Stock?
The Buy initiation came on the same day the company proposed a $3.5 billion convertible notes offering, sending shares lower on dilution concerns. A Sept. 27 filing pointing to a potential insider sale added to the selling pressure, while a broader risk-off market environment weighed on shares as well. Snowflake’s trailing price-to-sales multiple stands at about 20.78x, while its forward multiple is 18.31x. Both remain below the company’s five-year average. That suggests the current multiple is not stretched relative to Snowflake’s historical valuation.
PhilipCapital’s thesis is built on a clear advantage: 95% of Snowflake’s revenue is tied to consumption. This allows the company to benefit directly from AI usage and drive its strongest product growth in three years. The challenge is that the valuation offers little margin for error. Hedge fund ownership has increased, suggesting institutional investors remain confident in the growth thesis despite recent dilution concerns. At the same time, 5.45% short interest indicates that skepticism has not disappeared.
AI Products Help Snowflake Deliver Another Guidance Raise
Snowflake reported its second-quarter fiscal 2027 earnings on Sept. 2, topping Wall Street expectations, with revenue of $1.55 billion, above the $1.48 billion forecast, and earnings per share came in at $0.62, beating Wall Street consensus of $0.45. The company’s business continued to gain momentum in the second quarter, helped by stronger demand for its core data platform and a faster ramp in AI-related products. Net revenue retention was 126%, remaining performance obligations rose 30% to $9 billion, and Snowflake added 692 net new customers.
Looking forward, Snowflake raised its full-year product revenue forecast to $6.07 billion, which could represent 36% growth. The company also guided for third-quarter product revenue of $1.588 billion to $1.593 billion. The higher outlook reflects strength in both the core business and AI products. Full-year non-GAAP operating margin is expected to be 14.5%. In response to a question, CEO Sridhar Ramaswamy said the growth is coming from many different customers, not just a few large ones. He also said Snowflake’s optimization tools, such as CoCo, help customers use the platform more efficiently and control costs.
What Are Analysts Saying About Snowflake Stock?
Following the company’s quarterly results, many analysts upgraded their financial models and set new price targets. Philip Securities analyst Paul Chew initiated a Buy rating on Snowflake. The analyst gave the rating due to a combination of factors tied to Snowflake’s positioning in a structurally expanding market and its accelerating fundamentals. In addition to Philip Securities, Morgan Stanley reiterated a Buy rating with a price target of $470.
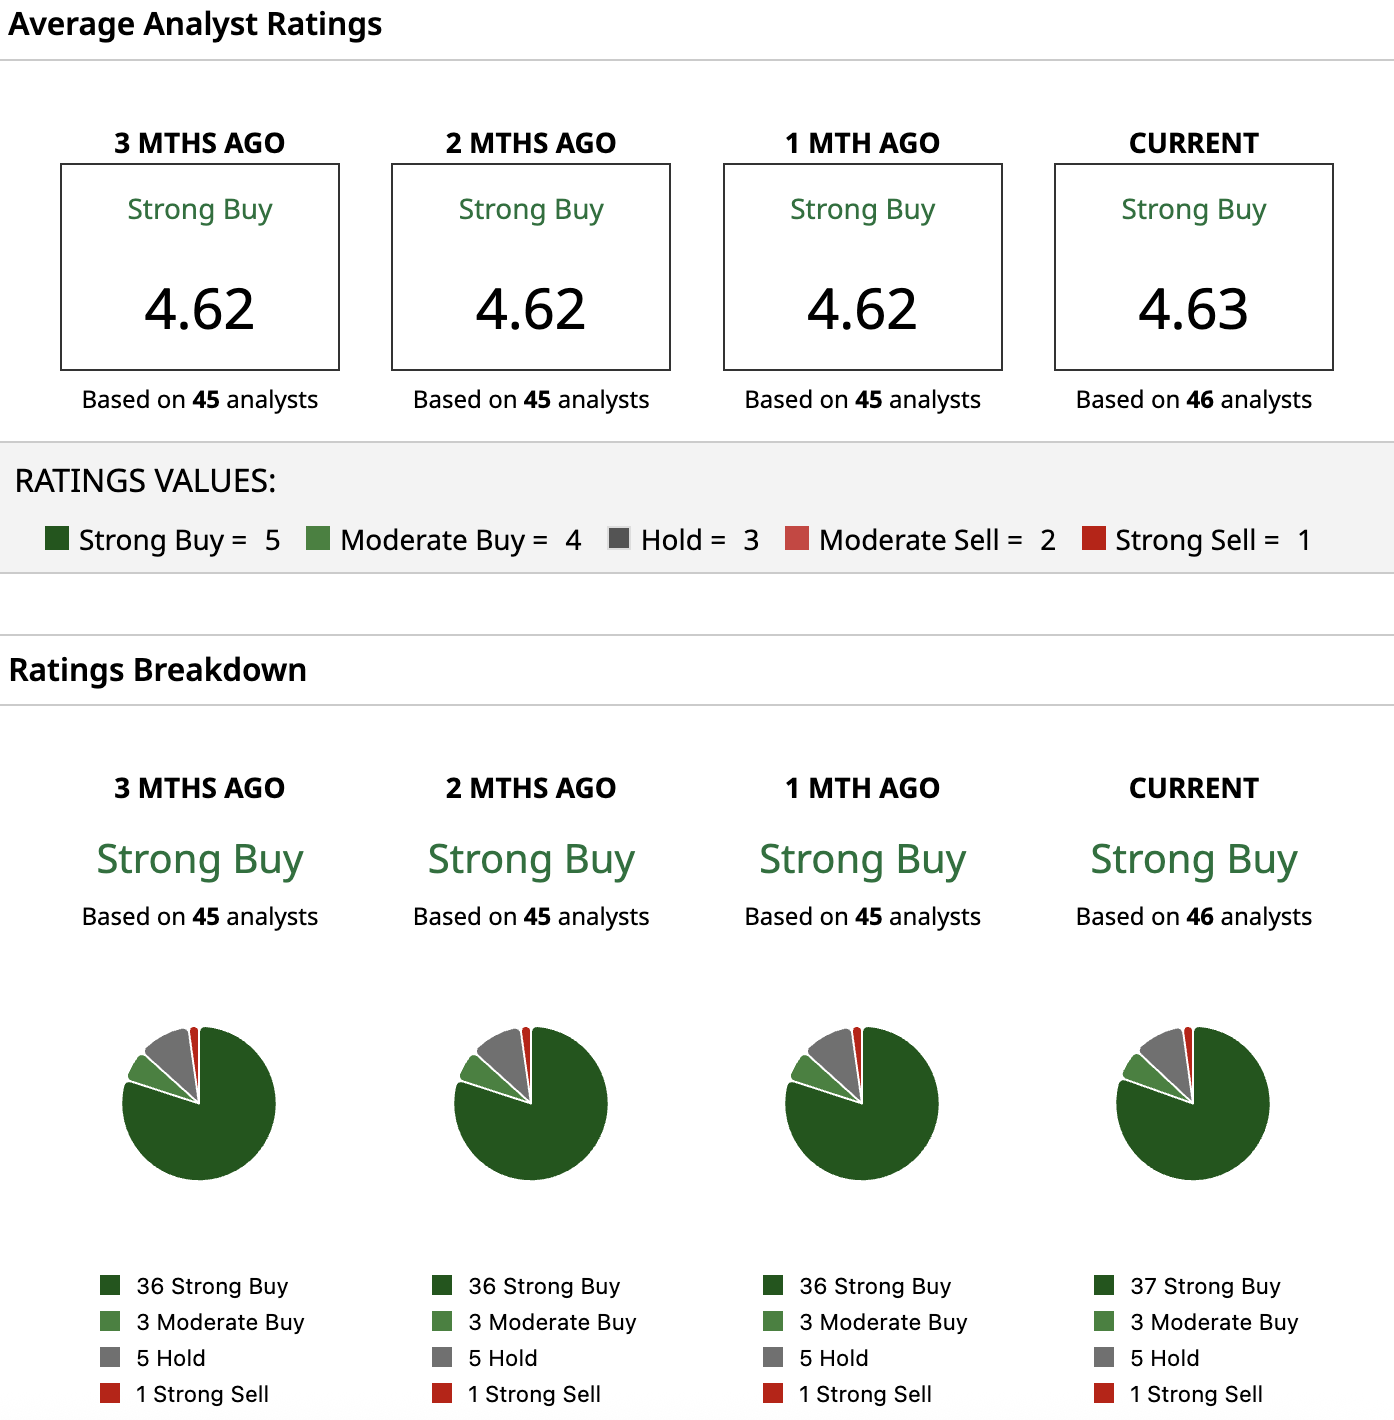
Based on 46 Wall Street analysts covering the stock, SNOW holds a consensus “Strong Buy” rating. The stock’s mean price target of $425 reflects 25% upside from current levels. The high price target of $525 implies an additional 55% upside from the current share price.