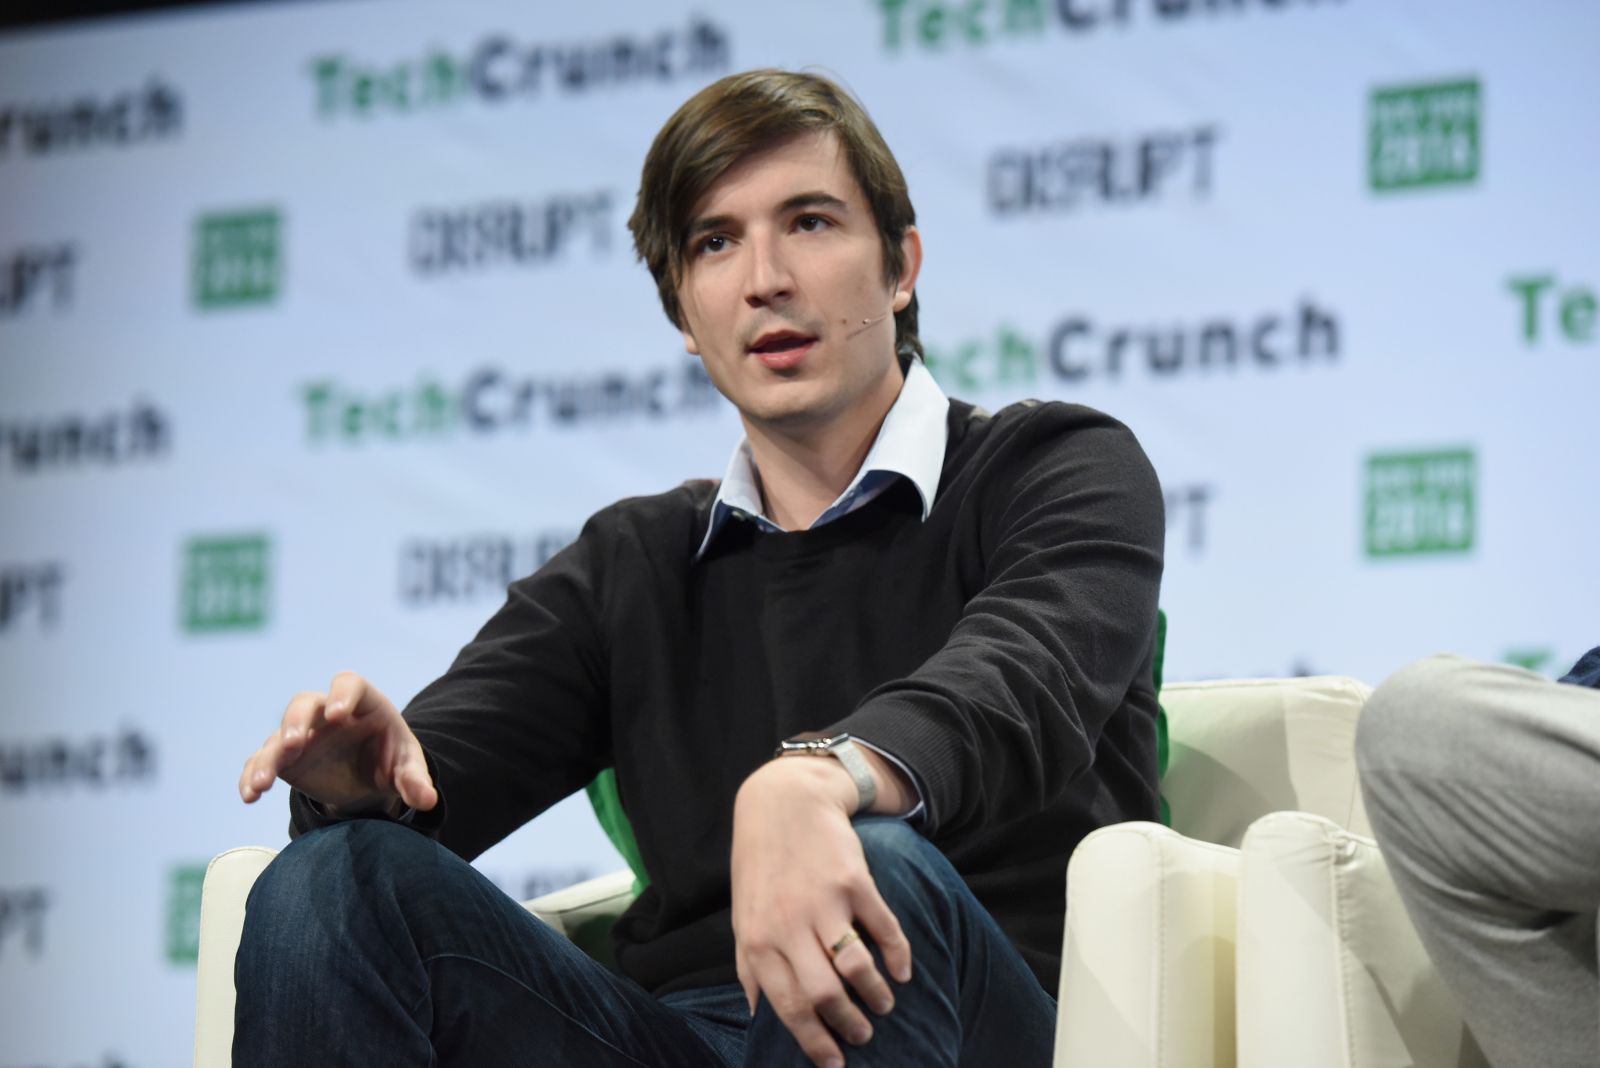
Robinhood chief executive Vlad Tenev told investors that the company's prediction markets business is at the beginning of something much larger, and he put a number on it that most executives avoid saying out loud. "I think we're just at the beginning of a Prediction Markets supercycle that could drive trillions in annual volume over time," he said on Robinhood Markets' (HOOD) fourth quarter and full year 2025 earnings call on February 10.
He reported adoption below the forecast. In the same remarks, Tenev said prediction market volumes had "more than doubled yet again" in the fourth quarter, "with over 12 billion contracts traded in 2025, which is the first full year of Prediction Markets." Customers had traded more than four billion further contracts in the opening weeks of 2026. He called it "the fastest-growing business in our history, $300 million-plus run rate in its first year."
For readers who have never traded one, a prediction market contract is a yes-or-no claim on a stated outcome, priced between zero and one dollar. It settles at $1 if the event happens and at $0 if it does not, so the price doubles as the market's implied probability. Robinhood lists them on sports, elections, economic releases, and a widening set of non-sports categories, under the Commodity Futures Trading Commission rather than state gambling regulators.
Sponsored Content: A $9 Trillion Flying Car Market Is Taking Shape. This Company Is Open to Investors.
The gap between today and "trillions" is still quite a stretch. On the company's first quarter 2026 call, finance chief Shiv Verma told analysts that April prediction market volume was tracking toward roughly $3 billion, which would have been the platform's second-best month on record. Annualize a month like that and Robinhood's own dollar volume is measured in the tens of billions. Bernstein, in an estimate reported in April 2026, put the entire prediction markets industry at $1 trillion of volume by 2030.
He also made a narrower claim than the coverage of it sometimes suggests. "Robinhood is the largest retail brokerage firm in prediction markets, and we've been one of the first to adopt a new asset class," Tenev said on the first quarter call. That statement is about retail brokerages, not prediction markets as a whole. Kalshi, the venue where Robinhood has listed contracts, is an exchange rather than a retail brokerage, so the two aren't competing for the same title.
Set the business against the company, and it is still small. A $300 million run rate is an annualized figure taken from a recent stretch rather than a full year's take, and Robinhood reported $4.5 billion of revenue for 2025. On that comparison, prediction markets are roughly one dollar in every fifteen, which is a lot for a product barely a year old but not much next to a forecast with the word trillions in it. Anyone weighing the forecast against what the market has already paid for the shares can start with Barchart's look at whether the stock has kept pace with the S&P 500, and with what analysts expected from the company's most recent quarter going in.
Robinhood has since been building the plumbing the forecast would require. Rothera — Robinhood's joint venture exchange with Susquehanna International Group — began carrying Robinhood prediction markets and, Tenev told investors on the second quarter 2026 call, "has rapidly become a top three DCM," meaning a designated contract market in the United States. Owning the exchange rather than routing through someone else's changes who decides which contracts get listed, and at what price.
The obvious point is worth making without any edge on it. Every figure here comes from Robinhood, about Robinhood's own product, presented by the executive whose company profits when the volume arrives. That does not make the numbers wrong. It does mean they are company disclosures rather than independent measurements, and the contract counts aren't necessarily dollars.
The regulatory question is also unsettled, which leaves open another aspect of uncertainty in the market. Several states have argued they have a role in overseeing event contracts, the CFTC has treated them as federally regulated products, and the agency withdrew its 2024 proposed rulemaking in February, saying it would pursue a new approach. Tenev said he expects the dispute to run through courts and regulators for years, and how that ultimately shakes out could mean the difference between “trillions” and something closer to the sports betting market.