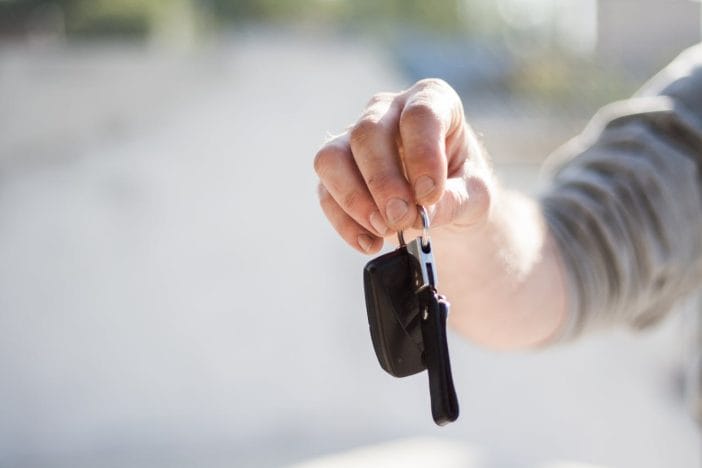
Title loans have long occupied one of the most expensive corners of the consumer-finance market. They offer fast cash in exchange for a vehicle title, but the cost of that speed can be enormous. Interest rates often soar into triple digits, repayment windows are short, and a single missed payment can put a borrower’s car at risk.
While these dangers have not changed, the regulatory environment around title-loan lenders has begun to shift in ways that matter for anyone considering this type of borrowing.