
The artificial intelligence (AI) boom is entering a new phase, and this time, the battle is moving deeper into the data center. It is no longer simply about who can build the fastest AI accelerator. Hyperscalers are scrambling for more compute, faster connectivity, and better power efficiency as AI workloads continue to grow at a breakneck pace. That is opening the door for chipmakers that can deliver customized, energy-efficient solutions at scale.
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Amazon could purchase as much as $60 billion of Qualcomm’s AI data-center chips and related products under the long-term agreement. That gives Qualcomm more than a marquee customer — it gives the company a potential entry point into a market dominated by a handful of established AI chip players. In other words, Qualcomm may finally have its foot in the data-center door.
RBC Capital Markets is taking notice. The firm recently described the agreement as giving Qualcomm a “foothold” in the important data-center AI segment. As a result, RBC raised its price target on QCOM stock to $180 from $160, citing the potentially significant revenue opportunity and Amazon’s scale as a hyperscale customer.
With QCOM stock still nursing a more than 30% drop from its 52-week high, it appears that the chip stock has already taken its share of punches. But with Amazon in Qualcomm's corner and RBC turning more bullish, let’s take a closer look and gauge how investors should play shares from here.
About Qualcomm Stock
Qualcomm is no longer just a smartphone chip story. Based in San Diego, California, the semiconductor giant has built a broad technology business spanning processors, wireless connectivity, licensing, and strategic investments. Its Qualcomm CDMA Technologies (QCT) segment develops chips and platforms, while Qualcomm Technology Licensing (QTL) monetizes Qualcomm’s extensive portfolio of wireless patents, giving the company multiple engines under the hood.
With a market capitalization of about $191 billion, Qualcomm has spent the past four decades helping power the connected world. Now, the company is widening its runway, taking its power-efficient computing expertise into AI, data centers, automotive, enterprise, and industrial applications. Qualcomm's Snapdragon and Dragonwing platforms are central to that push beyond handsets.
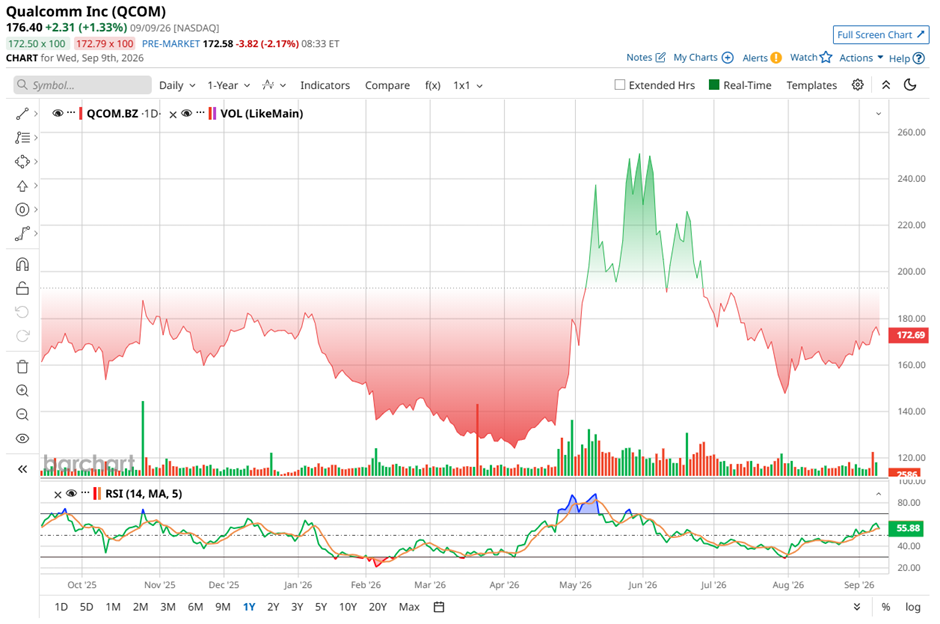
QCOM stock has had anything but a smooth ride this year. The stock started to find its footing in April, bottoming around $121.99, and then absolutely took off. By May, the stock had climbed to a 52-week high of $259.92 — a monster rally that had investors feeling pretty good about the story. But the momentum did not last. Concerns over a potential slowdown in Qualcomm’s core smartphone-chip business sent shares tumbling in July.
Then came another twist. Following its third-quarter earnings-related selloff, QCOM stock dipped to around $142.89 in early August before gradually clawing its way back above $180. The Amazon deal has given the stock a shot in the arm as investors warm to Qualcomm’s push into AI data-center infrastructure.
Despite the wild swings, QCOM is still up 39% over the past six months and up 12% over the past 52 weeks, although the stock remains below its May peak. Technically, the picture is also less bearish. The 14-day RSI has recovered from late July’s oversold territory, suggesting the selling pressure may be easing.
Qualcomm also looks pretty reasonable on valuation right now. The stock trades at roughly 23 times forward earnings, which is in-line with semiconductor sector peers.
There’s a nice income kicker, too. Qualcomm has raised its dividend for 22 consecutive years and currently pays $0.92 per share each quarter, or $3.68 on an annualized basis. That works out to a forward yield of about 2.02%. With a payout ratio of roughly 40%, the company still has plenty of room to keep rewarding shareholders with future dividend hikes.
A Closer Look at the Q3 Report
Qualcomm’s Q3 fiscal 2026 results were a bit of a mixed bag, with one business firing ahead while another hit a rough patch. Revenue came in above expectations, but the bottom line fell short of consensus, underscoring the pressure that higher costs and weaker handset demand are putting on near-term profitability.
For the quarter, revenue declined 4% year-over-year (YOY) to $9.95 billion, while non-GAAP EPS dropped 20% to $2.21. QCT revenue also fell 5% to $8.5 billion, showing that strength outside smartphones was still not enough to fully cushion the mobile slowdown.
The biggest bright spot was the automotive segment. Revenue surged 61% YOY to a record $1.6 billion, marking the 23rd-straight quarter of double-digit growth. Favorable product mix and higher average selling prices contributed $381 million, while higher shipments tied to digital cockpit, advanced driver-assistance, and automated-driving launches added another $223 million.
Handsets revenue, meanwhile, plunged 20% to $5.1 billion as major OEMs cut chipset purchases and worked through inventory amid tight memory supplies and higher memory prices. That weakness more than offset gains across other product categories. Still, there could be some relief ahead, with management expecting China handset revenue to rebound by double digits sequentially in fiscal Q4.
Looking ahead, management anticipates Q4 revenue between $9.7 billion and $10.5 billion, with non-GAAP EPS of $2.05 to $2.25. QCT revenue is projected at $8.4 billion to $9 billion, while automotive revenue is expected to grow annually.
But costs are not going away overnight. Higher wafer, assembly, testing, packaging, memory, and other input costs are squeezing margins, prompting Qualcomm to raise prices. Management expects the gross-margin benefits to build gradually.
Still, there’s a bigger piece of the story investors may want to watch. Qualcomm raised its fiscal 2026 exit outlook for annualized automotive sales to about $7 billion, reinforcing the company’s push beyond handsets.
Analysts expect Q4 EPS to decline 43% YOY to $1.47 per share. For the full year, EPS is projected to slip 23% YOY to $7.74 in fiscal 2026, then decline by another 7% annually to $7.17 in fiscal 2027.
What Do Analysts Expect for QCOM Stock?
RBC Capital Markets sees Qualcomm’s Amazon deal as a meaningful step into the AI data-center market. Under the agreement, Amazon will purchase Qualcomm’s server chips, technology, systems, and manufacturing services, with potential purchases reaching $60 billion. Qualcomm has also issued Amazon a warrant for up to 25 million QCOM shares at $161.26, with vesting tied to purchase orders and commercial milestones. The deal prompted RBC analyst Srini Pajjuri to lift the firm's price target on Qualcomm to $180 from $160 while keeping a “Sector Perform” rating.
RBC estimates the opportunity could eventually generate about $6 billion in incremental annual revenue over 10 years, assuming full vesting — far above Qualcomm’s prior data-center targets of $300 million for fiscal 2026 and $5 billion for fiscal 2027. Revenue recognition is expected to begin in the December 2026 quarter, with some programs already in production. RBC is particularly encouraged by Amazon’s scale as a hyperscaler customer and the broader custom-silicon opportunity.
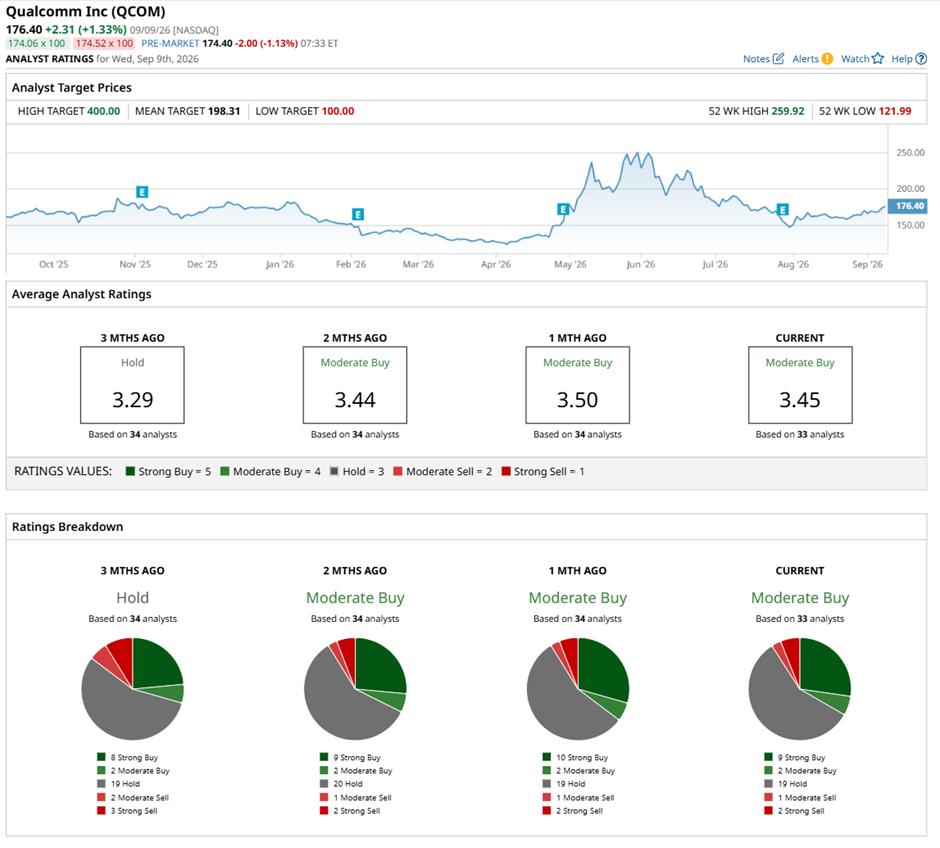
Analyst sentiment toward Qualcomm has improved over the past couple of months. Overall, Wall Street has a consensus “Moderate Buy” rating for QCOM stock, which is an upgrade from its “Hold” rating three months ago. Out of the 34 analysts that cover the stock, nine suggest a “Strong Buy,” two recommend a “Moderate Buy,” 20 analysts have a “Hold” rating, one has a “Moderate Sell,” and two have a “Strong Sell" rating.
Based on the mean price target of $198.03, QCOM stock has potential upside of 5% from current levels. The Street-high target price of $400 implies that shares could rally as much as 113% over the next 12 months.
Final Thoughts
Qualcomm’s Amazon deal certainly gives its AI data-center ambitions more teeth. The company is working hard to become less dependent on smartphones, with data-center revenue targeted at more than $15 billion annually by fiscal 2029, while handsets are expected to account for only about one-third of QCT revenue. The company's partnership with Meta Platforms (META) adds another piece to that diversification story.
But investors still have to separate the headline from the paycheck. That $60 billion Amazon figure is potential business, not guaranteed revenue, and Qualcomm will have to prove it can turn these relationships into real, recurring sales. RBC Capital's $180 price target signals optimism while keeping expectations in check. So, QCOM stock looks intriguing here, but the next chapter will come down to execution, not promises.