Okta’s (NASDAQ: OKTA) summer stock price weakness was warranted, as its security platform came under scrutiny amid industry headwinds and management and integration challenges. However, today's story is completely different: Okta has navigated its prior hurdles and emerged as an AI winner.
It just so happens that AI is driving an exponential increase in digital traffic, increasing the need for ID security and access management, Okta’s specialty. While growth remains sluggish for now, signs point to acceleration and long-term profitability.
Okta’s late-August price action reflects the strength of its newfound position. Up more than 100% from its April 2026 lows, the stock price surged 29% in a single day following the Q2 earnings release. The move confirmed support at a critical level, aligned with the mid-summer breakout, and set a fresh high, confirming the August price action as a continuation signal.
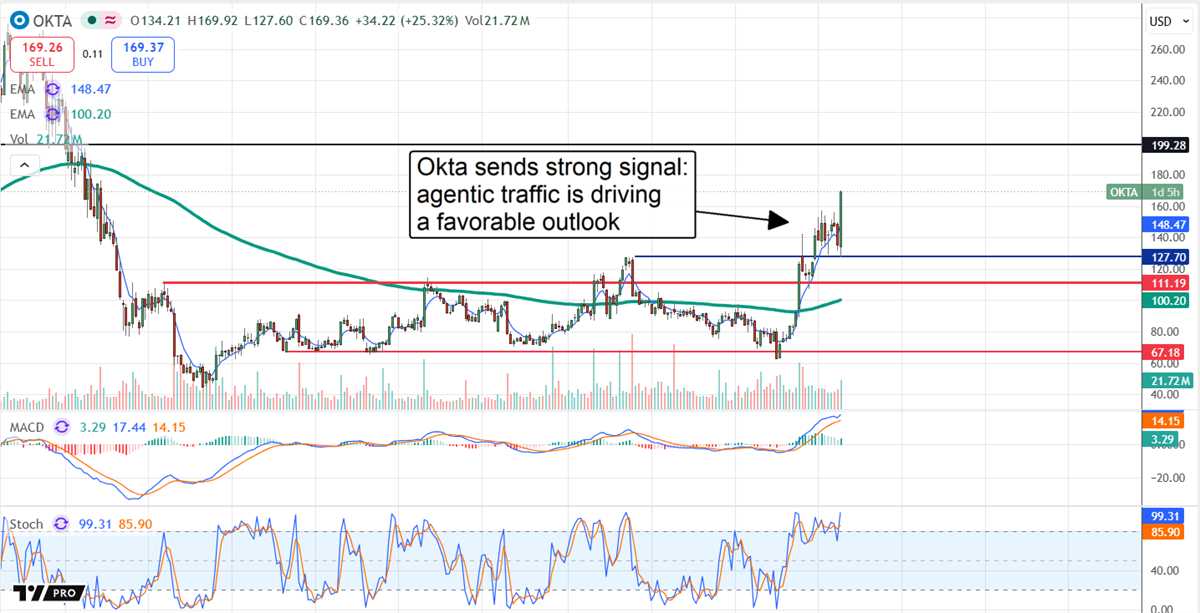
In this scenario, Okta’s uptrend is at best half over, with another $60 to $70 of upside relative to the pre-release highs near $150. As it stands, the near- to mid-term target is $210 to $220, putting this market on track to retest all-time highs within the next 12 months.
Okta Outperforms and Guides Higher on Agentic Traffic Strength
Okta had a good quarter, with revenue growing 10.6% to $805 million, about 150 basis points (bps) better than expected. Subscriptions drove the strength, growing 12%, with internal metrics pointing to sustained strength in the coming quarters. The remaining performance obligation (RPO), a measure of backlog, grew at an accelerated 17% pace, and the current RPO, the portion of the backlog to be recognized within the next 12 months, rose 14%.
Margin was another strength. The company controlled costs while investing in growth, lifting GAAP margins and sustaining strength on an adjusted basis. Adjusted operating margin came in flat, which was good enough, as share buybacks compounded the bottom line for accelerated growth.
The adjusted earnings per share of $1.05 was up more than 1,500 bps year-over-year (YOY) and more than 800 bps above expectations, with strength carrying through into guidance.
Guidance was a catalyst. Executives issued a solid Q3 forecast, expecting revenue above consensus, and improved the full-year outlook to include a low-end target for revenue and earnings above forecast. The likely outcome is that Okta continues to gain momentum in the coming quarters as data center completion and deepening agentic dependence drive traffic.
Can Okta Reach $200? Analysts and Institutions Weigh In
Analysts' initial response to the release was very bullish. MarketBeat tracked eight revisions within the first 12 hours of the release, including several price targets reaffirmed above the consensus, numerous price target increases, and sentiment upgrades.
As it stands, the consensus price target assumes fair value near $168, a slight downside in light of the post-release price pop, but the trend matters more, as it leads to the high-end range. Four analysts assign a price target of $200, which would represent a significant stepping stone for this stock because it aligns with the bottom of its 2020/2022 reversal pattern.
Institutional activity is a critical factor. The group bought aggressively in early Q3, underpinning market support, but has distributed over the trailing 12-month period. The risk is that they sell into the market, but this seems unlikely now that the business has traction. The worst case is that buyers dry up and institutions move to the sidelines, waiting to see what happens next. The best-case scenario is that they sustain their bullish posture and underpin the rally to $200.
A Healthier Balance Sheet Sets Okta Up for Value Gains
Cash flow, the balance sheet, and capital return are driving forces for this stock. The company is profitable and improving its profitability by leveraging AI. Q2 highlights include a 28% free cash flow margin, up 600 bps YOY, supporting a healthy balance sheet and capital returns.
Capital returns consist of opportunistic share buybacks, with Q2 activity aiding a 1.1% YOY reduction and ample authorization remaining. Balance sheet highlights reflect the impacts of debt reduction and buybacks, with cash, assets, and liabilities down. Key details include zero long-term debt as of quarter-end and steady equity, along with healthy cash flow, setting the stage for aggressive value gains in upcoming quarters.
Weighing Okta's Breach Risk Against Its Agentic AI Upside
Okta’s biggest risk is its position as an ID control plane. That makes it a prime target for attack, especially via third-party vendors who inadvertently receive overinflated authorizations. Breaches mean lost trust and impaired business, and they will be reflected in the stock’s price. Catalysts include expanding penetration of digital services throughout the ecosystem, agentic traffic, and the proliferation of hyperscale datacenter supercomputers slated to come online over the subsequent 12 to 24 months.
The article "Okta Stock Surges 29%—Is $200 the Next Stop?" first appeared on MarketBeat.