Oil prices slipped back below $100 this week, and Diamondback Energy (NASDAQ: FANG) shareholders felt every bit of it. The Permian Basin producer now trades about 11% below its September high. The sharpest blow came on Sept. 16, when FANG fell roughly 8% in one session.
The prevailing sentiment is that cooling crude means cooling oil stocks. Investors are treating a resolution between the United States and Iran as the end of the energy trade. But that's not the entire story.
Brent crude is still in the high $90s, and West Texas Intermediate sits near $90. The forces supporting high oil prices don't disappear when the Iran headlines fade.
The Middle East supply gap is measured in weeks and months, not days. And oil demand is also tied to the AI infrastructure buildout. There's also a broader wave of grid, construction, and manufacturing projects that rely on diesel, asphalt, and petrochemicals.
Together, those factors point to a higher floor for oil. That doesn't guarantee $100 crude every day. But it does mean the dips may be shallower than the market fears. For investors, Diamondback Energy's sell-off looks more like an opportunity than a warning.
What Actually Took a Bite Out of FANG
The Sept. 16 drop had less to do with oil than it appeared. Three things simultaneously hit the stock.
-
Morgan Stanley cut FANG to Equal Weight, arguing the shares had run ahead of fundamentals.
-
An investment vehicle tied to Endeavor's founding Stephens family sold more than 9 million shares, a block worth roughly $1.9 billion.
-
The Fed's rate decision that afternoon pushed money out of energy.
None of those factors changes how many barrels Diamondback produces or what it earns on them. A block sale is a supply-of-shares event, and it's temporary by design.
Wall Street seemed to agree. Within days, Raymond James raised its target to $255, and UBS lifted its target to $253. It's also important to note that FANG trades at about a 20% discount to its consensus price target of $226.33.
Earnings Tell the Real Story
Diamondback's Q2 2026 earnings report shows a business firing on all cylinders. Earnings came in at $6.48 per share, topping estimates by 40 cents. A year earlier, that figure was $2.38. Revenue jumped 51% to $5.56 billion, beating forecasts by about $675 million.
Management also raised 2026 production by roughly 3% to 4% and cut net debt by $1.6 billion. CEO Kaes Van't Hof said global inventories are draining and will eventually need to be refilled. That's the higher-floor thesis, coming straight from the operator.
The Inventory Scare Is a Sideshow
The latest leg lower followed a report from the American Petroleum Institute. It showed an unexpected build of about 1.8 million barrels in U.S. crude stocks. Traders sold first and asked questions later.
But the Energy Information Administration's official numbers haven't confirmed that build. Even if they had, one week of U.S. storage data says little about a global market this stretched.
The Supply Gap Isn't Closed
Saudi Arabia shut its East-West pipeline on Sept. 11 after drone strikes damaged pumping stations. Since the Strait of Hormuz was disrupted, Riyadh has used that line to reroute about four million barrels per day. That's roughly 4% of the global supply. Loadings at the Red Sea port of Yanbu stopped with it.
Aramco restarted the pipeline this week, but at a low rate. A full return could take six to eight weeks. Meanwhile, the Houthis targeted Yanbu again over the Sept. 18-19 weekend. The market is pricing in a quick fix that isn't supported by the realities on the ground.
The Floor Isn't Just About Iran
Investors treat oil's premium as a war premium. But a meaningful share of today's demand has nothing to do with the Middle East.
Every AI data center starts as a construction site. Steel, concrete and copper arrive on diesel trucks. Diesel equipment pours foundations and runs cranes. Many facilities rely on diesel generators for backup power. Cable insulation, cooling components and enclosures lean on petrochemicals.
The AI buildout isn't happening alone, either. Grid upgrades, transmission lines, highway work, and reshored manufacturing plants all compete for the same fuel. This kind of demand is sticky. A hyperscaler doesn't pause a multibillion-dollar campus because diesel costs more.
Diamondback also has a direct line into the AI story. On its Q2 conference call, management detailed a power project on its 30,000-acre Bryant Ranch near Midland. Behind-the-meter power could start in the back half of 2027, with grid connection as soon as 2028. Diamondback would supply gas, land, and water. Diamondback hasn’t yet finalized an agreement with a hyperscaler for the Bryant Ranch project. Still, that's the kind of optionality the market isn't paying for today.
What the Chart Says
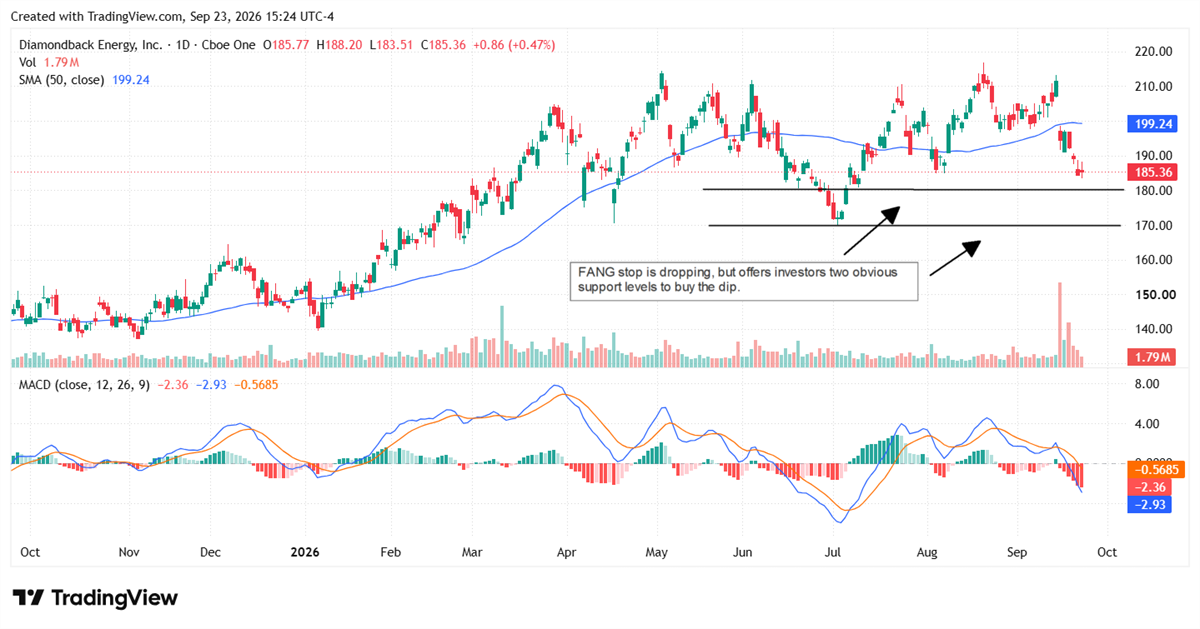
The technical picture argues for patience in how investors buy, not whether they buy. FANG trades near $188, below its 50-day moving average of around $199. The MACD sits below its signal line, so momentum hasn't turned yet.
The first support zone is near $180. Below that, the July low near $170 is the level to watch. Scaling in across those levels makes more sense than a single lump sum buy. A close back above the 50-day would signal that sellers are exhausted.
Investors Shouldn't Fear the Volatility in FANG
The perception is that oil below $100 means the energy trade is over. The fundamentals say otherwise. The Middle East supply gap will take weeks to close. AI and infrastructure demand gives crude a sturdier floor than past cycles. And Diamondback's sell-off came from share supply and a downgrade, not a broken business.
Oil will stay volatile, and FANG will move with it. But volatility around a higher floor is a buying setup. For investors with a longer view, the dips in Diamondback and other quality oil producers look like opportunities to accumulate.
The article "Oil May Be Stronger Than It Looks—And Diamondback Is on Sale" first appeared on MarketBeat.