
Morgan Stanley just delivered a major warning for Applied Materials (AMAT) investors.
The firm cut its price target on Applied Materials to $563 from $642 while keeping an “Equal-Weight” rating. That is a $79 reduction, or about 12%, even as Morgan Stanley raised its 2027 revenue and earnings forecasts. The reason is valuation: the firm lowered the multiple it uses from 26 times to 22 times.
That price cut really spooked investors' confidence, as Applied Materials is benefiting from the AI-driven semiconductor buildout, but the stock has already had a massive run. Now Morgan Stanley's move suggests the debate is shifting from whether the business can grow to how much investors should pay for that growth.
Morgan Stanley Cuts Its Applied Materials Stock Target for a Different Reason
Applied Materials' stock is up about 99% year-to-date (YTD), helped by AI-related demand for chipmaking equipment and higher spending on advanced logic, memory, and packaging.
But the rally has cooled. Shares have pulled back 29% in the past three months due to valuation concerns and investor caution even after strong earnings.
That makes Morgan Stanley's target cut notable. The firm is not pointing to a weaker business outlook. Instead, it is saying the stock price has moved faster than its earnings expectations.
Applied Materials trades at roughly 10 times sales, versus about 5 times for the semiconductor equipment industry. On forward earnings, it trades near 27 times, compared with about 30 times for ASML (ASML).
Morgan Stanley actually raised its 2027 revenue forecast to $50.7 billion and EPS forecast to $20.92. Yet it reduced the valuation multiple applied to those earnings from 26 times to 22 times, cutting $79 from the price target.
This means the earnings outlook improved, but the price Morgan Stanley is willing to pay for those earnings fell. For investors, future upside may depend increasingly on profits growing into AMAT stock's premium valuation.
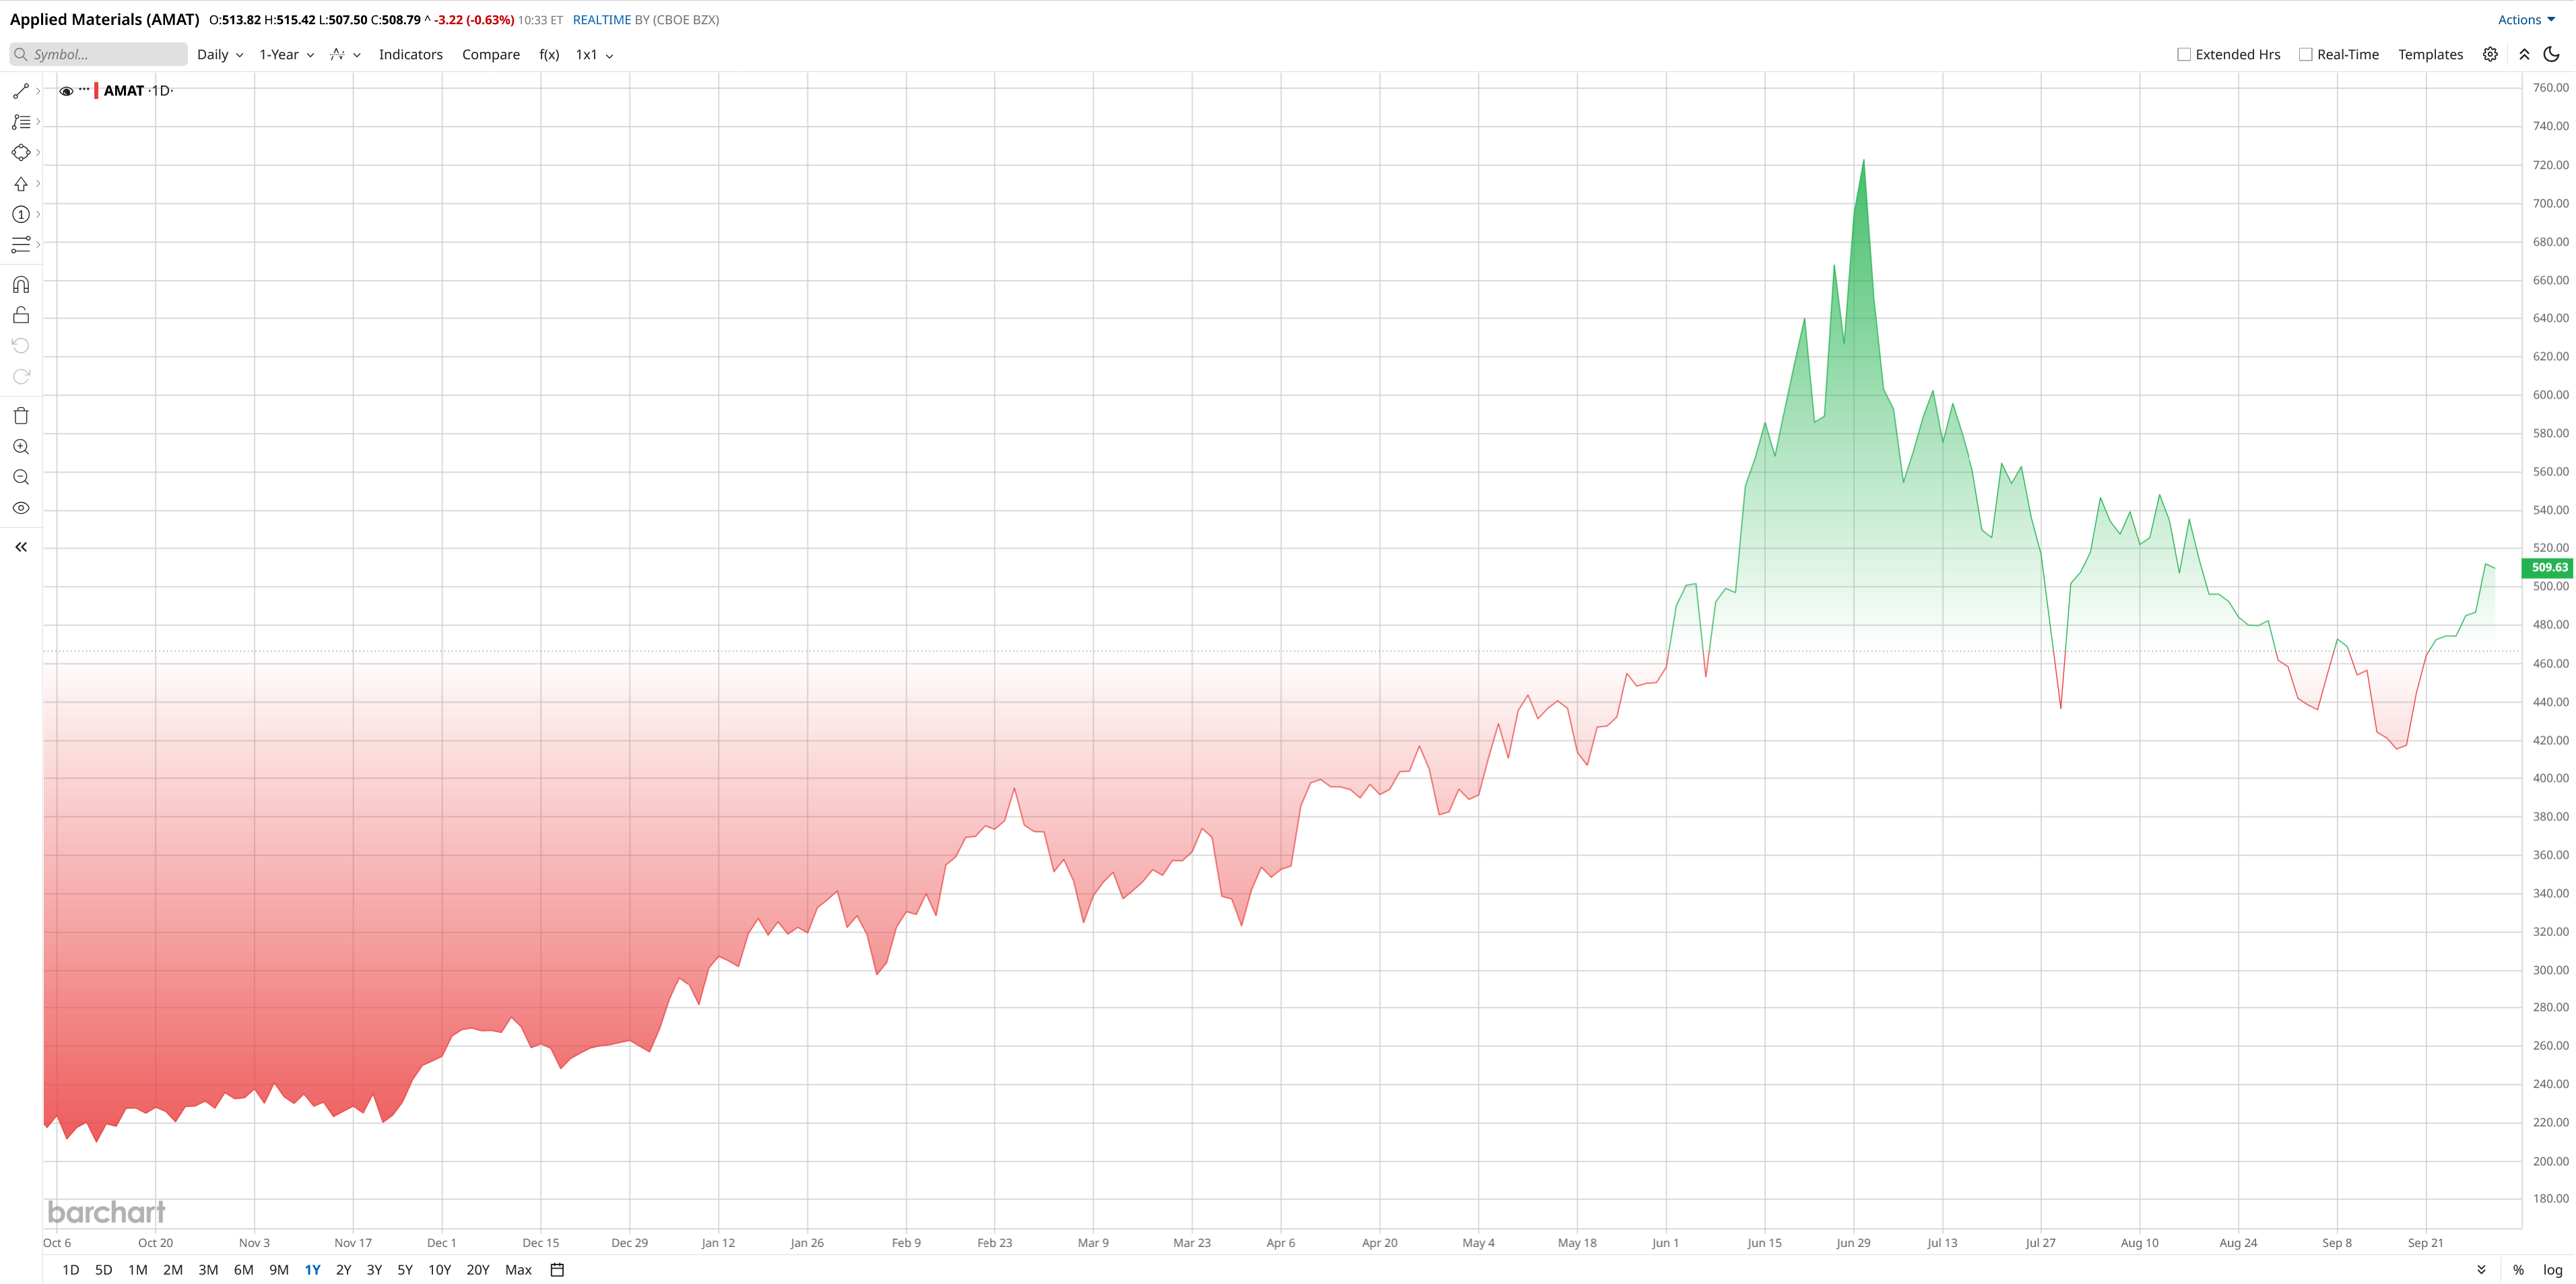
Beat Q3 Estimates as AI Demand Stays Strong
Applied Materials' fiscal third-quarter results showed why the long-term story remains intact. Revenue hit a record $9.12 billion, up 25% year-over-year (YoY). The company beat expectations on both major measures. EPS landed at $3.50 versus a consensus estimate of $3.38, while revenue topped the roughly $9 billion estimate.
Net income rose 43% to $2.54 billion, and free cash flow reached $2.33 billion. The company ended the quarter with $7.04 billion in cash and equivalents.
Looking forward, Management guided for fiscal fourth-quarter revenue of about $10.25 billion at the midpoint and EPS of $4.02. AI demand across leading-edge logic, DRAM, and advanced packaging is helping drive that momentum.
Applied Materials Is Expanding in India
Applied is also betting on the next era of semiconductors.
The company pledged a whopping $5 billion investment in India in September, for a 10-year term. The investment will fund research and development, expansion of investments in the semiconductor supply chain, and employment expansion as India builds its semiconductor industry.
The planned relocation provides chipmakers with the added asset of another base for diversified manufacturing and capacity expansion. India aims to make a bigger presence in the global semiconductor industry, offering potential long-term opportunity to equipment suppliers.
Wall Street Is Bullish on AMAT Stock
Unlike Morgan Stanley, Goldman Sachs retained an “Outperform” call and set a $670 price estimate, with a “bake-in” argument for order visibility into 2028 and pricing considerations to back that up.
Similarly, UBS analyst Timothy Arcuri maintained an outlook of “Buy” and increased his price estimate to $695 from $675 earlier.
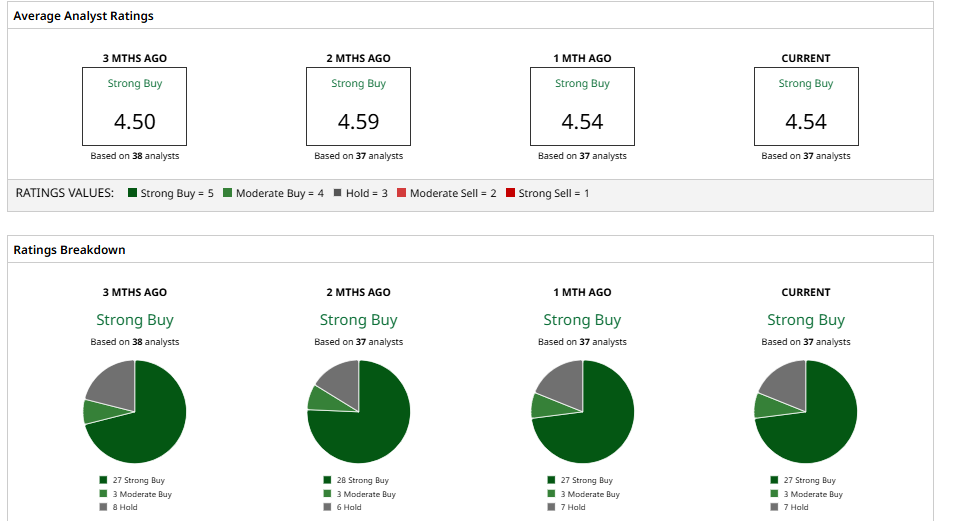
Barchart consensus data shows a “Strong Buy” rating among 37 analysts, with an average target at $651, suggesting more than 28% upside from the current level.
All told, it looks like Applied Materials is delivering strong growth, but investors are already paying a substantial premium for it.