
Irving, Texas-based McKesson Corporation (MCK) distributes pharmaceuticals, medical-surgical supplies, and health and beauty care products. With a market cap of $100.1 billion, the company also develops, implements, and supports software that facilitates the integration of data throughout the health enterprise. In addition, McKesson offers analytic, care management, and patient solutions for payers.
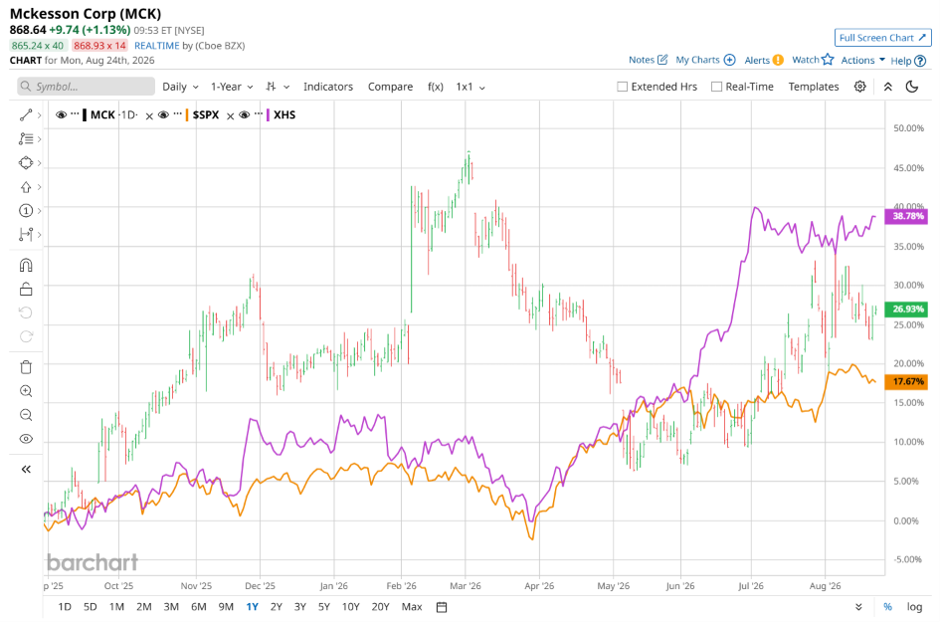
Shares of this healthcare giant have outperformed the broader market over the past year. MCK has gained 25.5% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 20.5%. However, in 2026, MCK stock is up 5.5%, compared to the SPX’s 12.1% rise on a YTD basis.
Narrowing the focus, MCK’s underperformance is apparent compared to State Street SPDR S&P Health Care Services ETF (XHS). The exchange-traded fund has gained about 40.6% over the past year. Moreover, the ETF’s 27.8% gains on a YTD basis outshine the stock’s single-digit returns over the same time frame.
MCK’s mixed performance stems from top-line operational strength clashing with segment-specific drag and changing pharmaceutical demand dynamics. While overall revenues and adjusted earnings expanded driven by double-digit volume growth in U.S. pharmaceutical distribution, specialty oncology, and high demand for GLP-1 weight-loss medications, bottom-line profitability faced periodic hits. Margin compression occurred due to lower-margin product mix shifts in primary care, softer demand in Medical-Surgical Solutions, strategic investments in technology and front-office infrastructure, and timing issues with major corporate customer contracts. Consequently, quarters with robust revenue beats were sometimes met with muted market reactions as investors weighed top-line expansion against cost pressures and decelerating GLP-1 momentum.
On Aug. 5, MCK shares rose 5.6% after reporting its Q1 results. Its adjusted EPS of $9.93 surpassed Wall Street expectations of $9.44. The company’s revenue was $105.4 billion, topping Wall Street forecasts of $104.4 billion. MCK expects full-year adjusted EPS in the range of $44.20 to $45.
For the current fiscal year, ending in March 2027, analysts expect MCK’s EPS to grow 14.2% to $44.65 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 19 analysts covering MCK stock, the consensus is a “Strong Buy.” That’s based on 14 “Strong Buy” ratings, and five “Holds.”
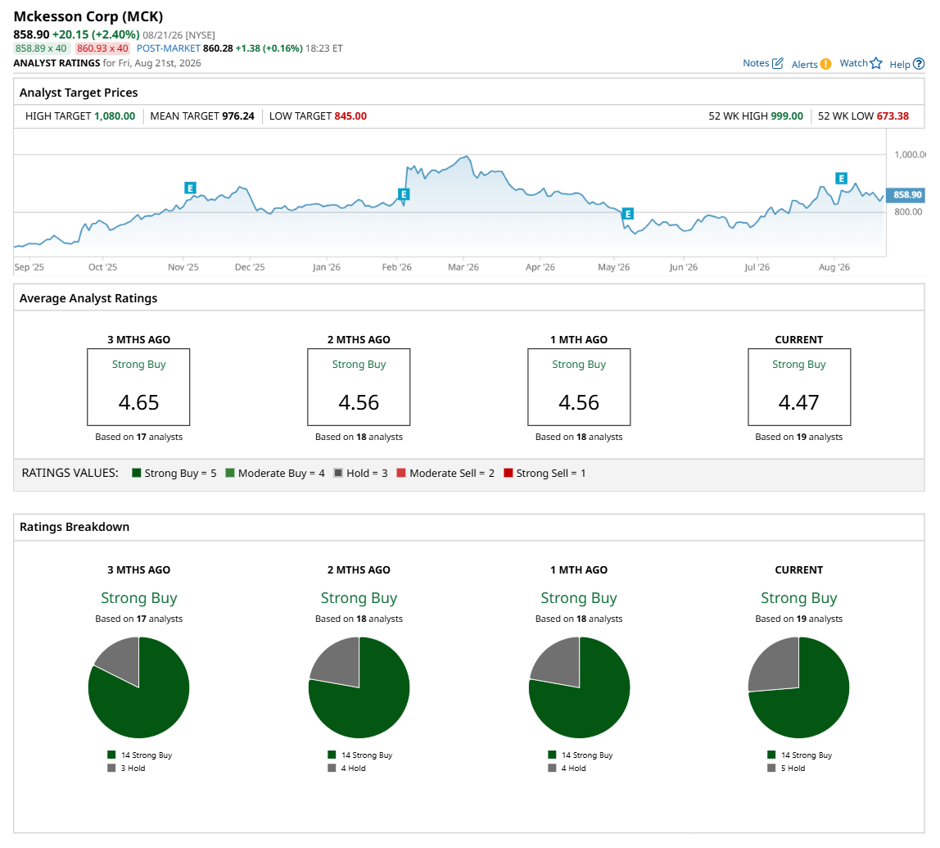
The configuration has been relatively stable over the past three months.
On Aug. 19, Barclays PLC (BCS) analyst Glen Santangelo kept an “Overweight” rating on MCK and raised the price target to $1,000, implying a potential upside of 16.4% from current levels.
The mean price target of $976.24 represents a 13.7% premium to MCK’s current price levels. The Street-high price target of $1,080 suggests an upside potential of 25.7%.