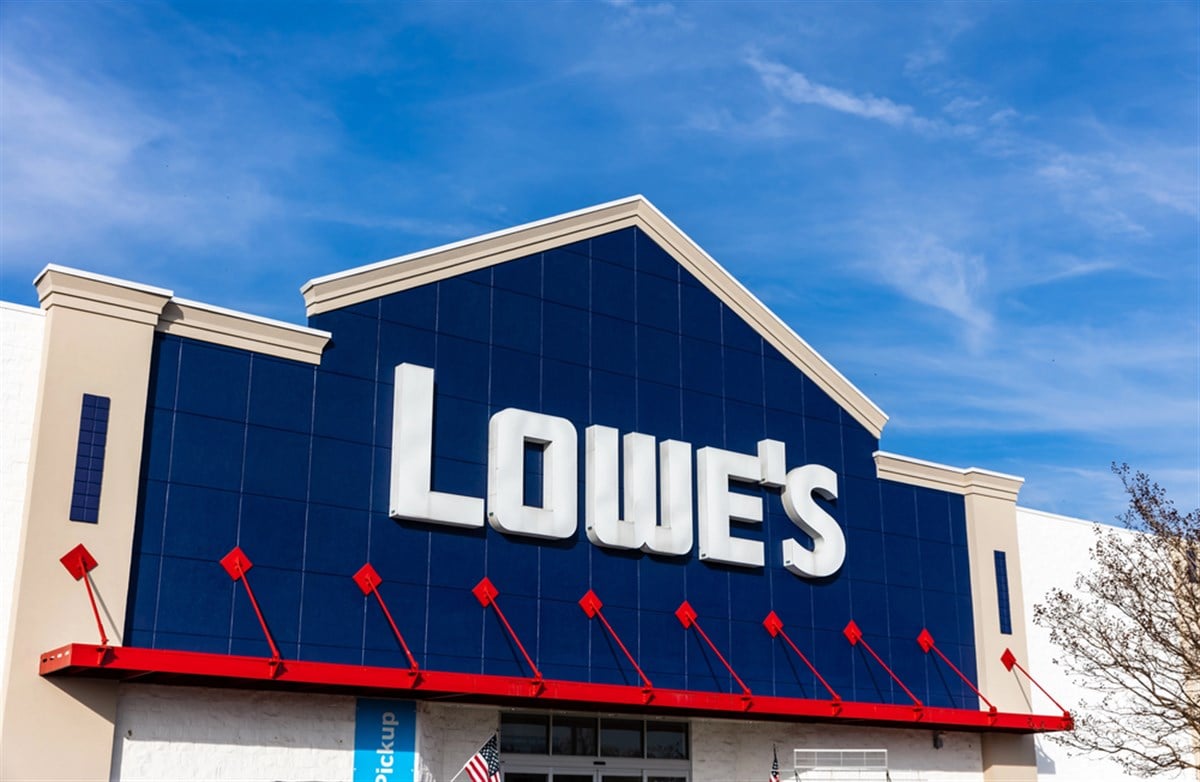
Lowe’s Companies (NYSE: LOW) price action pulled back from its October peak, providing a second-chance opportunity for investors. The opportunity is to add to positions or create new ones at a discounted price. Tepid results cause the pullback, but it is unlikely to get much deeper because of the company’s operational quality and the outlook for next year. Headwinds remain for Lowe’s and other retailers, but its earnings report and others show signs of consumer resilience and strength. Reports from Lowe’s, Home Depot (NYSE: HD), and Walmart (NYSE: WMT) show consumers shy about big-ticket projects. However, spending on smaller items is solid and underpinned by digital commerce channels.
The takeaway is that Lowe’s revenue is contracting in 2024 but less than expected, and growth is expected to resume in 2025. Revenue is expected to grow at a low-single-digit pace, and the consensus figure is likely low. Earnings growth will be more vigorous in 2025 and is critical to the capital return outlook. Lowe’s trimmed the size of its share repurchases in 2024 to better align the return with its diminished cash flow. With increasing cash flow, the company can pay down debt, reverse the shareholder deficit, and accelerate repurchase activity. The bigger opportunity is that tailwinds are expected to form in 2025 because of lower interest rates and Trump’s policies, and Lowe’s is well-positioned to benefit from them.