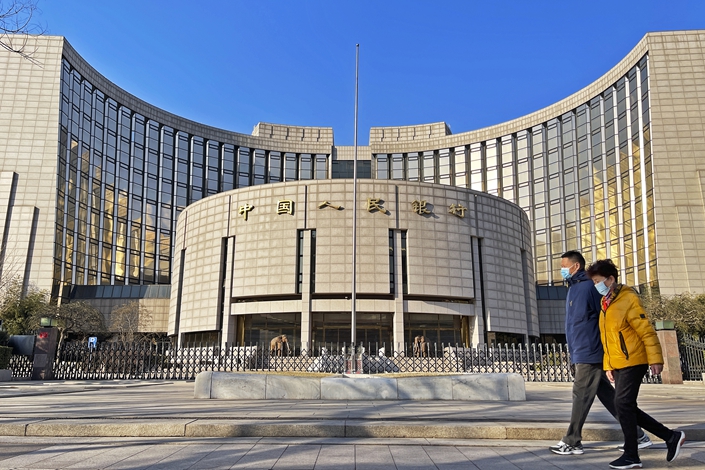
Back in 2020, a rather heated debate over whether there should be a monetization of China’s fiscal deficit put a spotlight on policy coordination between the central bank and the finance ministry. Back then, the government announced a 1 trillion yuan ($145 billion) quota for special government bonds to fight the Covid-19 pandemic. Recently, the disclosure of a more than 1 trillion yuan profit transfer made by the People’s Bank of China (PBOC) to the Ministry of Finance once again ignited a relevant discussion.
First of all, it is not surprising that the central bank has booked profits. The amount of profit the central bank has partly depends on its asset structure; while the transfer amount depends on the negotiation between the central bank and the finance ministry.