Lennar (NYSE: LEN) faces hurdles, but these are near-term issues that obscure what investors should focus on. The company is a cash-flow machine, sustaining aggressive capital returns as it builds a better business. Key takeaways from the Q3 report and conference call include lower construction costs and faster turnover, which should improve profitability and accelerate growth as the market recovers. Until then, the Even-Flow strategy is working; the company is sustaining volume despite market deterioration with incentives, gaining share as smaller operators are priced out of business.
Lennar’s capital return is substantial. Even with the risk of slowing. As it stands, the dividend yields approximately 2.63% with shares trading near long-term lows, and buybacks are reducing the share count aggressively. Down about 7% on average at quarter’s end, reductions give investors significant leverage, offsetting the impact of buybacks on the balance sheet. Balance sheet highlights include reduced cash but a sufficient pile to sustain operational health and capital returns in upcoming quarters, steady total assets and reduced debt and liabilities. Equity contracted, but mildly, given the share count reduction and subsequent addition to treasury shares.
Analysts and Institutions Give Mixed Signals - But Support Is Solid
Analysts and institutions provide conflicting signals, with a consensus of Reduce and reduced activity. However, analysts are fairly confident, with 19 covering the stock, suggesting it's an ownable stock, though September Q3 may not be the right time to get in. Meanwhile, institutional data reflects a reduction in overall activity more so than in total holdings, with trailing 12-month activity showing an approximately $600 million bearish balance, worth about 3.3% of the September market cap, and total activity petering out to under $100 million quarterly, as of mid-Q3 2026. They own more than 80% of the stock and reflect strong confidence in the long-term, cash-generating opportunity.
Short interest is a concern in the near term. Short interest isn’t astronomically high but reflects caution and hedging, at over 8% and a long-term high. The risk is that short-sellers will lean into this trade and drive to lower lows, but there is an opportunity even in that. Trading at 14x current-year expectations puts LEN stock at the high end of its range, suggesting lower share prices to come. The longer-term outlook, however, prices in an eventual housing recovery and puts this stock in the low single digits within five years, suggesting ample upside.
Bears are wrong to assume housing markets will be frozen forever. While inflation, affordability, and interest rates are undercutting demand today, interest rates will eventually fall, unleashing historically high demand. Until then, Lennar’s strategy is focused on building houses to fill the void, using affordability to drive sales and cash flow while it hones its process. Looking forward, it is well-positioned as a top-tier builder, commanding a massive market share within the mid-tier market, the largest segment of housing in America.
Lennar Whiffs in Q3 Despite Structural Improvement
Lennar’s Q3 results highlight the near-term risks. The company’s $8 billion in revenue fell 9.2% year over year and missed expectations due to lower pricing and traffic. New orders also fell by 9%, but there is good news. New orders lightly outpaced deliveries, setting the stage for sustainability in the upcoming quarter, if not growth.
Other details include reduced earnings power and cash flow, with adjusted cash flow down by a solid double-digit amount to $294 million and insufficient to cover capital returns, where the risks lie. In this scenario, the company’s balance sheet helps sustain returns, but it can’t do so forever. The upshot is that Lennar remains in a fortress-like position and can execute its strategy, including taking advantage of ultra-low stock prices. The question is when repurchases may slow, and by how much; the answer is likely in the coming year, and by half or more.
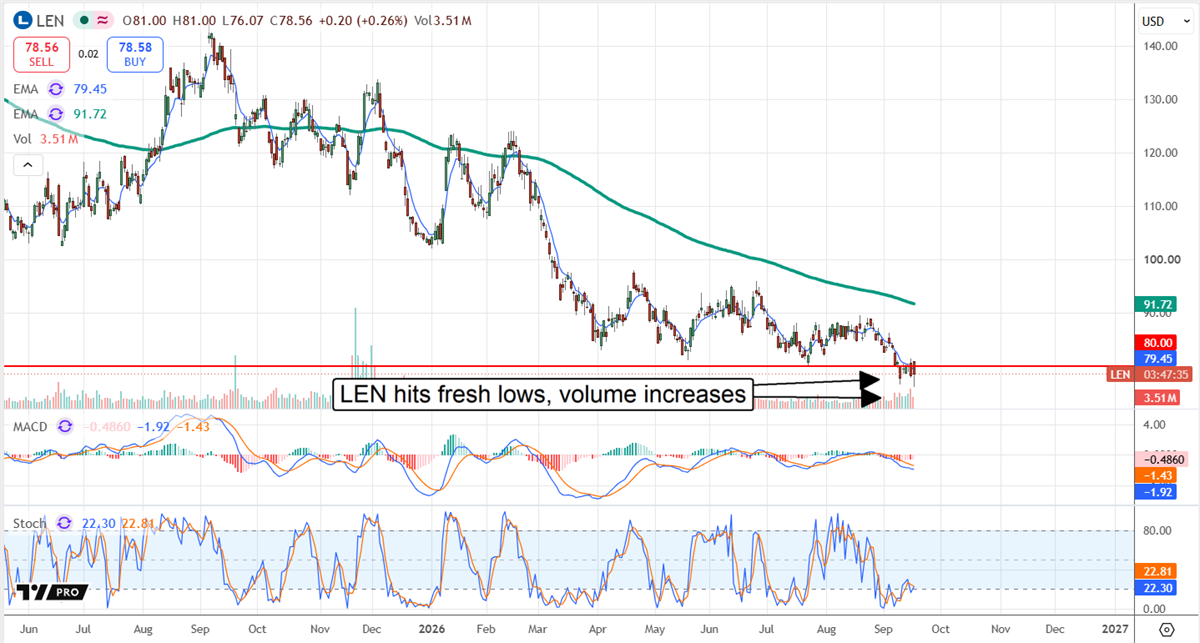
The post-release price action is as mixed as the quarterly details. Results triggered an initial pop, followed by selling and then a rebound, reflecting indecision. The technical signal is a Falling Wedge, which often signals a reversal. The best-case scenario is that Lennar is at its bottom and will begin to recover soon, but it is unlikely to advance significantly and is more likely to re-enter its trading range, which tops out near $90. The worst-case scenario is that Lennar’s support base shifts gears, starts distributing shares, and drives the market to fresh lows, which is not expected. Factors suggesting the lows are in include the volume, which increased as LEN reached its fresh lows.
The article "Lennar's Q3 Miss Hides a Stronger Operating Story Beneath the Housing Slump" first appeared on MarketBeat.