The scoreboard is the same. The prices, protections and people in charge are not.
A sports fan wants to put $20 behind a football team. What follows should not require a working knowledge of American federalism.
Yet here we are.
One platform offers a conventional sports wager. Another sells a contract that pays if the team wins. A third operates outside U.S. sportsbook licensing and advertises different prices or payment options. The products can look remarkably similar on a phone, even when the rules behind them are anything but.
Think of three overlapping lanes: state- and tribal-authorized sportsbooks, offshore operators, and prediction markets. These are not three equally authorized versions of the same service. Nor does “prediction market” automatically mean unregulated. The question is which entity offers the product, under whose authority, and with what protections.
That last part deserves more attention than the welcome bonus.
Lane One: The Licensed Sportsbook
The established U.S. model is built around authorization in particular jurisdictions, not a national permission slip.
New York, for example, publishes its licensed mobile sportsbook operators, requires mobile wagers to originate within the state and controls the permitted wagering menu. A familiar brand name does not make every product bearing that name available everywhere.
The business is enormous. The American Gaming Association’s 2026 State of the States report puts 2025 commercial sports-betting revenue at $16.89 billion, up 22.6%. That excludes tribal sportsbook revenue, including Florida’s tribal-operated mobile market. It is operator gaming revenue—not total money wagered or bottom-line profit.
The consumer advantage is accountability. Licensed operations face jurisdiction-specific requirements, and regulators provide mechanisms for complaints and responsible gambling. Indiana, for instance, has a dedicated sports-wagering complaint process; Massachusetts maintains a sports-wagering self-exclusion framework. Neither guarantees that every dispute ends in the customer’s favor.
Regulation is not insurance against losing a bet. It establishes rules for the company accepting it.
Lane Two: Offshore Sportsbooks
Offshore operators sit outside U.S. state sportsbook licensing. Some hold licenses elsewhere; the existence and scope of that oversight need checking rather than assuming.
Their commercial pitch often involves cryptocurrency banking, broader markets, higher limits or reduced-juice pricing on selected bets. Those features vary by operator. OddsTrader’s comparison of offshore and regulated sportsbooks examines those differences alongside withdrawal policies, verification requirements and consumer protections.
Price matters. On the same market with identical settlement terms, risking $105 instead of $110 to win $100 is plainly cheaper.
But price and permission are separate questions. A foreign license is not authorization to accept wagers in a particular U.S. state. A functioning deposit button is not a legal opinion.
Enforcement is not theoretical, either. In April 2026, Michigan’s Gaming Control Board announced cease-and-desist orders against 45 offshore gambling operators over the preceding four months. The action covered online casino gaming and sports wagering—not 45 sportsbooks alone. The board warned about withheld winnings, personal-data risks and the absence of protections required of Michigan licensees.
That does not establish that every offshore operator behaves identically. It does establish why comparing them only by bonus size misses the more consequential questions.
A generous price is less impressive when the withdrawal process becomes a pen-pal arrangement.
Lane Three: Prediction Markets
Prediction markets change the transaction’s packaging and, potentially, its regulatory framework.
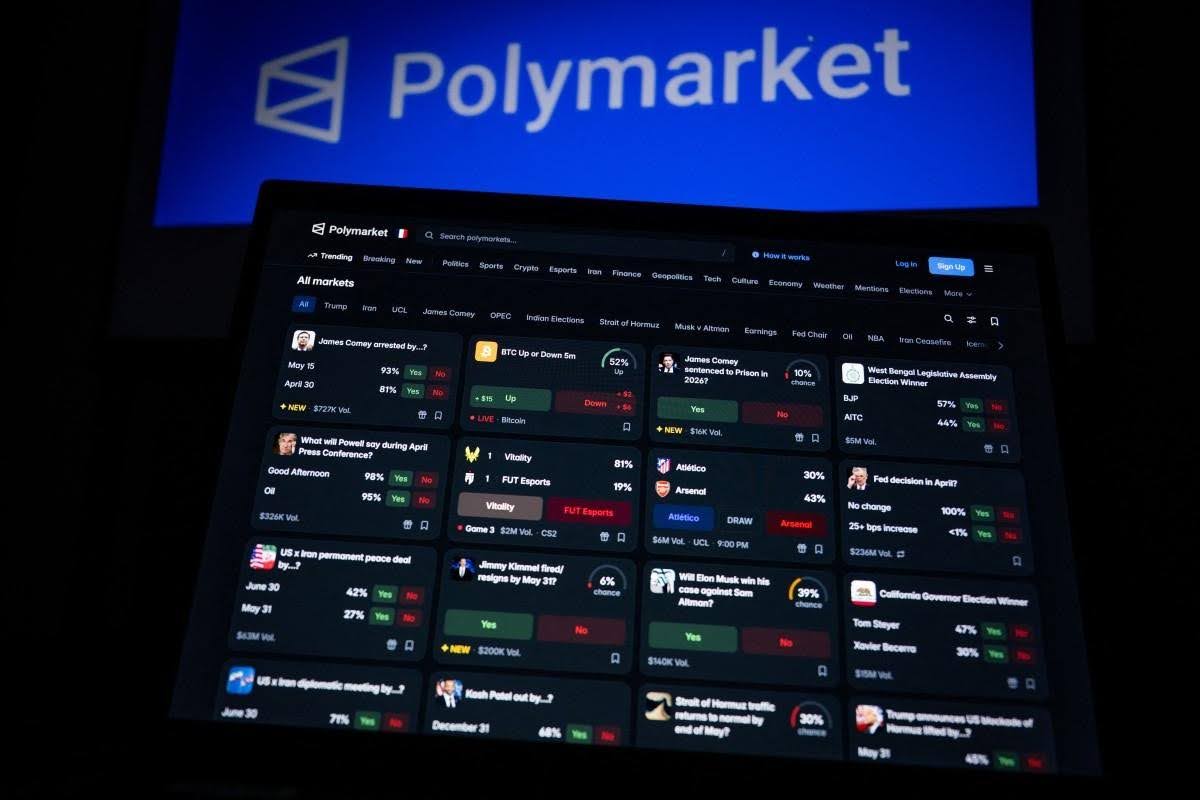
Instead of accepting conventional bookmaker odds, participants trade event contracts. The Commodity Futures Trading Commission’s explanation describes common yes-or-no contracts with a fixed payout, usually $1. On registered exchanges, participants generally trade against other market participants rather than a bookmaker directly taking the opposite position.
Consider a hypothetical contract costing 54 cents that pays $1 if a team wins. Hold it through settlement and a correct outcome produces 46 cents in profit before fees. An incorrect outcome loses the 54 cents. Calling the position a trade does not remove the downside.
The model can offer visible bids and offers and opportunities to exit before settlement. But execution depends on available liquidity, prices and fees. A screen showing an attractive price does not promise that an unlimited quantity is available there.
The category is growing beyond sports, too. Reporting carried by inkl on prediction markets expanding into Wall Street territory examines contracts tied to indexes and corporate events, alongside fresh questions about oversight. The label covers more than a different way to back Sunday’s favorite.
The Argument Is About Authority, Not Just Vocabulary
The CFTC maintains that federal commodities law gives it exclusive jurisdiction over event contracts on registered exchanges. In April, it sued Arizona, Connecticut and Illinois over their actions against those markets.
States are pushing back. On September 10, Connecticut announced nine cease-and-desist orders against prediction-market businesses, arguing that their sports products violated its gaming and consumer-protection laws. The state’s objections included age restrictions, self-exclusion and prohibited wagering categories.
Those are competing legal positions, not a dispute that can be settled by changing “bet” to “contract” in an app.
The practical conclusion is narrower than either side’s marketing: federal registration and state sportsbook licensing are different things. Readers should check the specific platform, product and jurisdiction rather than assume nationwide availability or uniform protections.
The commercial boundaries are blurring, meanwhile. inkl’s coverage of DraftKings’ push into prediction markets shows an established sportsbook business pursuing event-contract growth. Three lanes does not mean three separate sets of companies.
An Exchange Still Needs a Fair Market
Removing the traditional bookmaker from the opposite side does not remove questions about who knows what.
In an August interview with Columbia Law School, law professor Joshua Mitts discussed research with Moran Ofir that flagged more than 210,000 suspicious Polymarket bets between February 2024 and February 2026.
“There is a problem. The scope of that problem is open for debate,” Mitts said. He emphasized that the research was a statistical screen—not proof that particular traders obtained information improperly. The findings also concerned that historical Polymarket sample, not every prediction platform or sports contract.
That distinction matters. Good analysis does not turn suspicious activity into proven wrongdoing. Equally, calling a platform an exchange does not make scrutiny unnecessary.
Read the Rulebook Before the Sales Pitch
For anyone comparing these products, the sensible starting point is not “Which app looks easiest?”
Identify the operating company and verify the authorization relevant to the product and your location. Read the settlement rules, withdrawal conditions and complaint process. Compare the actual cost—including commissions or other fees—not just the biggest number in the advertisement.
Then check what controls exist for limiting spending or taking a break. A different label should not become an excuse to risk money needed elsewhere.
America’s sports-betting market is not simply choosing between old bookmakers and shiny new exchanges. It is testing competing models of pricing, access and accountability.
The football game may come down to one field goal. Choosing where to put your money should involve considerably more homework than that.




