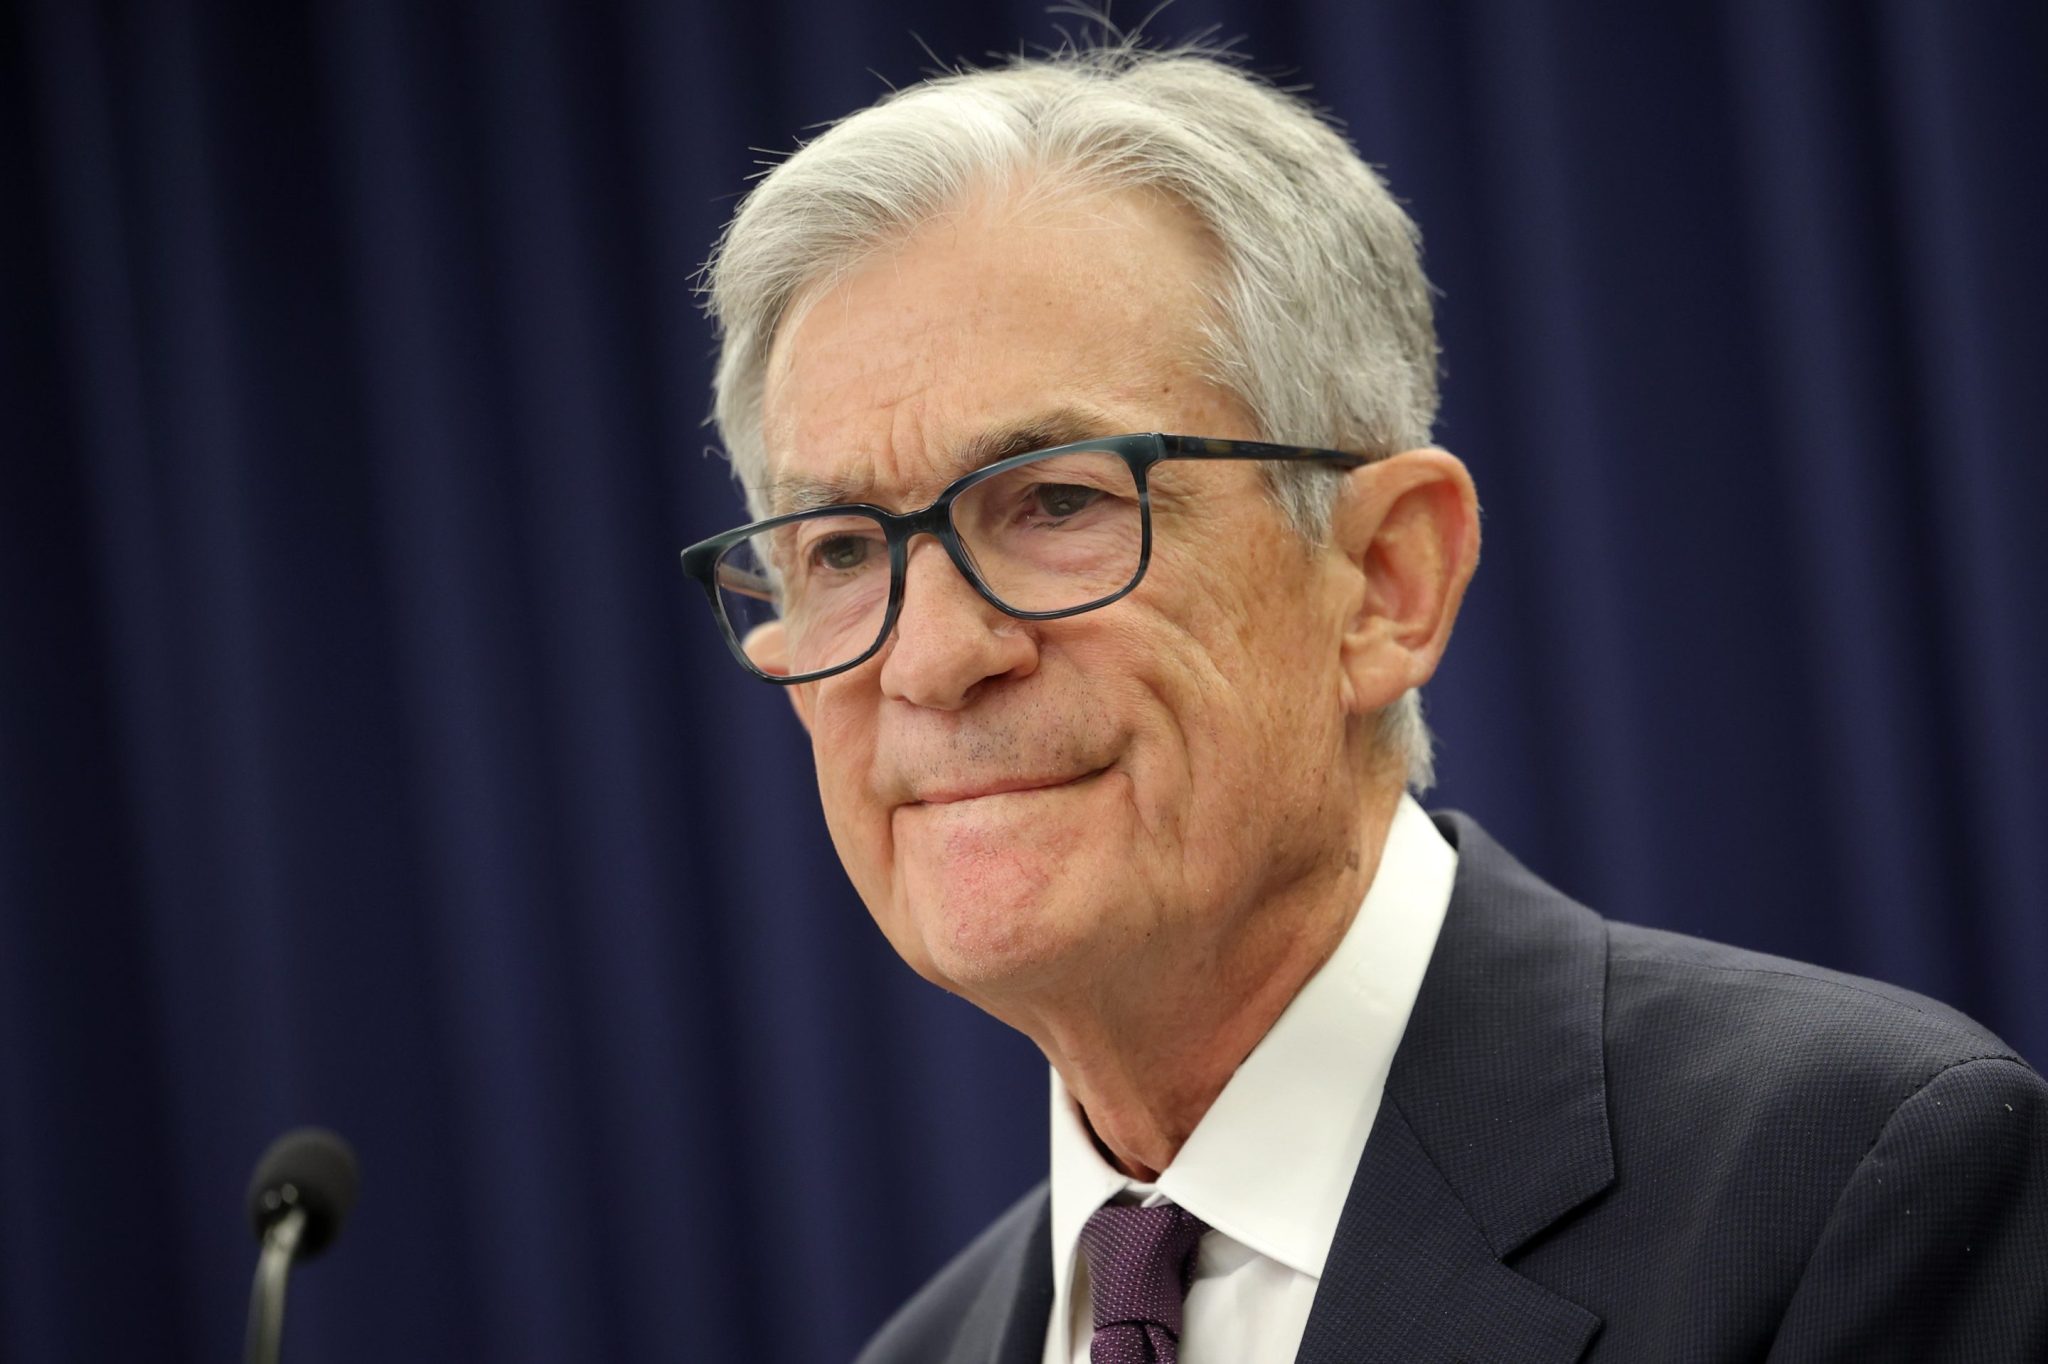
One could argue that last week’s surprisingly robust jobs report has made Jerome Powell’s job harder, as it defies the narrative economists had widely believed when it came to the slowing pace of the economy.
On the other hand, some might argue that the Fed chair’s exit from the top job at the central bank just got easier, because it may support a call for inaction by the rate-setting Federal Open Market Committee (FOMC).
Prior to Wednesday, speculators had been fairly balanced in their view of whether a 25-basis-point cut would come at the FOMC’s next meeting in March, giving it a probability of around 40%, per CME’s FedWatch barometer. But the jobs report, showing nonfarm payroll employment rose by 130,000 in January, blew those odds out of the water: They now indicate a more than 92% likelihood of a hold at the next meeting.
That inverse relationship comes from the idea that the Fed will only continue to reduce the base rate if it needs to in relation to its mandate: keeping inflation at 2% and maintaining maximum employment. The FOMC may be motivated to cut if job growth was slowing, in order to stimulate the economy. But if jobs look healthy then the Fed may not feel the need to cut.