Insulet Corporation (PODD), headquartered in Acton, Massachusetts, operates as an innovative medical device company. Valued at $10.1 billion by market cap, the company develops, manufactures, and sells insulin delivery systems for people with insulin-dependent diabetes.
Shares of this insulin infusion systems maker have considerably underperformed the broader market over the past year. PODD has declined 56% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 18.3%. In 2026, PODD stock is down 48.8%, compared to the SPX’s 11.8% rise on a YTD basis.
Narrowing the focus, PODD’s underperformance is also apparent compared to the iShares U.S. Medical Devices ETF (IHI). The exchange-traded fund has declined about 11.1% over the past year. Moreover, the ETF’s 10.1% dip on a YTD basis outshines the stock’s losses over the same time frame.
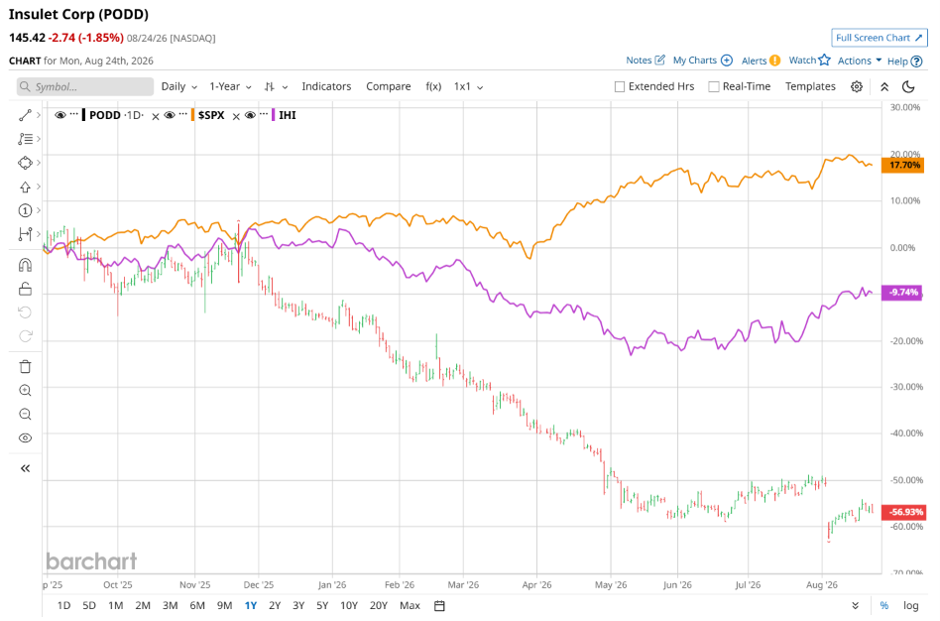
PODD underperformed as market sentiment was weighed down by commercial friction in its Type 2 diabetes segment, key adoption concerns, and intensifying competition. While top-line growth remained solid via its Omnipod 5 system, investors reacted sharply to lower-than-expected retention rates among new Type 2 users during their first 90 days of therapy, forcing a reevaluation of patient onboarding and commercial support models. Compounding these retention hiccups, broader macro anxiety over GLP-1 adoption dampening long-term insulin demand and aggressive pressure from rival automated insulin delivery providers dampened investor enthusiasm, offsetting management's progress in expanding U.S. insurance coverage and stabilizing pricing.
On Aug. 5, PODD shares nosedived over 20% after reporting its Q2 results. Its adjusted EPS of $1.66 beat Wall Street expectations of $1.44. The company’s revenue was $801.7 million, topping Wall Street forecasts of $786.8 million.
For the current fiscal year, ending in December, analysts expect PODD’s EPS to grow 31% to $6.51 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 27 analysts covering PODD stock, the consensus is a “Moderate Buy.” That’s based on 13 “Strong Buy” ratings, two “Moderate Buys,” 11 “Holds,” and one “Strong Sell.”
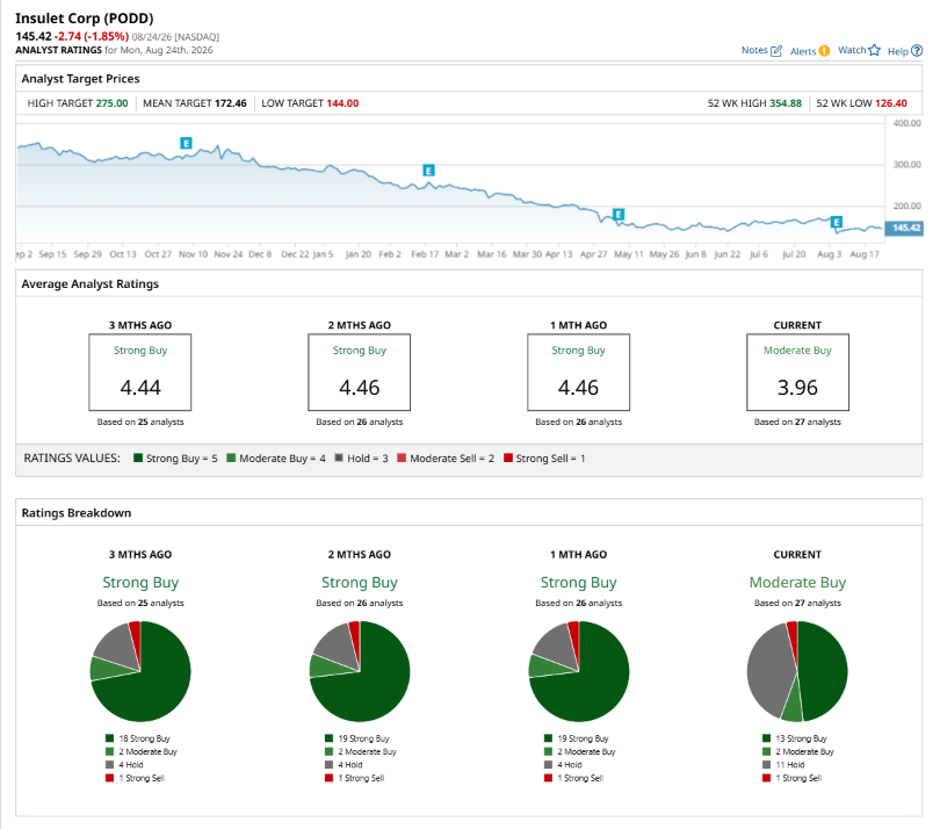
This configuration is less bullish than a month ago, with a “Strong Buy” rating overall, consisting 19 analysts suggesting a “Strong Buy.”
On Aug. 13, Citigroup Inc. (C) analyst Joanne Wuensch maintained a “Hold” rating on PODD and set a price target of $150, implying a potential upside of 3.1% from current levels.
The mean price target of $172.46 represents an 18.6% premium to PODD’s current price levels. The Street-high price target of $275 suggests an ambitious upside potential of 89.1%.