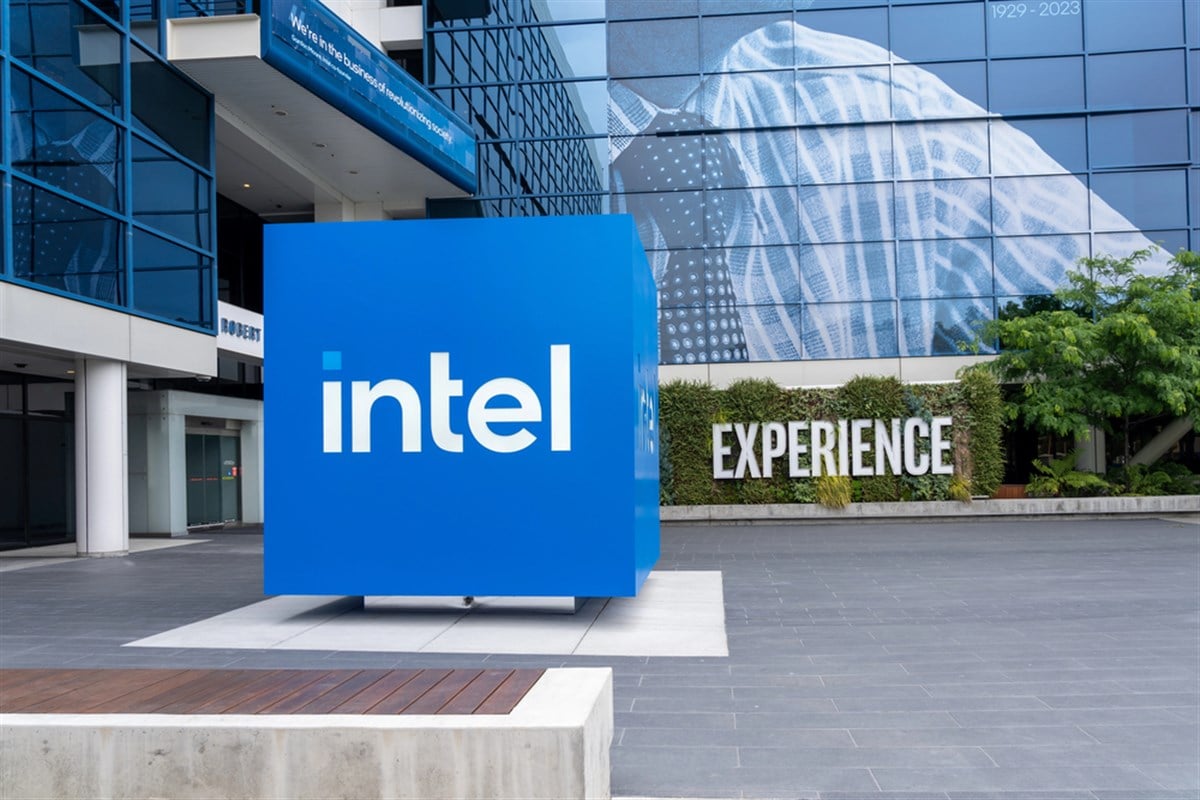
Trading near its 52-week low around $20, Intel (NASDAQ: INTC) presents a seemingly inexpensive investment in the semiconductor sector as we near the middle of 2025. This low valuation, however, clashes with Intel’s analyst community’s cautious consensus rating and a weak financial outlook following a better-than-expected first quarter. Despite exceeding Q1 estimates, Intel's forecast of breakeven adjusted earnings for Q2 triggered market concerns and amplified questions about the company's direction. Investors now face a dilemma: Is Intel's current low price and CEO Lip-Bu Tan's turnaround strategy a genuine value opportunity, or does it represent a value trap with potential for further difficulties?