
Stamford, Connecticut-based Gartner, Inc. (IT) is a global research and advisory firm serving the technology industry, with expertise spanning hardware, software, communications, and information technology. With more than 45 years of experience, Gartner helps businesses make informed decisions on critical priorities across approximately 90 countries and territories. Its insights are backed by more than 2,400 analysts, 510,000+ client interactions, 23,000+ vendor briefings, and 815,000+ vetted peer reviews.
Gartner’s market capitalization stands at about $11.3 billion, placing it in the “large-cap” category. That valuation reflects the company’s established brand, trusted research, recurring client relationships, and high-value advisory services, along with its ability to turn deep industry expertise into profitable, scalable business operations.
Despite its notable strength, IT stock has slipped 32.5% from its 52-week high of 265.85, achieved on Sept. 26, 2025. However, over the past three months, IT stock climbed 20.7%, outperforming the Dow Jones Industrials Average’s ($DOWI) 3.4% gains during the same time frame.
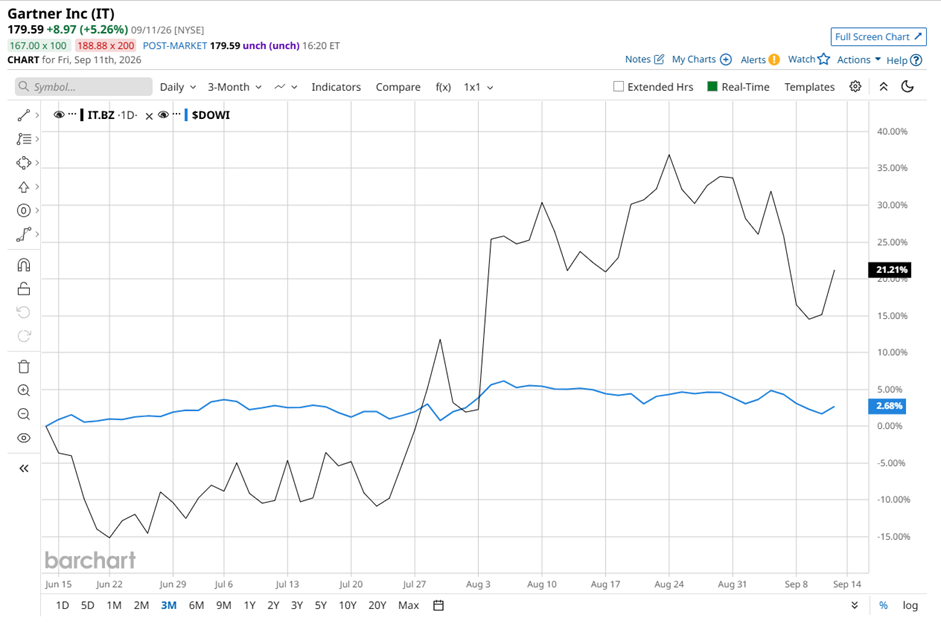
Zooming out, however, IT remains firmly in negative territory. The stock is down 28.8% on a year-to-date (YTD) basis and 25.5% over the past 52 weeks, compared with the Dow’s 9.4% YTD gain and 14% return over the past year.
The technical picture tells a similar mixed story. IT spent much of the past year trading below both its 50-day and 200-day moving averages, signaling persistent weakness. More recently, though, shares have climbed back above both averages. That shift gives investors a reason to pay closer attention, even if the broader performance still leaves plenty of ground to recover.
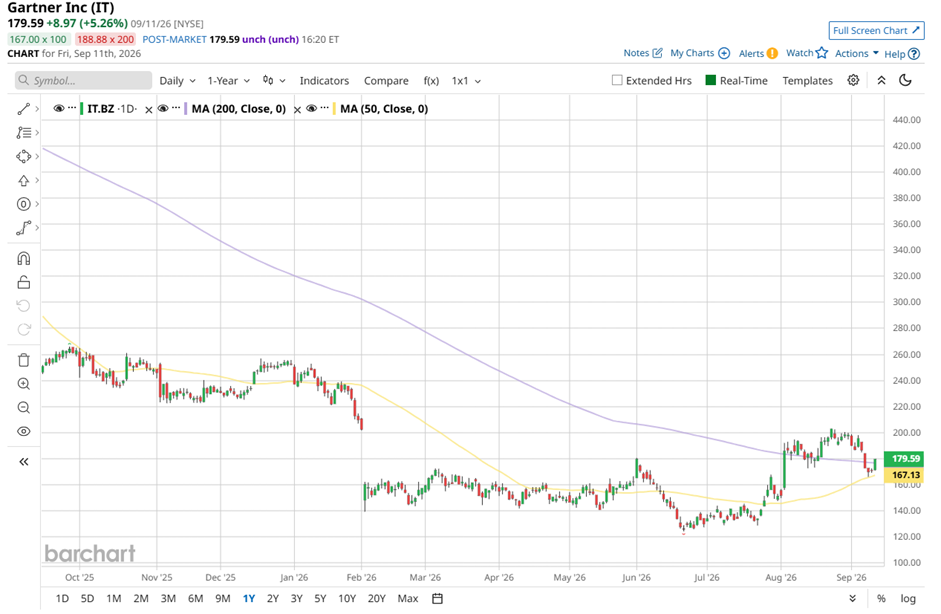
Gartner’s stock had a difficult 2025, with shares roughly cut in half as investors worried about two growing headwinds – government spending cuts and the risk that AI could eventually replace parts of Gartner’s advisory business. Slowing revenue growth and pressure on profit margins added to the concerns, while companies were also redirecting technology budgets toward AI projects and using AI-powered research tools instead of traditional consulting. Government cost-cutting efforts early in the Trump administration also weighed on renewals for Gartner’s services, creating another challenge for the company.
But zoom out to recent times, Gartner gave investors a reason to reconsider that bearish view when it reported better-than-expected Q2 FY2026 results on Aug. 4. Shares jumped 22.6% as adjusted revenue rose 2.8% year over year (YOY) to $1.68 billion, while adjusted EPS climbed 23.8% to $4.37.
The company also raised its full-year outlook, calling for at least $6.38 billion in revenue, $1.57 billion in adjusted EBITDA, $14 in adjusted EPS, and $1.19 billion in free cash flow. Gartner had also increased its share repurchase authorization by $500 million in July.
More recently, shares slipped after a Gartner survey found that only 22% of organizations had successfully scaled AI, raising concerns about near-term demand. Yet 85% plan to increase AI investment in 2026, suggesting the opportunity remains significant but uneven.
We compare Gartner’s share price performance with that of Forrester Research, Inc.’s (FORR). FORR stock rose 17.4% over the past 52 weeks and surged 44.7% in 2026, surpassing Gartner’s stock price performance.
Wall Street remains cautious on Gartner, with the stock carrying a consensus “Hold” rating among the 15 analysts currently covering it. The mean price target of $191.54 implies a 6.7% upside from current levels. The Street-high price target of $233 indicates a 29.7% upside.