Shortly before noon on Sept. 17, the directors of Tata Sons Pvt., the holding company for India’s biggest conglomerate, gathered in a sleek boardroom on the fourth floor of its headquarters for a meeting.
On one side of the long table that can accommodate 20 people sat Noel Tata, chairman of Tata Trusts, the group of charities that own 66% of the holding company that in turn controls some of India’s biggest brand names from Air India to Jaguar Land Rover. Sleeves rolled up, a seven-page document at the ready, he came prepared with a strategy to keep the company that carries his family name in private hands.
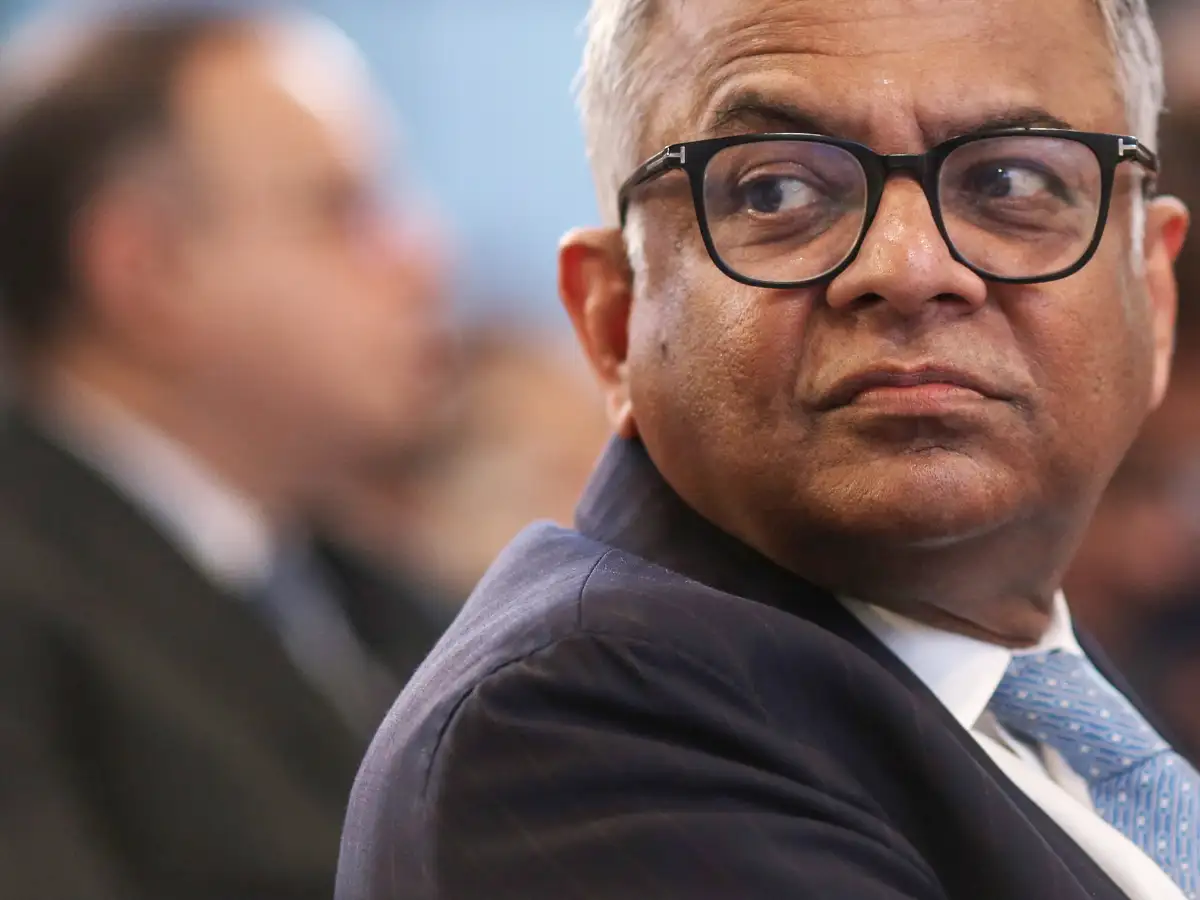
Among those facing him was Natarajan Chandrasekaran, chairman of Tata Sons, wearing a suit and a fuchsia pink tie. Chandrasekaran, known as Chandra, had helmed the closely held company for a decade, and had signaled openness to the idea of taking it public. But after his reappointment failed to secure unanimity earlier this year, he decided to bow out instead of seeking another term.
Also Read| Bombay House heads to D-Street as Tata Sons finally begins IPO prep
Yet it wasn’t Chandra’s last act. In a surprise move, Tata Sons’ directors voted 4-1 to extend his tenure for another five years and planned to move forward with steps toward a public listing — rebuffing Noel’s position and deepening a rift over control and the future of the 158-year-old conglomerate. The split has set off a civil war that’s likely to reach India’s courts and Prime Minister Narendra Modi’s government before it can be resolved. A stark battle line has been drawn, with Tata Sons describing matters as settled and Tata Trusts calling the vote to extend Chandra’s term “illegal.”
The controversy over Tata Sons and its chairman’s tenure is set to fuel uncertainty about the Indian conglomerate’s leadership at a time when it’s helming several prestige projects for India. Tata Group has plans to expand local production of Apple Inc. iPhones, and is building India’s first chipmaking facility. The group’s existing businesses are among the country’s most pervasive and renowned, including global brands like Taj Hotels, consumer staples such as Tetley tea, and software giant Tata Consultancy Services Ltd.
Tension among directors had been building before anyone arrived for the meeting at Bombay House, the group’s headquarters in Mumbai. The immediate chain of events began six days earlier, on Sept. 11, when India’s central bank rejected a petition by Tata Sons to exempt it from a regulatory path that would require a public listing. Then, the day before the board convened, one of the trusts sought — unsuccessfully — to prevent its representative director, Venu Srinivasan, from attending the meeting and voting on the board proposals, reflecting internal schisms that would soon burst into public view.
This account of the 24 hours surrounding the meeting is based on interviews with people familiar with the events, who asked not to be identified because the discussions were private. Representatives for Tata Trusts and Tata Sons did not respond to requests for comment. Srinivasan did not immediately respond to a request for comment.
For the first half hour of the pivotal meeting, board members talked about normal business affairs, such as quarterly performance, and accounts, the people familiar said. Then the discussion turned to the decision by the Reserve Bank of India and the mood shifted as the gravity of the subject matter weighed on those in attendance, these people said.
Noel argued a listing wasn’t inevitable, methodically explaining why that position could be defended, without raising his voice or displaying any hint of hostile body language, according to people familiar with the meeting.
His proposal was for the board to ask Tata Sons to go back to the regulator, seek a hearing with top officials to plead its case and then exhaust all other legal options to remain private. If those efforts failed, he said the company could seek at least three more years to comply, arguing that a listing would require extensive corporate approvals and financial preparation.
The fate of Tata Sons’ structure as a closely held entity is intertwined with the death of Ratan Tata, the group’s former patriarch and Noel’s half-brother, in October 2024. Seven months before his death, the Tata Sons board unanimously resolved to remain private. Tata Trusts publicly reiterated that decision on Thursday.
The company then spent about 200 billion rupees ($2.1 billion) paying down debt and cleaning up its balance sheet, part of an effort to shed the regulatory status that could force Tata Sons to list.
But in the aftermath of Ratan’s reign, the conglomerate has come under increasing pressure from other stakeholders, especially the central bank, to list shares of Tata Sons on the public markets. Shapoorji Pallonji Group, Tata Sons’ second-largest shareholder, has separately pushed for a listing as a way to create liquidity for its stake.
Proponents of a listing, including SP Group, argue it would improve transparency and accountability and create a mechanism for shareholders to unlock value.
However, doing so would also dilute the Trusts’ influence over the company and could restrict its ability to freely make decisions shielded from intense investor and regulatory scrutiny.
The internal debate about whether to list has also become a proxy for the power struggle between Noel Tata and Chandra over who will control the group at a critical time. UK luxury carmaker Jaguar Land Rover is recovering from a damaging cyberattack, Air India is battling record losses following a fatal crash and Tata Consultancy Services, one of the world’s biggest technology-services companies, is trying to revive growth as artificial intelligence reshapes its industry.
Also Read| Chandra is back, or is he? Noel Tata rejects board vote
In addition to Noel Tata and Chandra, those assembled in Bombay House to discuss next steps included Srinivasan, chairman emeritus of Indian motorcycle maker TVS Motor Co. and, like Noel, a Tata Trusts nominee on the Tata Sons board. Also present were former Unilever executive Harish Manwani, Tata Sons Chief Financial Officer Saurabh Agrawal, and former World Bank executive Anita Marangoly George. The three would join Srinivasan to ultimately vote against Noel’s position.