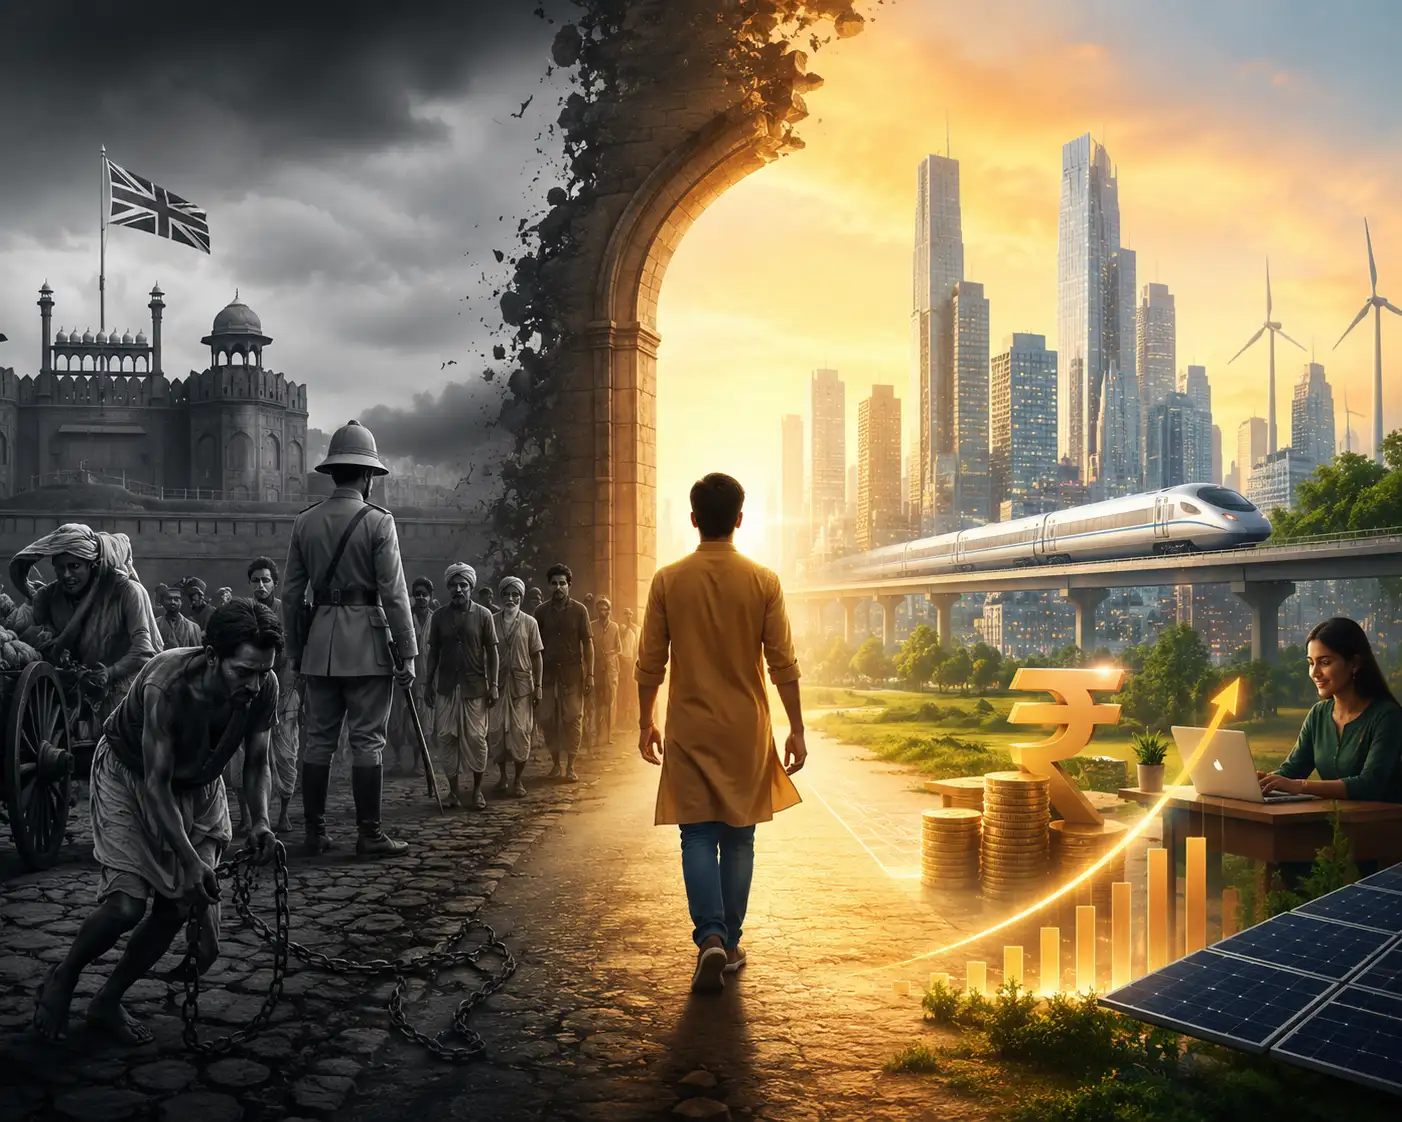
Every 15th of August, we celebrate the freedom India won in 1947, the right of a people to govern themselves. There is another freedom, quieter and still being won, worth a thought on the occasion of our Independence Day. It is the freedom of an ordinary household to provide for itself, to educate a child, own a home and retire in dignity, from its own savings. Political freedom was won for us on the fifteenth of August. Financial freedom is earned household by household, and India is relatively closer to it today than ever before. Interestingly, its foundations were laid even before India's independence as India's capital markets took root long before 1947. In 1875, a group of Indian brokers pooled their own capital to establish Asia's first stock exchange in Bombay, ahead of Tokyo, Shanghai and Hong Kong, on a street named in our own language: Dalal Street. Capital markets are not an import into India. Yet for most of the century and a half since, they were accessed by a few, while household wealth sat in gold and land.
Jan Dhan Yojana and Digital Public Infrastructure have been gamechangers. India today has internet and smartphone access few countries can match, at among the lowest data costs anywhere. Aadhar made verification quick and paperless, and UPI made money move instantly at any hour. In June this year, UPI carried 22.72 billion transactions worth Rs 28.92 lakh crore, against 2.81 billion worth Rs 5.47 lakh crore in the same month five years ago. UPI is not only a payments system. An SIP mandate can now be authorised on UPI app, and a fund purchase can be done on UPI too.