
If you’ve ever wondered why the NFL has become so pass-heavy, it comes down to simple math. You stand a better chance of gaining yardage through the air rather than grinding it out on the ground. It’s the same principle with Aurora Innovations (AUR). Yes, it’s a penny stock and no, it’s not the least bit trustworthy. You don't put your life savings into this name. Still, you don’t always ignore it.
AUR stock isn’t going to make most investors comfortable; let’s just be real. Currently, it features a 40% Sell rating by the Barchart Technical Opinion indicator. I would propose to you that this is the least of its problems. Just yesterday, Aurora lost more than 12% of market value. Since its introduction as a publicly traded security — delivered via a special purpose acquisition company, no less — the ticker has tanked nearly 47%.
To be fair, Aurora stock has also enjoyed positive momentum recently, sparked by optimistic commercial targets. Analysts are also looking at strong revenue growth, which helps explain the Moderate Buy consensus. But what continues to worry investors is the ongoing cash burn, which has served to cap enthusiasm. In some cases, as Monday’s session showed, those concerns can take front and center stage.
However, contrarians may wonder if the present malaise may offer a longshot opportunity in AUR stock. You’re all thinking it; now let’s talk about it.
Why the Quick Answer for AUR Stock is “No”
To spare you the suspense, the answer to the above question is “no.” I don’t think you’re going to find any financial expert that’s going to recommend additional research to this idea. Bluntly, the reason is that the math doesn’t check out.
Let’s consider, as a benchmark ambitious goal, the 6/7 bull call spread expiring Nov. 20. Rationally speaking, monthly options chains typically offer greater diversity of strike selections and thus tend to offer more flexibility for debit-side options traders. Since the October monthly is only three weeks away, the November monthly arguably makes more sense.
Further, on this expiration date, the $7 second-leg strike is the lowest price among vertical spreads that offers positive asymmetry (a payout greater than 100%). Here, you would be risking $30 for the chance to profit $70, a payout of over 233%. That’s very attractive — but for the modest probability of profit of 38.8%.
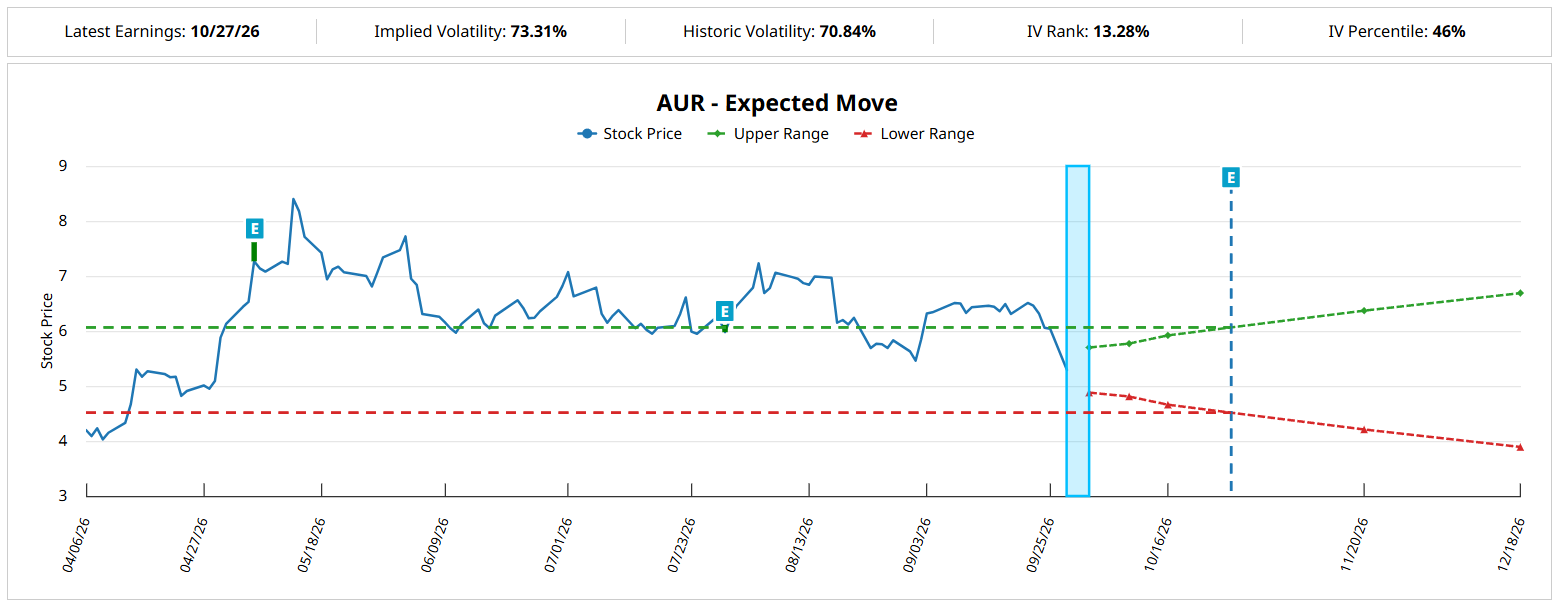
That figure refers to the chance of Aurora stock of triggering the $6.30 breakeven price on expiration. It gets worse. If you reverse-engineer Barchart’s Expected Move calculator, the odds of AUR triggering the $7 strike on Nov. 20 sits at only 15.68%.
In fact, if you really want to get technical, you’ll notice that the “mass” of probability distribution predominantly sits south of the current spot price ($5.29) while featuring a long-tail skew north of spot. Basically, this means that while upside price targets are possible, downside targets are more probable.
As the 15.68% figure demonstrates, you’re more likely to lose than to win. And even when you do win, the payout isn’t big enough to justify the trade. So, that’s why you should avoid AUR stock. Since Wall Street isn’t about to just hand you an extra payout to take the same risk, it would be silly to accept the wager.
Realistically, since the payout is unlikely to change, the only thing that can make this trade remotely worthwhile is if the probability did.
Looking at an Alternate Reality
Whenever we make a forecast of future events, we have to presuppose a framework in order to move the argument along. That’s philosophically unavoidable because nobody — no institution, no person, no model — knows the future with absolute certainty.
That brings up a side point about Monte Carlo simulations. There’s a common misconception that you just run advanced simulations and that the computer will give you an answer. No, a simulation is only as good as the parameters you feed it. So, the question isn’t so much about the forecasting as it is whether the assumptions fed into it are justified.
What’s interesting is that if we break the price history of AUR stock into Markov states comprised of 10-week sequences, we can determine that AUR is currently in a bearish state. Specifically, in the last 10 weeks, the ticker printed four up weeks, leading to a downward slope. Put another way, 60% of the unit-wise volume within the defined period was net negative.
This bearish Markov state historically generates a particular set of likely probabilities that are different from a random walk distribution. Using this framework, I calculate the odds of AUR stock terminating at $7 on Nov. 20 at 28%. Granted, that’s not much of a difference from the earlier probabilities — we’re still talking about a statistically terrible idea.
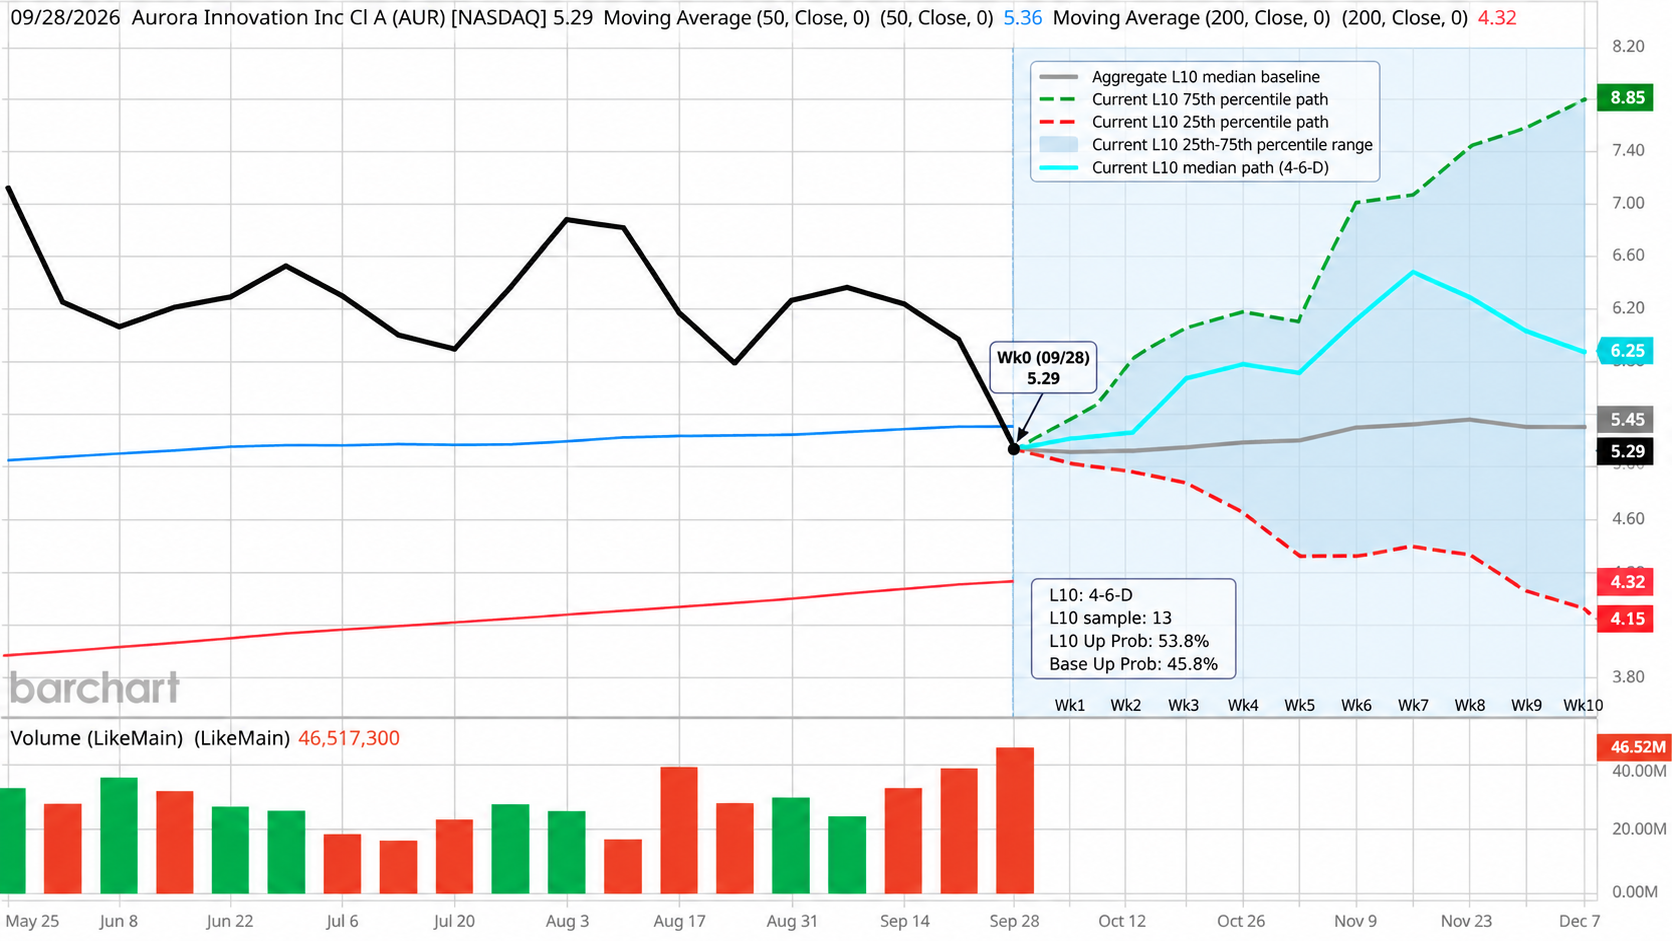
However, if we apply recency bias to the Markov chain analysis so that the point of analysis starts in January 2024, we then get a far different probability — perhaps due to a broader sentiment regime shift that occurred in the last roughly three years.
Under this favorable bias, the odds of hitting $7 on expiration improve to between 46.2% to 53.8%. In that case, the 6/7 bull spread starts to make more sense.
Aurora Stock Remains a Perplexing Idea
Should you then consider gambling on AUR stock? When you consider the overall picture, the answer still continues to be that Aurora is a highly speculative idea. It really should be treated as a gamble.
However, when you look at the math, there’s a reason why extreme contrarians are tempted by the offer. Yes, the math does show that Aurora stock is an imprudent idea. But that’s true if the parameters fed into the standard Wall Street pricing mechanism turn out to be accurate.
But where the temptation reaches its zenith is the meta question: what if the parameters themselves warrant a change of assumptions? Please hear me out: I do not know which parameters are justified. Nevertheless, it cannot be avoided that the same math on different parameters yield different conclusions.
Therefore, under certain conditions, it may be better to pass the ball if indeed the decision has been made to conduct an offensive play rather than a defensive strategy.
Ultimately, then, Aurora stock isn’t a matter of deciding if it’s a risky trade or not. It’s risky no matter how you look at it. But the relative risk is where the dispute lies — and AUR bulls are not without defense.