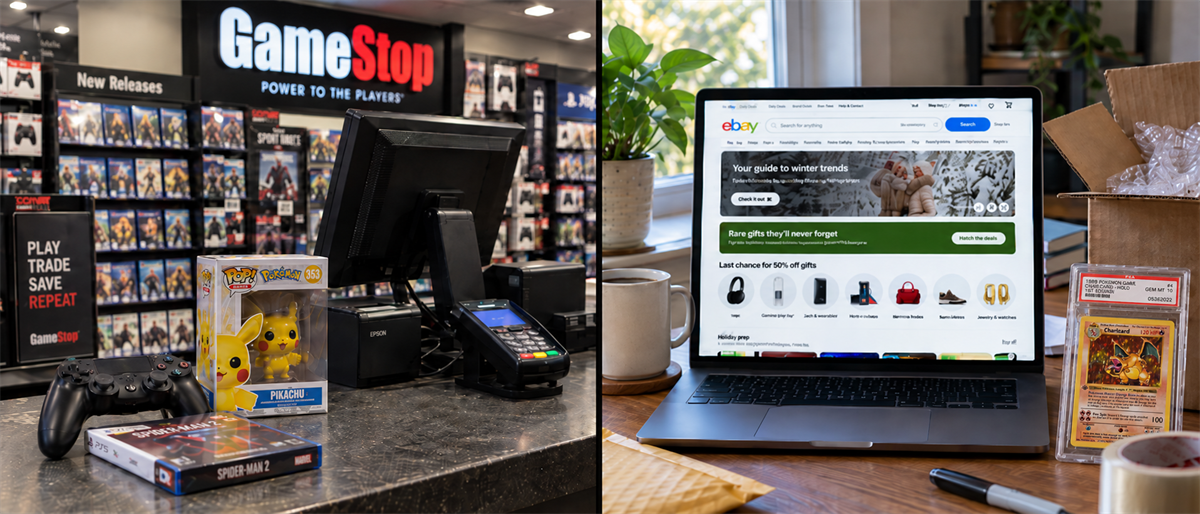
GameStop’s (NYSE: GME) Q2 2026 results offer intriguing details suggesting it may be time to take the stock seriously. Maybe. The critical details lie within the Collectibles segment, which has long been the company’s growth focus. It grew 57% year over year to 45.1% of sales and is expected to continue growing. It also contributed to the company’s profitability, but it may not be enough to keep the market in gear.
As good as the news is, Collectibles are still less than 50% of the business; the remaining segments are in sharp contraction, and there aren’t many other reasons to want to own the stock. Collectibles are unlikely to ever eclipse the strong games and hardware business, raising the question of what you're really getting. As it stands, the company increasingly looks like a collectibles retailer, a cash-rich holding company, and an eBay (NASDAQ: EBAY) investor, while eBay remains by far the cleaner operating business. eBay is growing, producing steadier profits, and, more importantly, generating cash in a way that supports capital returns.