Norwalk, Connecticut-based EMCOR Group, Inc. (EME) provides electrical and mechanical construction and facilities, building, and industrial services. Valued at $32.6 billion by market cap, the company specializes in the design, installation, integration, and start-up of distribution systems for electrical power, lighting systems, and low-voltage systems such as fire and security alarms, voice and data communication, ventilation, and plumbing and piping systems.
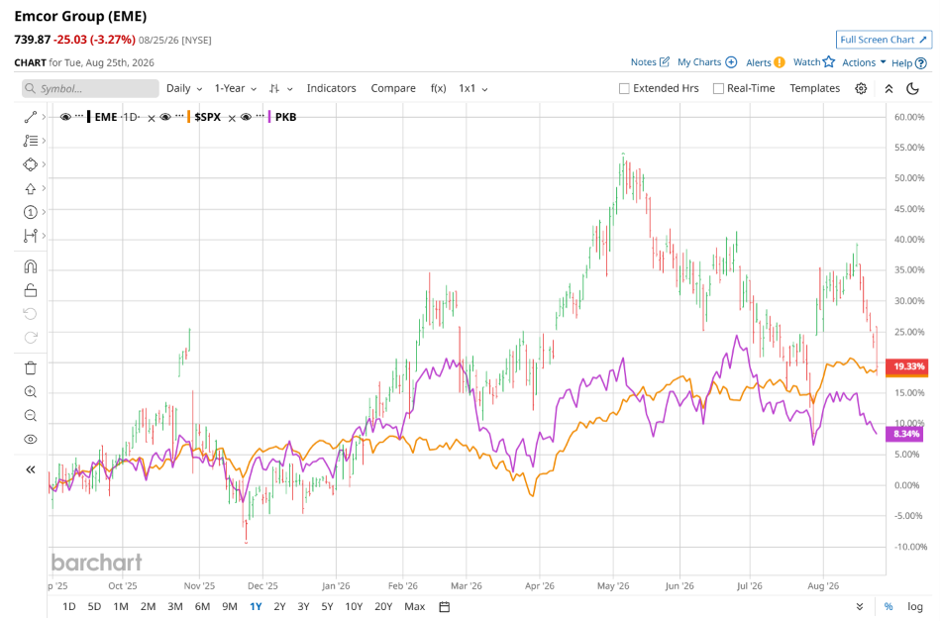
Shares of this leading provider of electrical and mechanical construction and facilities services have outperformed the broader market over the past year. EME has gained 21.5% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 18.7%. In 2026, EME stock is up 20.9%, surpassing the SPX’s 12.2% gains on a YTD basis.
Zooming in further, EME’s outperformance looks more pronounced compared to the Invesco Building & Construction ETF (PKB). The exchange-traded fund has gained about 8.4% over the past year. Moreover, EME’s double-digit gains on a YTD basis outshine the ETF’s 7.1% returns over the same time frame.
EME outperformed on broad-based strength in data centers, institutional, and industrial projects, supported by strong execution on complex, mission-critical work. Electrical and Mechanical Construction were standouts, with network & communications revenue up sharply and efficiency gains from prefabrication and virtual design. Institutional and commercial projects also accelerated, while Building Services grew on HVAC retrofits and controls, and Industrial Services rose on turnaround and petrochemical activity. Record Remaining Performance Obligations (RPOs) and recent acquisitions in Electrical Construction provide strong visibility.
On Jul. 30, EME shares skyrocketed 19.3% after reporting its Q2 results. Its EPS of $9.06 beat Wall Street expectations of $7.23. The company’s revenue was $5.2 billion, topping Wall Street forecasts of $4.7 billion. EME expects full-year EPS to be $32 to $33.25, and revenue in the range of $20 billion to $20.5 billion.
For the current fiscal year, ending in December, analysts expect EME’s EPS to grow 27.7% to $33.04 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in three of the last four quarters while missing the forecast on another occasion.
Among the 11 analysts covering EME stock, the consensus is a “Strong Buy.” That’s based on eight “Strong Buy” ratings, and three “Holds.”
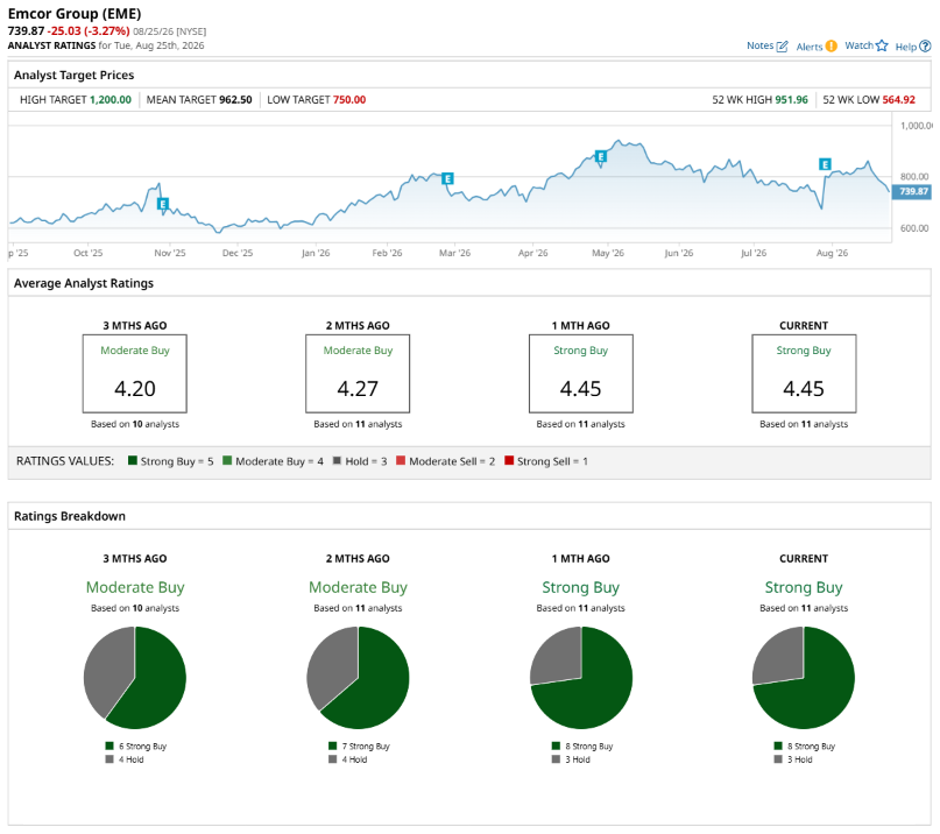
This configuration is more bullish than two months ago, with a “Moderate Buy” rating overall, consisting seven analysts suggesting a “Strong Buy.”
On Jul. 30, Adam Bubes from The Goldman Sachs Group, Inc. (GS) maintained a “Hold” rating on EME, with a price target of $885, implying a potential upside of 19.6% from current levels.
The mean price target of $962.50 represents a 30.1% premium to EME’s current price levels. The Street-high price target of $1,200 suggests a notable upside potential of 62.2%.