
SpaceX (SPCX) shareholders have had a positive week, with Starship Flight 14 recently reaching orbit and deploying 26 Starlink V3 satellites, moving SpaceX closer to launching satellites in large numbers and ultimately toward full reusability. TD Cowen initiated coverage of SPCX stock shortly after the flight, assigning a “Buy” rating and a $200 price target.
The reaction from the market was rather moderate, as SpaceX gained almost 3% on Sept. 29 and closed at $149.24 per share. This may be due to the ongoing debate regarding the newly public company. While the operational performance and revenue growth of SpaceX is impressive, the stock already commands a significant premium in terms of valuation.
About SpaceX Stock
SpaceX is a provider of launch services, satellite connectivity, and infrastructure for artificial intelligence (AI). The company is most well-known for its Falcon rocket series, Starship launch vehicle, and Starlink satellites. The company is valued at approximately $1.95 trillion market capitalization, making SpaceX one of the biggest publicly traded companies in the world.
As of Oct. 1, SPCX stock closed at $148.07. Shares currently trade about 52% higher than the 52-week low of $104.83 but about 30% lower than the 52-week high of $225.64. Over the last five trading sessions, shares of SpaceX are up by about 7%.
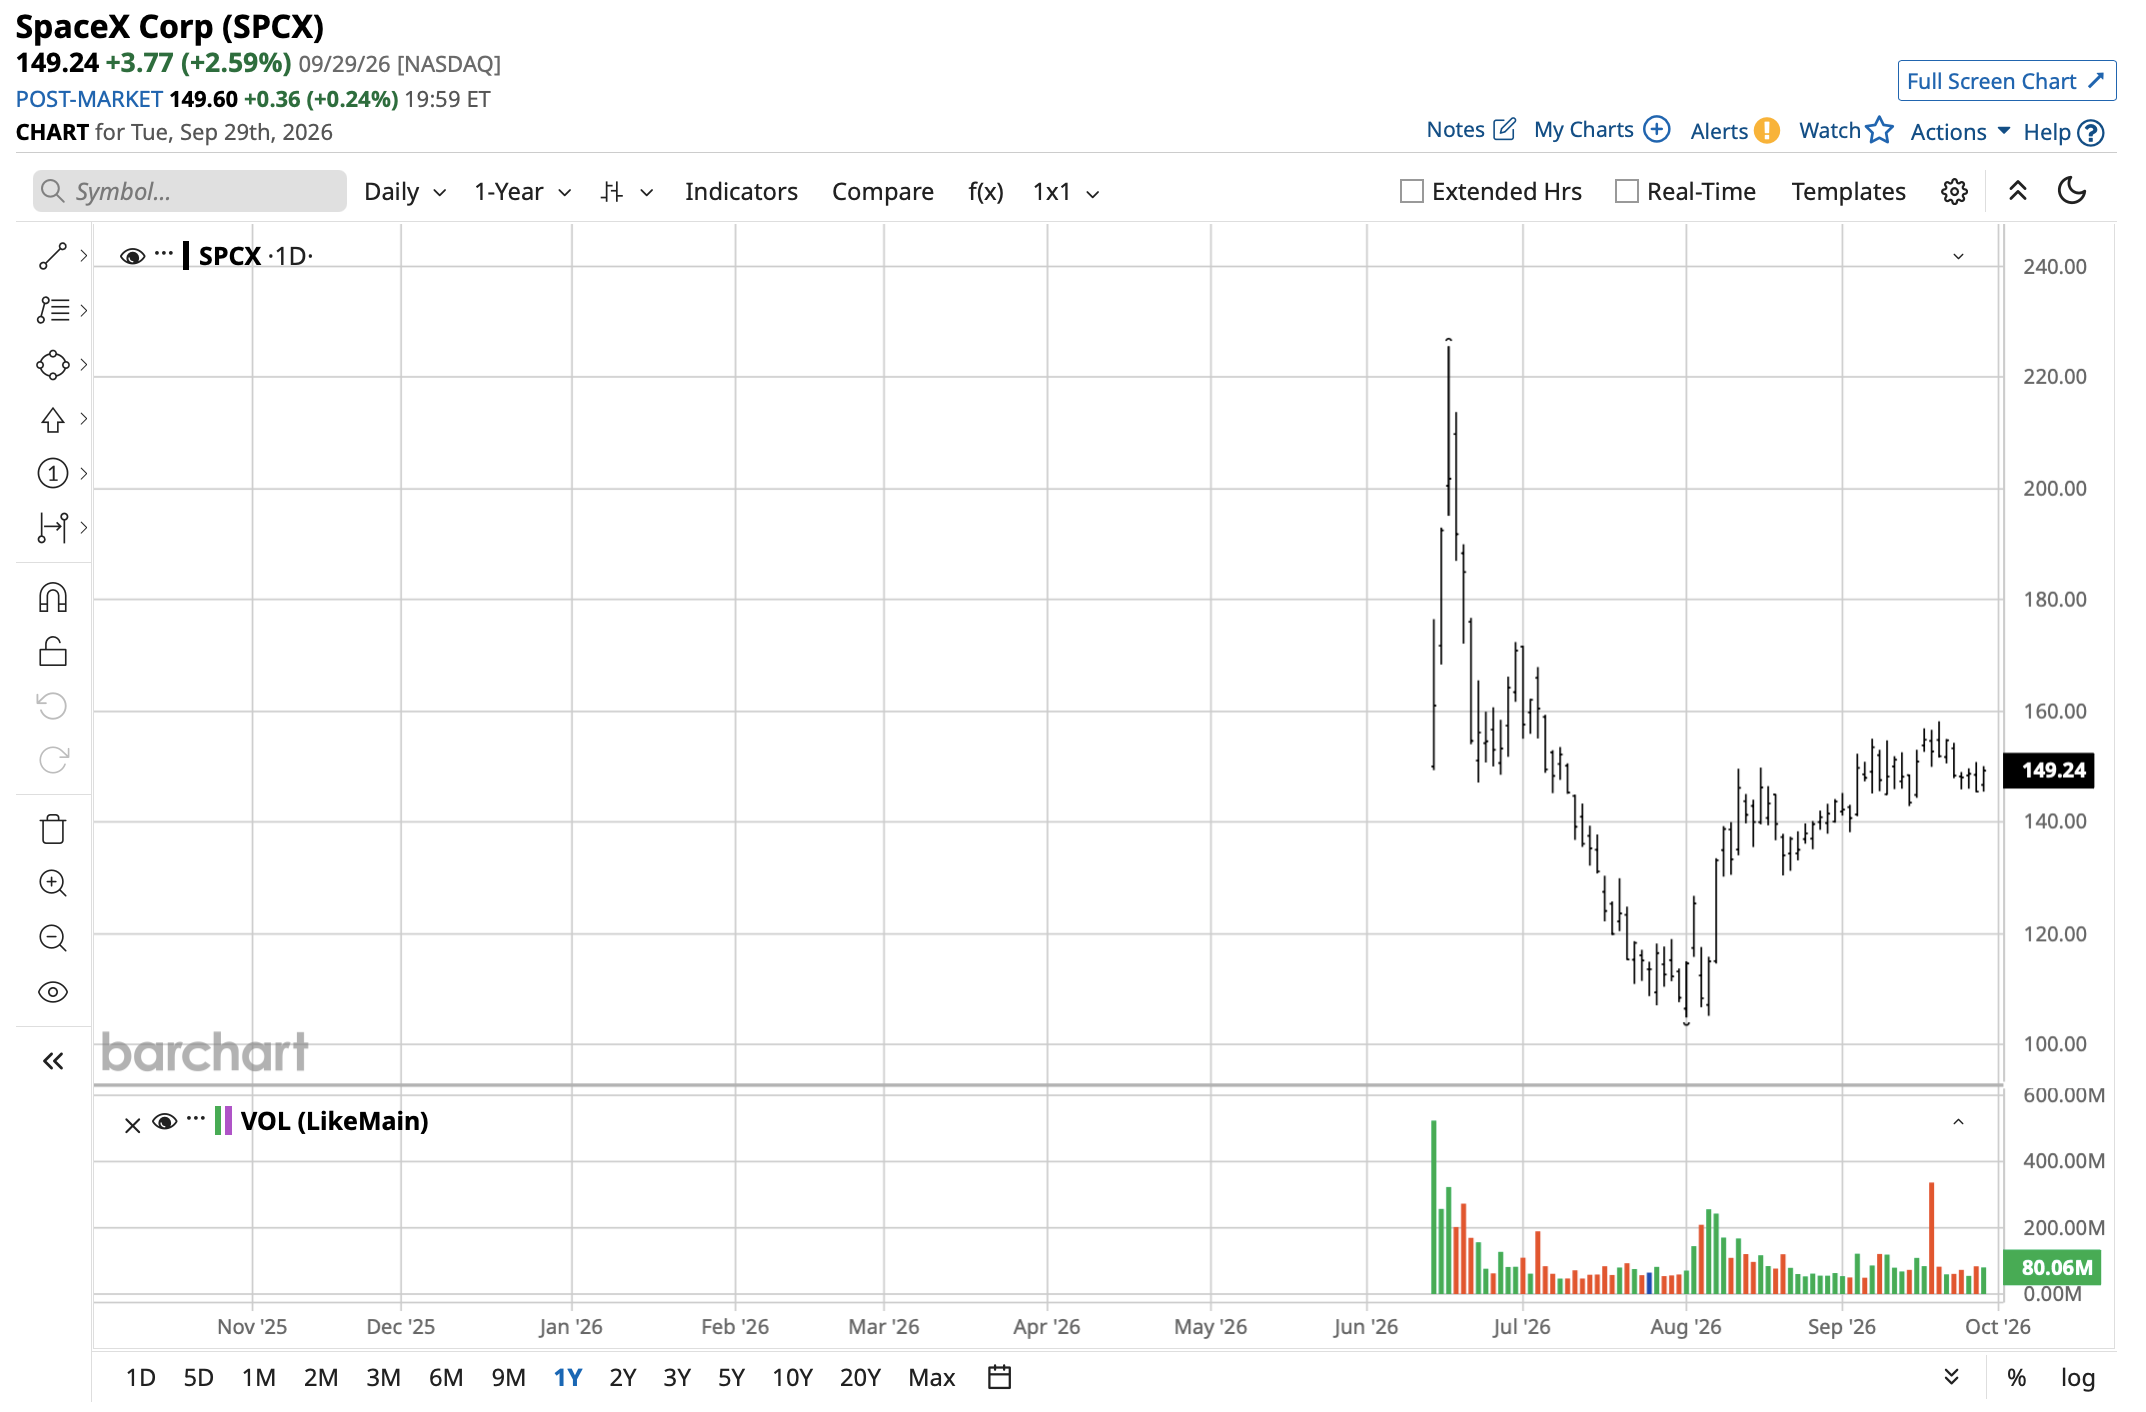
However, the valuation is not easy, as SpaceX is currently unprofitable on a GAAP basis, making the price-to-earnings (P/E) ratio irrelevant. Meanwhile, SpaceX has a price-to-sales (P/S) ratio of approximately 106.4 times. That is an extremely high multiple indicating that investors have already priced in many years of fast growth ahead. In this sense, the valuation also increases the significance of SpaceX continuing to successfully execute its plans involving Starship, Starlink, and its emerging AI projects.
SpaceX Reports Robust Q2 Revenue Growth
SpaceX reported solid second-quarter results, providing support for its growth story. In Q2 2026, the company generated revenue of $7.8 billion, up 92% year-over-year (YOY) from $4.1 billion a year ago. Net losses narrowed to $541 million from approximately $1 billion a year earlier.
SpaceX reported even more impressive growth in its adjusted EBITDA, which surged 191% YOY to $3.5 billion. The company made solid progress in its Connectivity segment as well, as revenue from the segment increased 66% and operating income grew 79%, driven by a “doubling of Starlink Subscribers and continued momentum in Enterprise & Government.”
AI operations are becoming an important component of SpaceX's strategy. The company signed multiple Cloud Services Agreements in Q2, representing $14.1 billion in contracted sales. Moreover, SpaceX announced the acquisition of Cursor for $60 billion and the release of Grok 4.5 in July. SpaceX secured more than $6 billion of multiyear U.S. government contracts for Starshield as well.
Importantly, the company's balance sheet provides enough financial resources to implement all of these projects. SpaceX ended Q2 with cash, cash equivalents, and marketable securities of $100 billion and a backlog of $47.5 billion.
The latest flight of Starship is yet another step in the right direction. Flight 14 reached orbit and successfully deployed 26 Starlink V3 satellites. Although an engine issue shortened the mission, the fact that the mission ended successfully with payload deployment brings Starship closer to becoming a part of SpaceX's commercial launch infrastructure.
What Do Analysts Expect from SpaceX Stock?
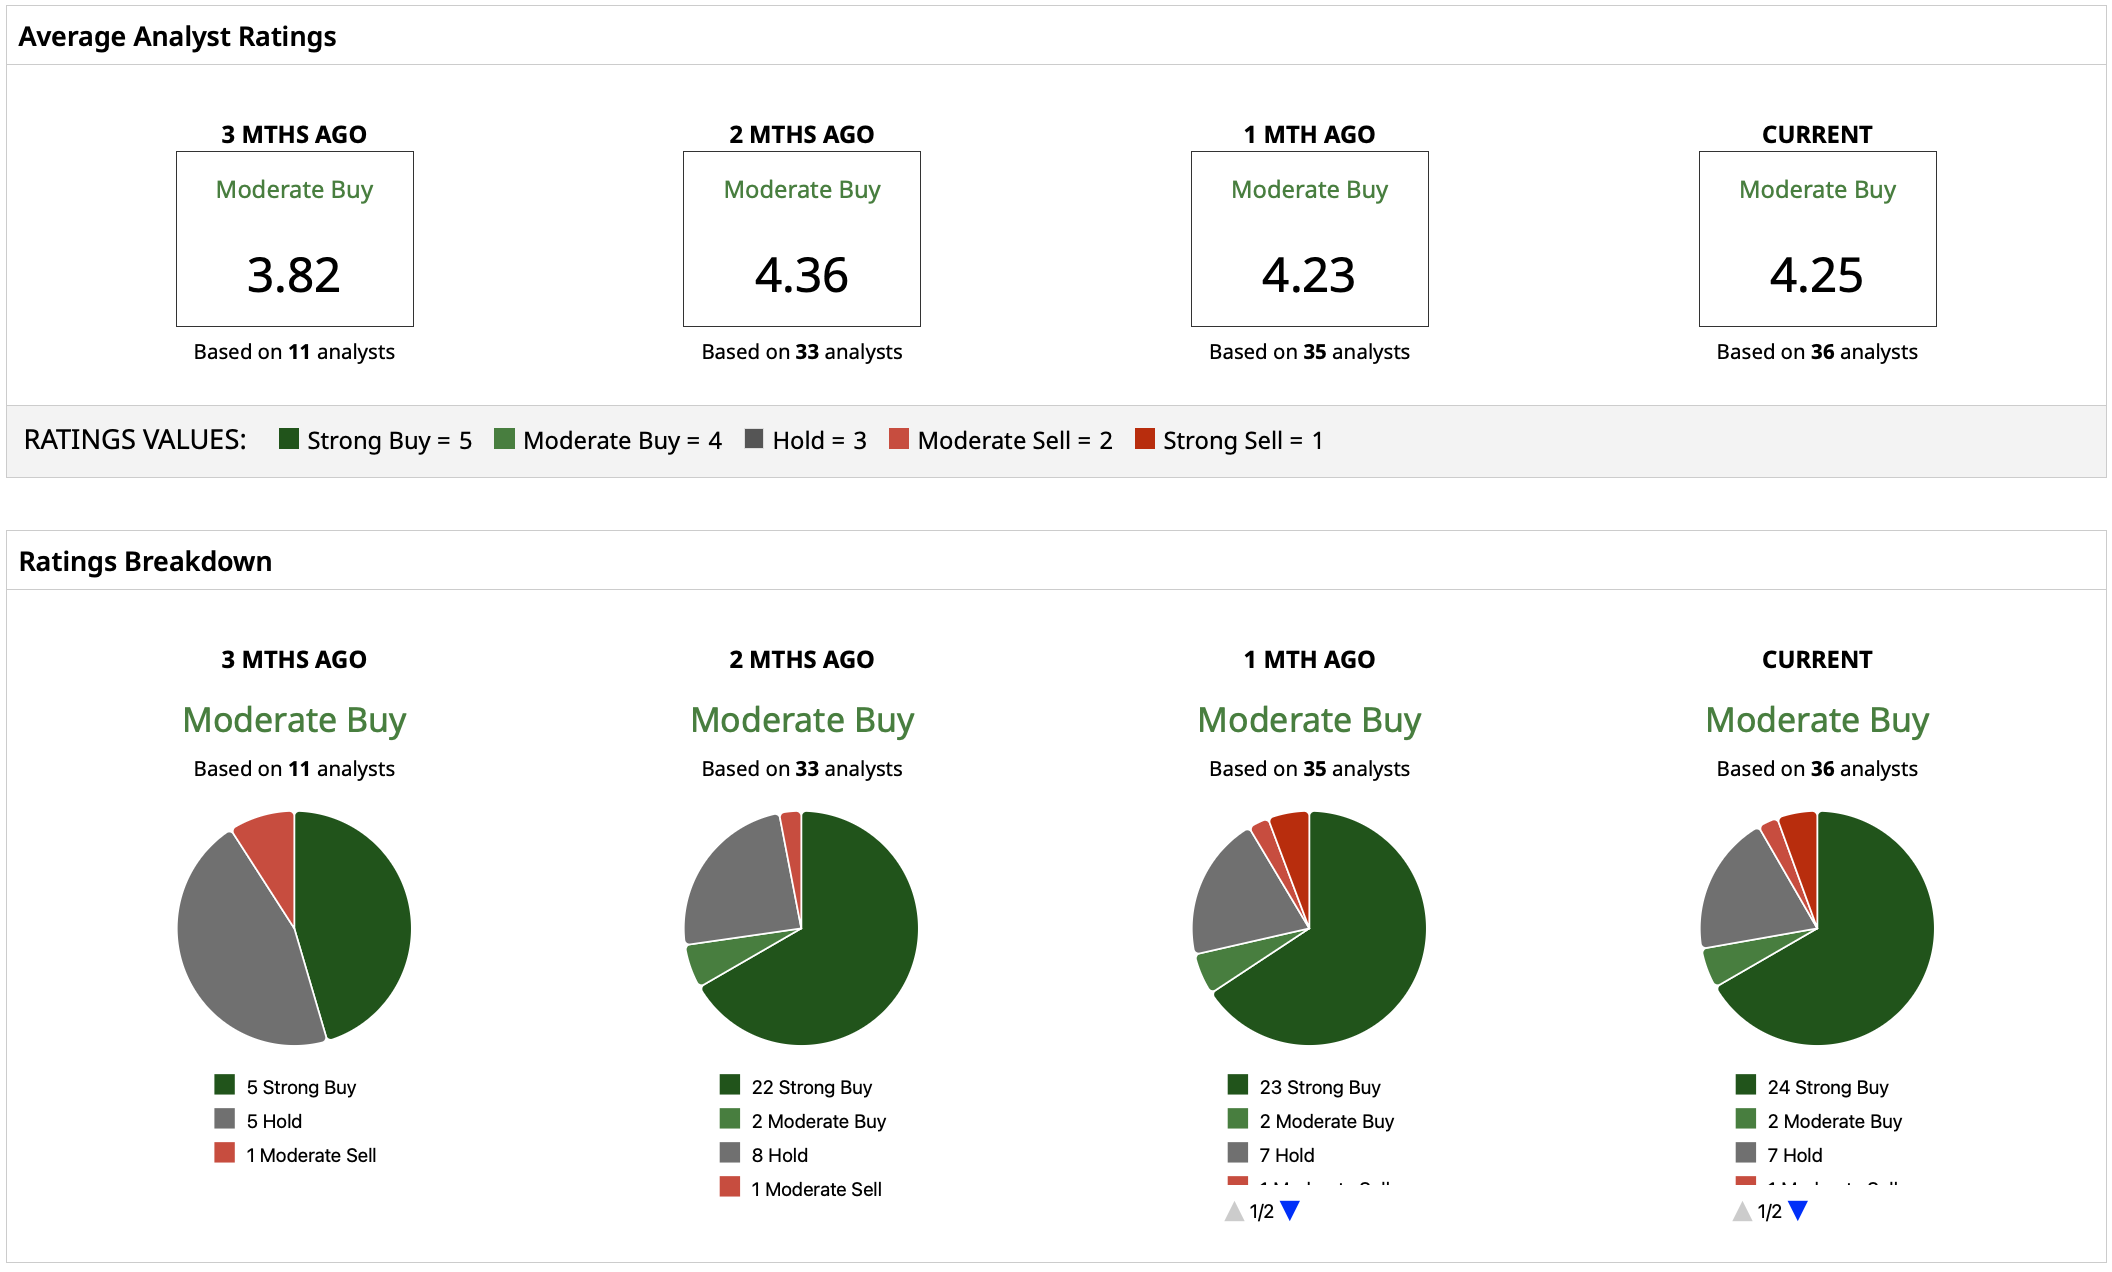
Wall Street appears to be somewhat optimistic about SPCX stock with a consensus “Moderate Buy” rating. Bank of America analyst Ronald Epstein reiterated a “Buy” rating and a $235 price target following Flight 14, highlighting the fact that it proved that the launch system can achieve orbit and successfully deliver the payload. TD Cowen also started coverage of SPCX stock with a “Buy” rating and a $200 price target. Analyst John Blackledge believes SpaceX has a big AI and space opportunity, with terrestrial AI compute leasing poised to become SpaceX's biggest revenue source.
The Street-high price target for SpaceX stock comes in at $800, while the low target is just $75 per share. The mean price target of $220.31 represents potential upside of about 38% from current levels.
This range of opinions is something to be aware of as SpaceX rapidly grows, making progress with Starship as its AI division becomes a source of additional revenue. On the other hand, the company already has a P/S ratio of more than 100 times. This means that a lot of success is already priced into SPCX stock. For now, SpaceX has gained additional growth support from its successful launch and new “Buy” rating, but it still has to catch up with its valuation.