
Shares of Lennar Corporation (LEN) have been hit hard on Wall Street, with persistent housing market headwinds sending its stock deep into the red in 2026. Elevated mortgage rates, sluggish housing demand, lower average selling prices, and shrinking gross margins fueled by aggressive pricing incentives have weighed heavily on the homebuilder. Add a string of analyst downgrades to the mix, and it’s easy to see why investor confidence has taken a beating.
But Lennar may have a chance to turn the tide. The homebuilder is set to report its fiscal 2026 third-quarter earnings after market hours on Wednesday, Sept. 16, putting the stock back in the spotlight. Investors will be watching closely for any signs of recovery and, more importantly, clues that the housing giant’s rough stretch could finally be coming to an end. With a major catalyst just around the corner, here’s a closer look at Lennar stock ahead of its earnings report.
About Lennar Stock
Founded in 1954, Florida-based Lennar Corporation is one of the nation’s leading homebuilders, with “Quality, Value, and Integrity” as its core principles. These principles form the foundation of the company’s operations, shaping how it serves its customers, associates, and shareholders. By putting its company, customers, and associates first, Lennar aims to deliver the best possible results for its shareholders.
With a mission to make the American dream of homeownership attainable for more people, Lennar has built more than 1.5 million homes since its founding. Its communities cater to buyers at every stage of life, from first-time and move-up buyers to active adults, helping families find homes across the country. Beyond homebuilding, Lennar’s Financial Services segment adds another layer to its business, providing mortgage financing, title, and closing services primarily for buyers of Lennar homes.
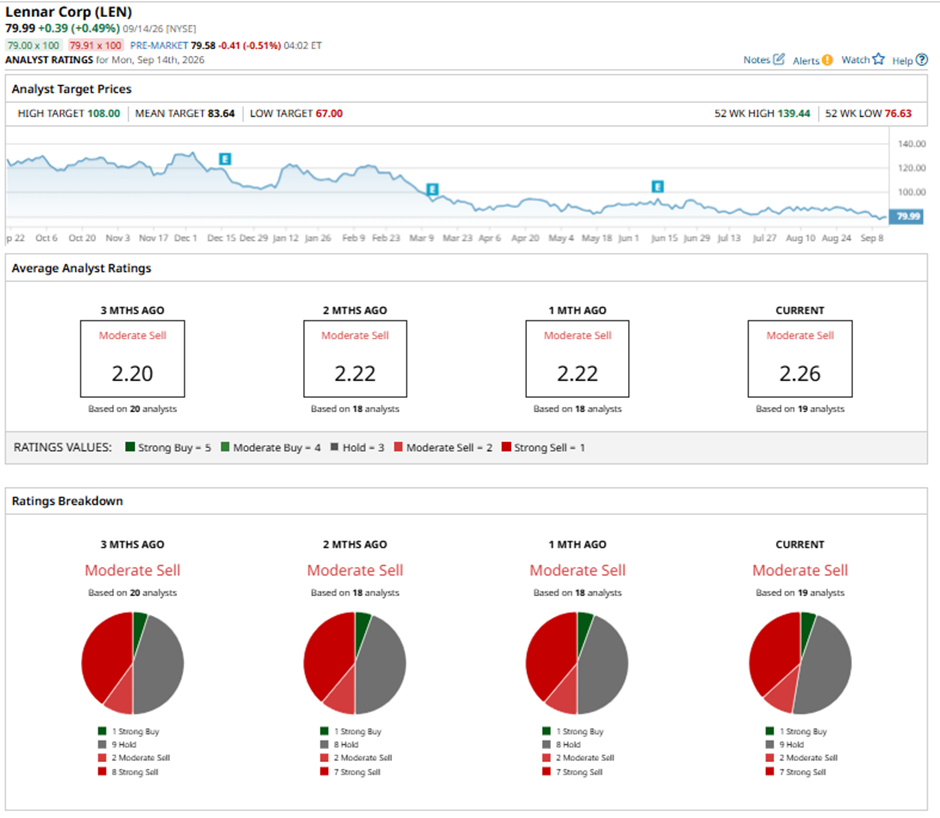
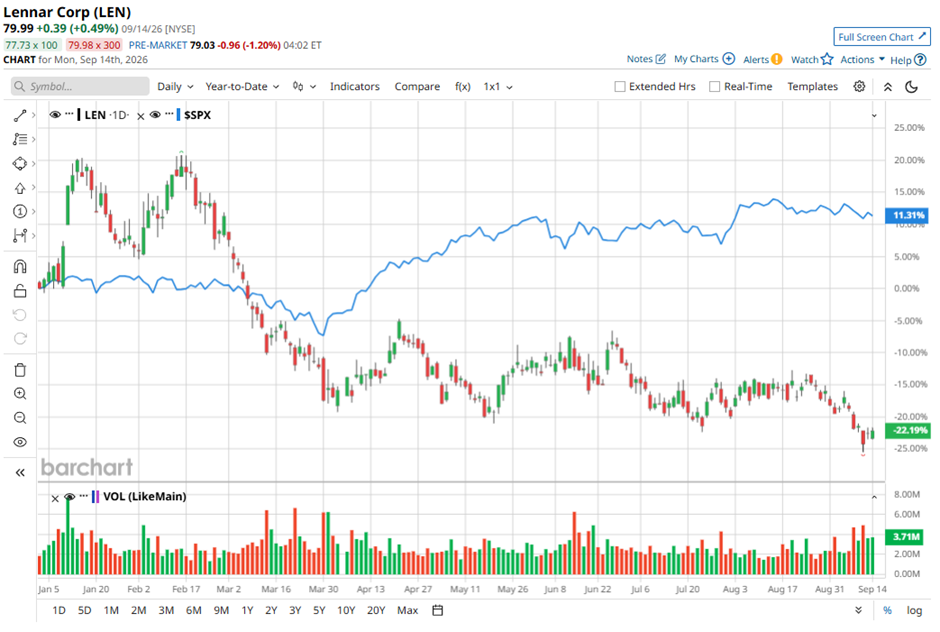
Despite its sizable footprint in the homebuilding industry, Lennar’s stock has struggled to keep pace with the broader market. Currently valued at a market capitalization of approximately $19.27 billion, the homebuilder has delivered disappointing returns for investors over the past few years. Shares have plunged nearly 41.7% over the past year and are down roughly 22.2% so far in 2026, sharply underperforming the broader S&P 500 Index ($SPX).
By comparison, the benchmark has gained about 15.7% over the past year and 11.3% year to date, highlighting just how steep Lennar’s recent slide has been. After hitting a 52-week high of $139.44 in September last year, Lennar shares have since plunged nearly 42.6% from that peak, highlighting the steep selloff that has battered the homebuilder’s stock.
Inside Lennar’s Q2 Earnings Report
Lennar Corporation reported its fiscal 2026 second-quarter financial results on June 11, delivering a mixed performance marked by margin compression, lower net earnings, and continued affordability challenges. While adjusted earnings managed to beat expectations, weaker revenue and declining profitability highlighted the pressure still facing the homebuilder. Total revenue for the quarter fell 5.2% year-over-year (YoY) to $7.94 billion, missing Wall Street’s estimate of $8.07 billion.
Home sales revenue also declined 2% in the second quarter of fiscal 2026, coming in at $7.6 billion compared to $7.8 billion in the same period last year. The pressure was even more visible on the bottom line. Net earnings attributable to Lennar dropped to $305 million, or $1.24 per diluted share, from $477 million, or $1.81 per share, a year earlier. However, excluding pretax mark-to-market losses on technology investments, adjusted earnings per share came in at $1.31, beating consensus expectations of $1.23.
On the operational front, Lennar delivered a modest improvement. Home deliveries rose 2% YoY to 20,519 homes, landing squarely within management’s previously issued guidance range. However, new orders declined 4% to 21,749 homes as prospective buyers continued to grapple with persistent affordability challenges.
Lennar’s profitability metrics reflected the broader pressures weighing on the housing sector. Gross margin on home sales fell to 15.6% from 17.8% a year earlier, pressured by lower revenue per square foot and higher relative land costs. A decrease in construction costs partially offset these pressures, reflecting the company’s continued focus on cost-saving initiatives.
Management highlighted that the second quarter was shaped by the same stubborn housing market headwinds seen over the past several years, including persistently elevated mortgage rates, constrained affordability, and cautious consumer sentiment. Geopolitical uncertainty further exacerbated these challenges, contributing to a resurgent inflation reading of 4.2% driven by higher energy prices.
Investors were clearly unhappy with the results, as LEN stock dropped almost 5% in the next trading session following the underwhelming Q2 performance. Looking ahead to the company’s upcoming fiscal third-quarter results, management expects to deliver approximately 20,500 to 21,500 homes, with gross margin on home sales improving to approximately 16%.
New orders are projected to range between 21,000 and 22,000, while the average sales price is expected to come in at approximately $375,000 to $380,000. SG&A is also expected to improve toward 8.8% to 9%. However, Lennar is taking a more cautious stance on its full-year outlook. Given current pressure on interest rates and geopolitical uncertainty, management is moderating its target fiscal 2026 deliveries to approximately 82,000 to 83,000 homes.
What Do Analysts Think About LEN Stock?
Ahead of Lennar’s third-quarter earnings report, BofA Securities is taking a more cautious stance on the homebuilder. The firm lowered its price target to $70 from $77 while maintaining an “Underperform” rating on LEN stock, reflecting continued pressure on Lennar’s return on tangible equity. BofA based its revised price target on 0.9 times Lennar’s 12-month forward tangible book value, down from 1.1 times previously.
The lower valuation multiple highlights the firm’s concerns about the company’s profitability and its ability to generate returns for shareholders. The firm also trimmed its earnings per share estimates for fiscal 2026, 2027, and 2028 to $5.49, $6.12, and $7.11, respectively, from previous estimates of $5.51, $6.38, and $7.53.
Overall, Wall Street remains bearish on Lennar, with the homebuilder carrying a consensus “Moderate Sell” rating. Among the 19 analysts covering LEN stock, only one recommends a “Strong Buy,” while nine rate it a “Hold.” Two analysts have a “Moderate Sell” rating, and seven go a step further with a “Strong Sell.”
Despite the overall cautious sentiment, analysts see some upside ahead. The average price target of $83.64 implies a potential 4.6% gain from current levels, while the Street-high target of $108 points to as much as 35% upside. That leaves Lennar with something to prove as investors look for signs of a recovery.