Has the Traditional Grain Harvest Low Begun to Change?
For generations, grain traders have been taught a simple seasonal tendency: as combines roll and newly harvested grain becomes available, selling pressure can weigh on corn and soybean prices. Somewhere around harvest, the market often establishes a seasonal low.
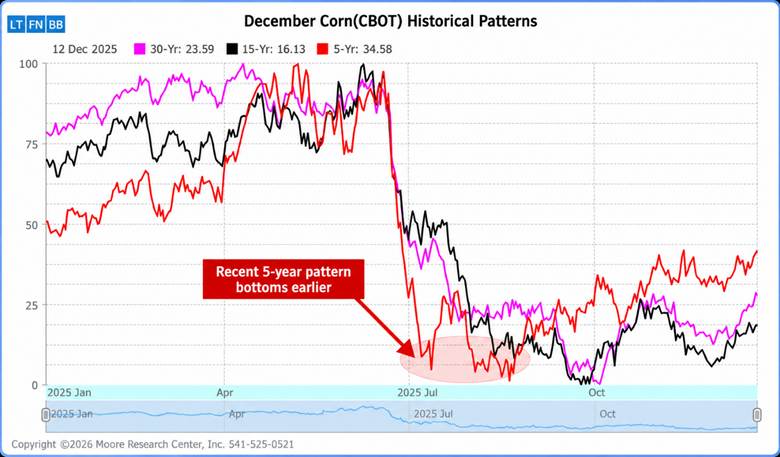
But take a close look at the seasonal patterns for December corn. Something interesting appears to be happening.
Source: Moore Research Center, Inc. (MRCI)
According to Moore Research Center, Inc. (MRCI), the 15- and 30-year seasonal patterns for December corn show the familiar tendency for prices to weaken into the harvest period before recovering. But the five-year pattern has been different. Its seasonal low has tended to arrive earlier.
That raises an interesting question: Could something be changing in the way producers market their grain?
Harvested Doesn't Mean Sold
One of the easiest assumptions for a speculator to make is that a large harvest automatically means a large amount of grain being sold.
It doesn't.
According to the United States Department of Agriculture (USDA), American farmers had 8.70 billion bushels of corn stored on their farms as of December 1, 2025, 14% more than a year earlier.
Even more interesting is how much stored grain can remain unpriced.
According to research from the USDA Economic Research Service (ERS), 38.6% of U.S. corn stocks and 32.9% of soybean stocks were unpriced at the end of 2023. Unpriced corn held by farms increased from approximately 342 million bushels in September to 4.7 billion bushels in December.
Think about that for a moment.
The corn had been harvested. It was sitting somewhere in storage. But billions of bushels were still exposed to future price changes.
Harvest creates supply. It doesn't necessarily create a sale.
The Government Gives Farmers Another Choice
This is where a federal program many speculators probably pay little attention to becomes interesting.
The USDA's Marketing Assistance Loan (MAL) program allows eligible producers to use harvested commodities as collateral for short-term financing.
In plain English, a farmer can harvest corn, put it into storage, borrow against it, and receive needed cash without immediately selling the grain.
This isn't an unintended consequence of the program. According to the USDA, MALs are designed to provide producers with interim financing so they can meet cash-flow needs without selling commodities when prices are typically at harvest-time lows.
For the 2026 crop, national loan rates increased to $2.42 per bushel for corn and $6.82 per bushel for soybeans.
Why Does a Farmer Need Cash?
Harvest may bring grain into the bins, but it doesn't stop the bills.
Farmers may have operating loans and other obligations to pay. They are also beginning to plan for the 2027 crop, including seed, fertilizer, chemicals, machinery expenses, and other production costs. Calendar-year tax planning also becomes increasingly important as December approaches.
Selling grain is one way to raise that cash.
But financing and storage can provide another choice: keep the grain and wait for what the producer believes will be a better price.
That can change the timing of physical selling pressure.
A Farmer Can Finish Harvest and Still Be Long Corn
This is where producers and speculators have more in common than they might think.
Suppose a farmer has corn in the bin that could be sold today but decides to hold it because higher prices are expected next spring.
That farmer has made a price decision.
The grain may have been produced rather than purchased in the market, but unpriced grain still has market risk. If prices rise, holding the grain may prove to have been an excellent marketing decision. If prices fall, the stored inventory's value declines.
Of course, the farmer could hedge the stored corn against lower prices using futures or other risk-management tools. But doing so would also establish much of the corn's price, depending on basis and the hedge used. In that sense, the producer has effectively moved from holding unpriced grain toward pricing the crop, even though the physical corn may still be sitting in the bin.
If the farmer chooses not to sell or hedge because higher prices are expected, the producer is making much the same price decision a speculator makes: accepting downside price risk in hopes of receiving a higher price later.
Storage costs, interest rates, basis, and futures spreads all factor in.
Sometimes the bird in the hand turns out to have been the better price.
Soybeans Tell a Similar Seasonal Story
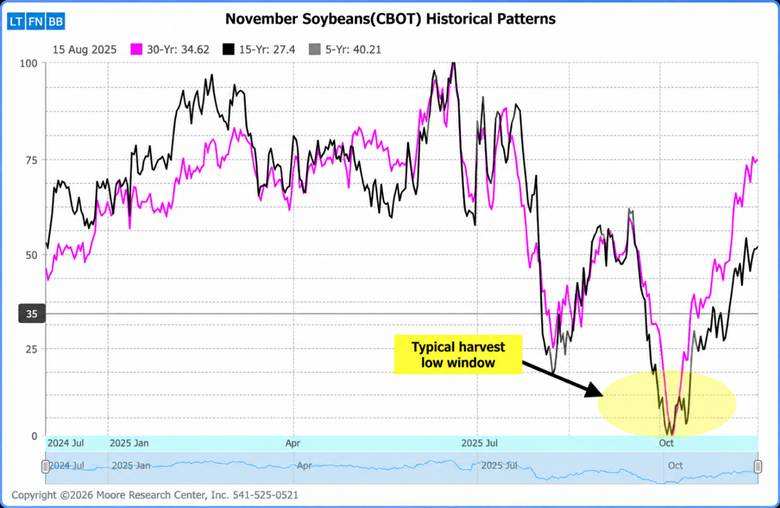
November soybeans have historically shown substantial selling pressure as harvest approaches, followed by a recovery from harvest-period lows.
Source: MRCI
The MRCI chart illustrates why grain traders have watched harvest seasonality for decades.
But storage capacity, financing, and producer marketing decisions remind us that harvest progress and selling pressure aren't the same.
A combine tells us when grain leaves the field. It doesn't tell us when that grain will be priced.
What Should Grain Traders Watch Next?
According to the USDA, U.S. corn stocks totaled 5.29 billion bushels on June 1, 2026, 14% above the previous year, while on-farm corn stocks were up 16%.
The next USDA quarterly Grain Stocks report is scheduled for September 30 and will measure inventories as of September 1, including grain stored both on and off farms.
Grain traders may want to pay particular attention to the amount of old-crop corn still sitting on farms as the new crop moves into storage. Follow the December Corn (ZC) and the November Soybean (ZS) contracts for reactions to this upcoming report.
The report won't tell us how much of that grain remains unpriced. But it can provide another piece of the puzzle when estimating how much potential producer selling remains over the market.
Perhaps the lesson is simpler than all the statistics:
Harvest tells us how much grain farmers have produced. It doesn't tell us when they'll sell it.
And sometimes understanding that difference can tell a speculator more than simply knowing that October has historically been a good month to buy corn.