Shares of CoreWeave (NASDAQ: CRWV) are getting a lift after Oracle (NYSE: ORCL) delivered a force majeure order to Blue Owl Capital(NYSE: OWL) for its Project Jupiter. Oracle wants to defer payments to Slack Infrastructure, the developer owned by Blue Owl, if the data center project doesn't open in 2028.
Bulls are latching onto the idea that new data center capacity is becoming more likely to be delayed. In that case, neocloud companies such as CoreWeave, Iren (NASDAQ: IREN) and Nebius Group (NASDAQ: NBIS), which have existing capacity, will become more valuable.
After initially dropping over 7% between Sept. 24 and the market open on Sept. 28, CRWV roared back. But should investors ride this momentum higher? Recent analyst ratings offer differing opinions on CRWV.
Same Stock, 2 Different Outlooks
In the same week as Oracle's force majeure notice, CoreWeave received two fresh analyst ratings with polar opposite outlooks. On Sept. 24, the same day as the Oracle notice, JPMorgan Chase upgraded CRWV from Neutral to Overweight and raised its price target to $125 from $120.
The firm focused on the company's pricing power. The thinking is that, like the entertainment industry, buyers who book late pay a higher price. Even if these buyers balk at the higher rate, CoreWeave will fill its $104.20 billion revenue backlog, which is up 246% year over year.
Rothschild took the other side of the outlook for AI infrastructure. The firm initiated coverage on CoreWeave with a Sell rating and a $54 price target. That would be a drop of over 38% from its price as of this writing.
The concern is the company's debt burden. CoreWeave spent $9.4 billion in capital expenditures (CapEx) in the quarter and carries a debt-to-equity ratio of 5.54 on a market cap of $40 billion.
Why Data Center Delays Could Boost CoreWeave's Pricing Power
The bull case rests on scarcity. Every delayed project like Project Jupiter keeps AI compute capacity tight. Developers building and running AI models can't wait until 2028. They need GPUs that are online today, and CoreWeave already has them. Tight supply gives the company leverage when contracts come up for renewal or new customers show up late. That's the core of JPMorgan's thesis.
The backlog adds a layer of visibility that few growth stocks enjoy. At $104.2 billion, contracted revenue is more than double the company's roughly $40 billion market cap. In other words, investors are paying less than half of what customers have already committed to spend. If CoreWeave executes, today's heavy spending turns into years of recurring revenue. From this view, the Oracle headline isn't a warning for the sector. It's proof that existing capacity is the scarcest asset in AI.
CoreWeave's Debt Load Leaves Little Room for Error
Rothschild's argument isn't about demand. It's about how CoreWeave pays for growth. The company funds much of its buildout with borrowed money. A debt-to-equity ratio of 5.54 means it leans far more on lenders than on shareholder capital. As that debt grows, so do interest costs. That's a key reason net losses keep widening even as revenue climbs.
There's also a timing mismatch. CoreWeave spends billions today on GPUs and data centers, but backlog revenue arrives over several years. Meanwhile, those chips lose value as newer generations launch. If pricing softens before contracts are fulfilled, returns on that spending shrink.
Perception versus reality adds to the complexity surrounding neocloud stocks. A backlog is a commitment, not cash in the bank. Plus, a large share is tied to a small number of customers. Oracle's force majeure notice shows how quickly assumed timelines can change.
Is CRWV a Buy? The Upside Depends on Execution
Despite being down more than 8% since July, CRWV is still up over 20% in 2026. Its consensus price target of $138.78 implies approximately 60% upside from recent trading levels. For investors who believe in the bull case, there's plenty of upside. And looking at the broader analysts' outlook, Rothschild appears to be the extreme outlier.
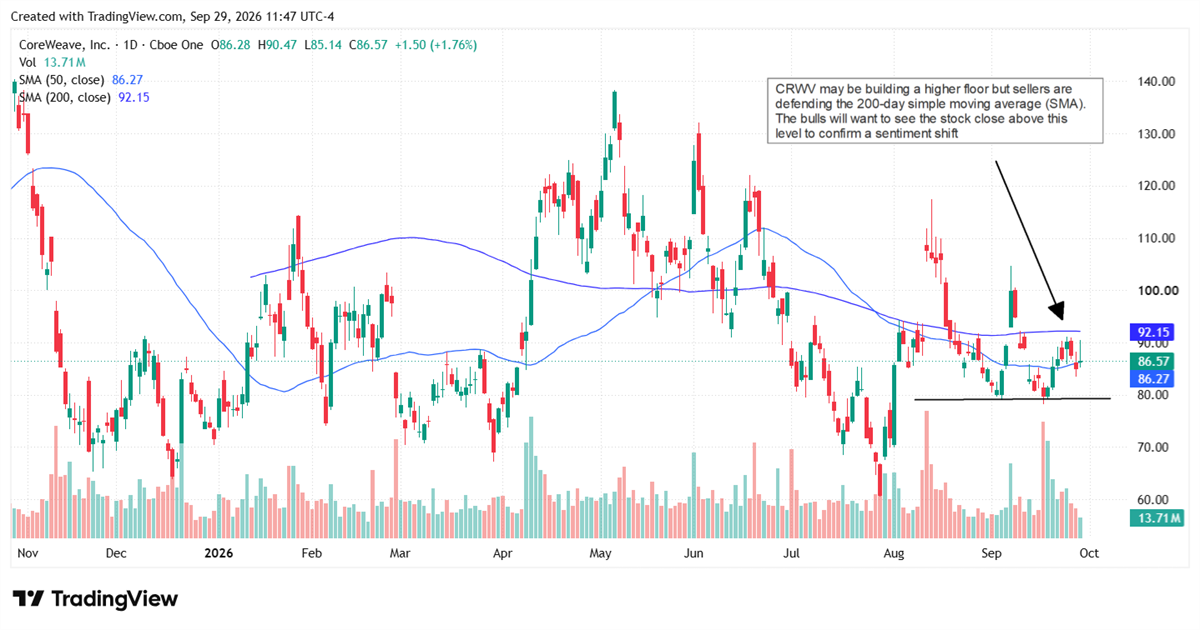
The chart offers a cautious signal. CRWV has held near $80 twice in September, well above its late-July low near $62. That suggests buyers may be building a higher bottom. The stock currently sits just above its 50-day simple moving average (SMA) of $86.27.
The bigger test is the 200-day SMA near $92. On Tuesday, Sept. 29, CRWV touched $90.47 before fading, showing sellers are still defending that level. A close above both averages would signal a real shift in sentiment. Until then, the stock is coiling between roughly $80 and $92, and a break below that floor would undercut the bullish setup.
However, the risks are real. The company raised its CapEx guidance for the year to a range between $35 billion and $39 billion. Keep in mind, the company isn't profitable yet, and its net losses are widening. This is far from a clean balance sheet, and anything shy of flawless execution may put pressure on the stock.
The article "CoreWeave Comes With Risks: Analysts Split on What Matters Most" first appeared on MarketBeat.